克里斯·休斯撰文 电信大亨帕特里克·德拉希将其美国有线电视帝国的债权人逼入绝境,后者随即提起一份长达165页的大型诉讼进行反击。这是一场围绕着逐渐融化的冰块展开的绝望争夺。但这个故事应成为信贷投资者的必读教材,因为它极其生动地说明了借贷给精明的控股股东所面临的风险。
By Chris Hughes Telecom tycoon Patrick Drahi has nudged creditors at his US cable empire into a corner and they’re pushing back with a jumbo 165-page lawsuit. It’s a desperate fight over a melting ice cube. But the tale should be required reading for credit investors given how neatly it illustrates the risks of lending to a smart controlling shareholder.
Optimum Communications Inc.(奥普特姆通信公司)身处竞争惨烈的美国宽带行业。其净债务高达250亿美元,而企业价值或许仅约160亿美元(基于同业估值倍数测算)。在此基础上,股权已毫无价值,迟早需要通过削减借款的重组来解决。这家在纽约上市的股票所残存的微薄价值,仅反映出普通股东在此类情况解决时,有时能分得几许微薄施舍。
Optimum Communications Inc. operates in the viciously competitive US broadband industry. It has $25 billion of net debt versus an enterprise value of perhaps only around $16 billion (based on the valuation multiples of its peers). On that basis, the equity is worthless and a restructuring that slashes borrowings will be needed one day. What little value remains in the New York-listed stock merely reflects how ordinary shareholders sometimes receive a few paltry goodies when such situations get resolved.
德拉希通过超级投票权股份控制Optimum。他过去曾证明自己擅长从资不抵债中挽救残值,此次亦在重施故技。
Drahi controls Optimum through super-voting stock. He’s proven himself a master at salvaging something from negative equity in the past, and he’s been at it again here.
关键转折发生在去年11月,当时Optimum对一笔贷款进行了再融资,移除了禁止其以现有借款抵押品为担保发行新债的契约条款。解除这一限制后,德拉希创建了一个新的孤岛实体“Optimum East”(奥普特姆东部),纳入长岛和康涅狄格州等地区的业务。
The critical turn came last November when Optimum refinanced a loan with covenants preventing it from raising new debt against collateral pledged to existing borrowings. With that constraint removed, Drahi created a new silo, Optimum East, to house operations serving areas such as Long Island and Connecticut.
原有业务现更名为“Optimum West”(奥普特姆西部),仅剩10亿美元息税折旧摊销前利润(EBITDA)来支撑其高达220亿美元的巨额净债务。这些借款中,超过60亿美元将于2027年到期。新成立的Optimum East所承接的资产产生约20亿美元EBITDA,但债务规模适中(为再融资那笔限制性贷款而承担),且拥有充足的额外借贷能力。
The original business, now dubbed Optimum West, was left with only $1 billion of earnings before interest, tax, depreciation and amortization to support its colossal $22 billion of net debt. Of those borrowings, more than $6 billion falls due in 2027. The assets assumed by the newly established Optimum East generate around $2 billion of Ebitda. But it has modest debt (taken on to refinance the restrictive loan) and plenty of spare borrowing capacity.
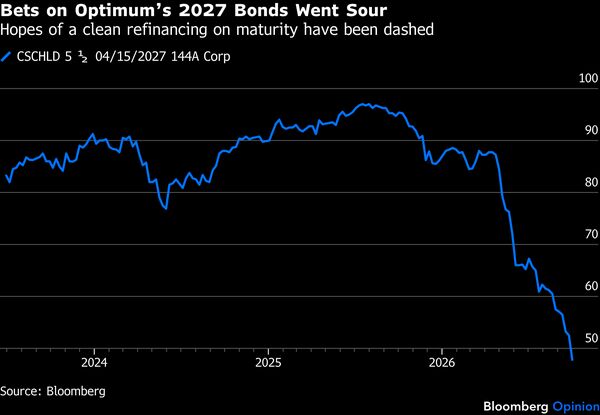
尽管 Optimum West 的信用指标急剧恶化,但其 2027 年到期的债券价格在 12 月至 4 月期间仅比面值低 10% 至 15% 左右。市场普遍认为,Drahi 很可能会从 Optimum East 那里筹集更多资金来偿还这些债券,从而避免明年出现财务危机——这似乎是一个快速获利的机会。
Despite this savage deterioration in Optimum West’s credit metrics, its bonds maturing in 2027 were trading at only around 10% to 15% below par from December to April. The market view appeared to be that Drahi would likely raise further cash at Optimum East to settle the bonds and avoid a crunch next year.
然而,事实证明这种看法大错特错。6 月份,随着 Optimum 加快重组谈判的步伐,这些债券的价格进一步下跌。更糟糕的是,Optimum 向 Drahi 及其他投资者发行了约 5 亿美元的优先债券;这些优先债券在该公司破产时可以兑换成 13 亿美元。对于处境艰难的 Optimum West 的债权人来说,原本还有一个安慰:如果公司倒闭,他们有权获得 Optimum East 的股权。然而,这些优先债券也会侵蚀他们的权益……真是厚颜无耻至极。
Here, it seemed, was the chance for a quick buck. How wrong that was. The price of the 2027 debt slid in June as Optimum moved to accelerate restructuring talks. Worse, Optimum issued around $500 million of preferred securities to Drahi and other investors that could be redeemed for $1.3 billion in a bankruptcy. One comfort for Optimum West’s beleaguered creditors had been their entitlement to Optimum East’s equity if the company collapsed. The preferred securities would take a bite out of this too. What cheek.
Optimum 表示这些交易完全符合债务协议和法律法规。但债权人指责这些行为属于“欺诈性转让”以及违反信托责任,这也情有可原;他们将这些行为称为“明目张胆的欺诈行为”,确实也很难反驳。不过,目前仍无法确定是否存在任何违法行为。
Optimum says the transactions fully complied with the debt agreements and the law. Butyou can’t blame the creditors for alleging they’re “fraudulent transfers” and a breach of fiduciary duty. And it’s hard to disagree with their characterization of it as “brazen.”All the same, it’s far from clear anything illegal has taken place.
首先,Drahi 并没有利用这次公司拆分为东西两部分的机会为自己谋取巨额利益;他只是用新的债务替换了旧的债务,重新调整了公司的资产结构而已。此外,从债权人签署的协议条款来看,这种资产转移行为似乎也不被禁止。
For starters, Drahi did not use the East-West split to take out a massive dividend for himself. He just replaced old debt with new and rearranged the deck chairs. Nor is it obvious that this asset-shifting was forbidden under the terms creditors signed up for.
事实上,一些市场参与者早已预见到这场危机。研究机构CreditSights去年就曾向客户警示相关风险。信贷基金CrossingBridge Advisors LLC曾通过博客文章阐述,为何选择投资Optimum East的新发债务,而非收益率更高的Optimum West债务,理由是“资本返还比资本回报更为重要”。优先证券更有可能以债权人的利益为代价,使德拉希(Drahi)获利。话虽如此,外部投资者也参与了投资,这为Optimum提供了一定的辩护空间,即慷慨的偿付条款是由市场决定的。
Indeed, some market participants saw the iceberg coming. Research provider CreditSights was warning clients of the risks last year. Credit fund CrossingBridge Advisors LLC has blogged about how it chose to invest in the new debt at Optimum East rather than the higher-yielding debt at Optimum West because “return of capital is more important than return on capital.”The preferred securities more clearly stand to enrich Drahi at creditors’ expense. That said, external investors also participated, providing Optimum with the potential defense that the generous payback terms were set by the market.
本案双方均具备高度的专业性。包括阿波罗全球管理公司(Apollo Global Management Inc.)和Ares Management Corp.在内的债券持有人,理应已充分理解合同中的细微条款。正如彭博智能(Bloomberg Intelligence)所指出的,案件的关键更可能在于交易发生的原因,而非信贷文件所允许的内容。动机至关重要。债权人需要证明存在明确的意图,旨在剥夺其价值。这取决于若获准对Optimum的电子邮件进行证据开示,他们能挖掘出什么。
Both sides here are highly sophisticated. The bondholders, including Apollo Global Management Inc. and Ares Management Corp., will have understood the small print. The case more likely turns on why the transactions happened rather than what the credit documents allowed, as Bloomberg Intelligence points out. Motives matter. The creditors need to provethere was a clear intention to deprive them of value. That depends on what they unearth if they’re granted discovery of Optimum’s inboxes.
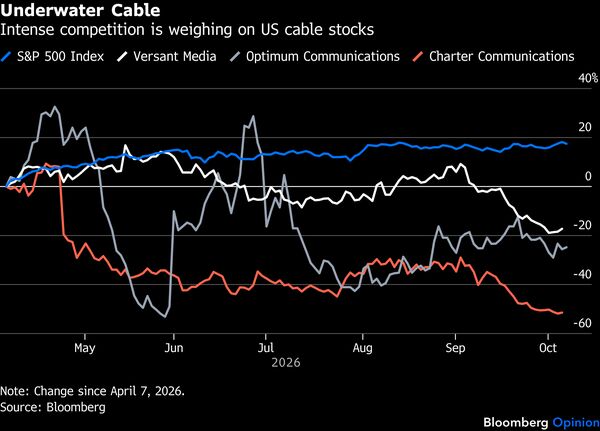
某些困境债务情形可能带来丰厚回报,但这一案例却是一团糟。尽管债券价格已计入大量痛苦预期,仍难以看出有利的交易机会。假设最终进行债转股,这些股份将如何被有利可图地变现?Optimum的宽带同行业绩惨淡。理论上,特许通信公司(Charter Communications Inc.)可能是潜在买家,但其自身已面临诸多挑战。
Some distressed-debt situations can be highly lucrative. This one is just a mess. Even with a lot of pain now priced into the bonds, it’s hard to see a winning trading opportunity. Suppose there’s ultimately a debt-for-equity swap. How will those shares ever be profitably monetized? The readouts from Optimum’s broadband peers are grim. Charter Communications Inc. is, in theory, a potential buyer, but it has enough on its plate.
当然,这场诉讼具有骚扰价值。这增强了债权人在未来重组谈判中的地位——但随之而来的是高昂的费用和麻烦。正如BI所言,这是一场大规模的胆小鬼博弈。
Of course, this lawsuit has nuisance value. That strengthens creditors’ hand in any negotiations on a future restructuring — but what a lot of fees and hassle. As BI says, it’s a big game of chicken.
像德拉希这样的控股股东,会动用一切手段保护其股权。那些意识到这一点并避开Optimum的投资者,将毫无遗憾。有时,最聪明的困境债务交易就是放弃。
Controlling shareholders like Drahi will pull every lever to protect their equity. Investors who were mindful of that and avoided Optimum won’t have any regrets at all. Sometimes the cleverest distressed trade is to pass. To contact the author of this story: at chughes89@bloomberg.net