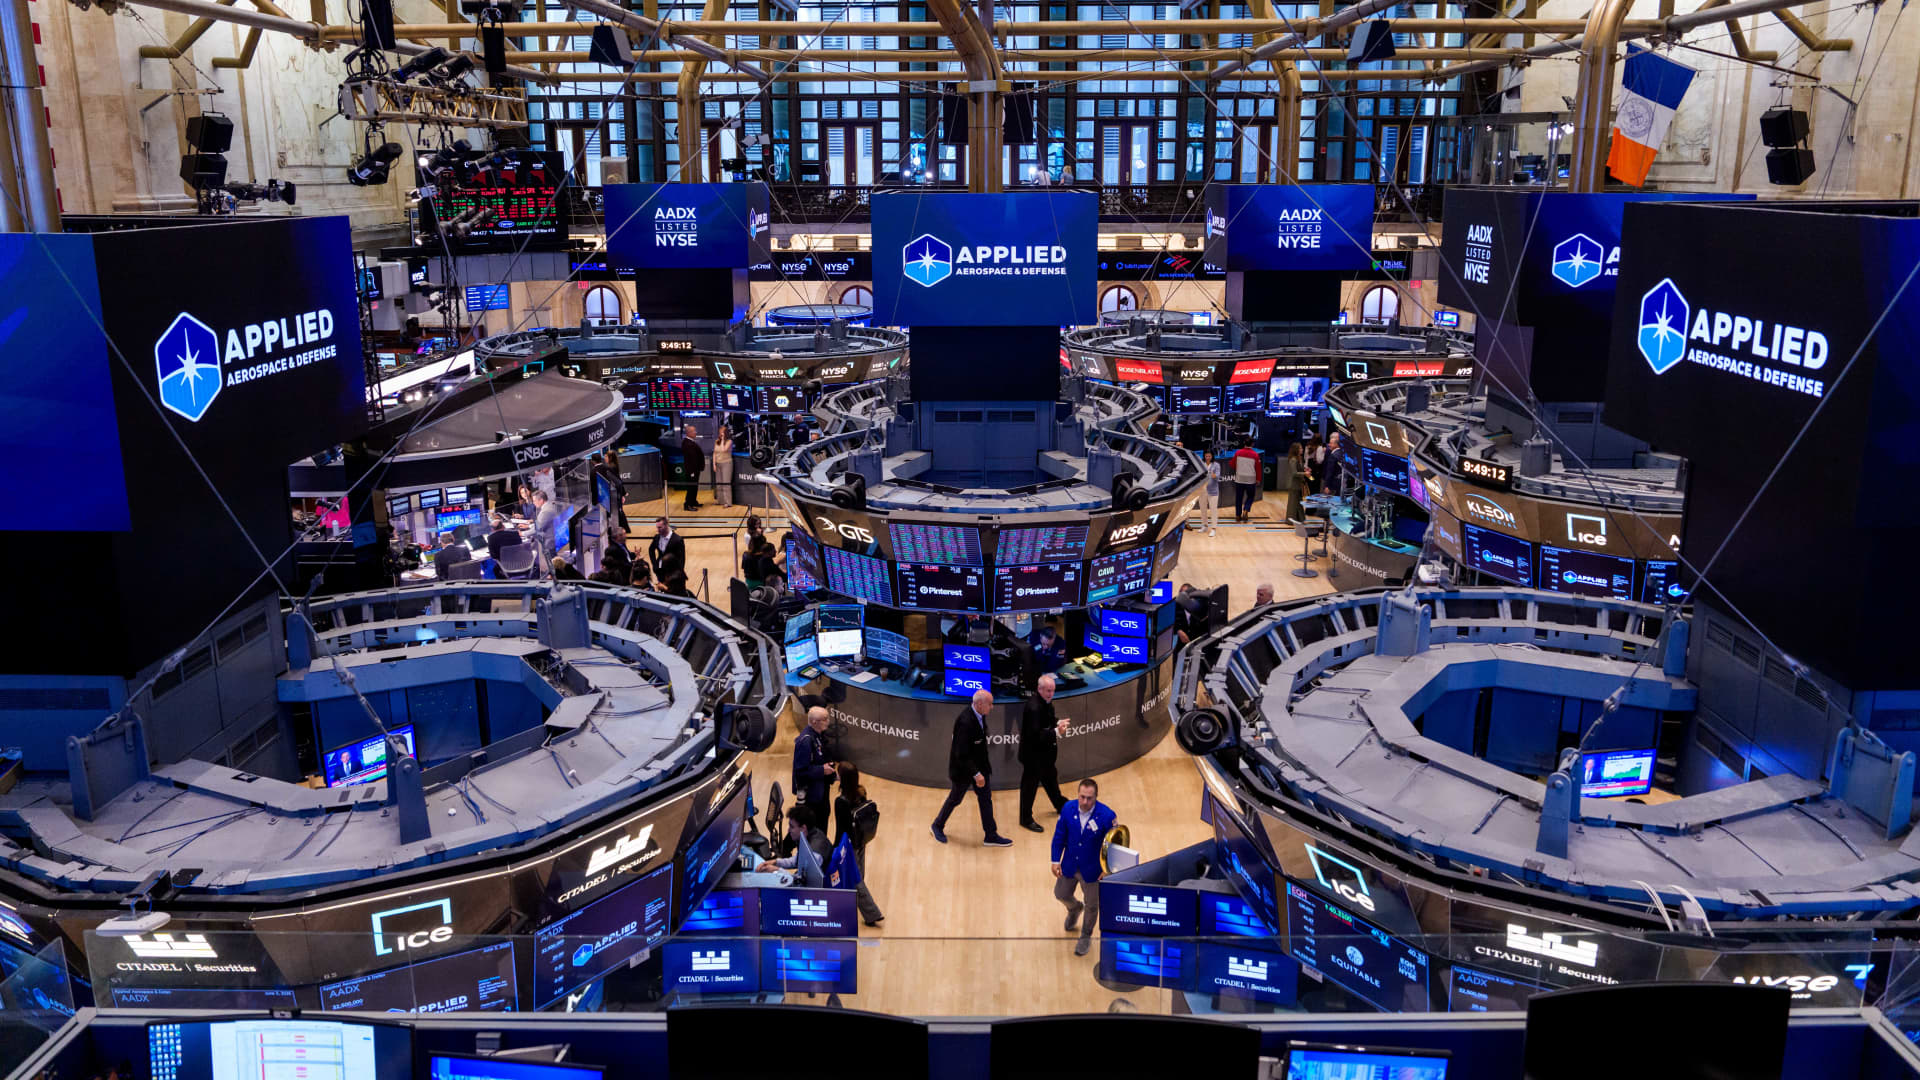
应用航空航天与国防股份定价错误。该股在第二季度亏损后跌破6月份的IPO价格,主要是由于一次性问题,掩盖了其增长潜力。这家国防公司提供嵌入式、循环性的经济学。其约87%的收入来自其作为唯一供应商的产品销售,三分之一与长寿命售后市场和维持计划有关。Applied Aerospace在下一代国防和太空计划中拥有战略地位,但该股的股价低于TransDigm和HEICO等同行。
Applied Aerospace & Defense shares are mispriced. The stock fell below its June IPO price after a second-quarter loss, largely due to one-time issues, masking its growth potential. The defense company offers embedded, recurring economics. About 87% of its revenue comes from the sale of products of which it is the sole supplier, and one-third is tied to long-life aftermarket and sustainment programs. Applied Aerospace has strategic positions in next-generation defense and space programs, yet the stock trades below peers such as TransDigm and HEICO.
当一家新上市公司的价值在上市后几个月内下跌超过三分之一时,投资者通常会争先恐后地退出。但这家国防和航天工业的供应商值得仔细研究。6月3日以每股20美元上市的Applied Aerospace & Defense已跌至11.39美元。催化剂是第二季度引人注目的1.54亿美元亏损,这可能导致交易算法按下了卖出按钮。报告的损失是一个会计条目,由1.1亿美元的非经常性、非现金IPO相关股票薪酬和交易费驱动。
When the value of a newly public company drops by more than a third within months of its trading debut, investors usually scramble for the exits. But this supplier to the defense and space industry deserves a closer look. Applied Aerospace & Defense , which went public on June 3 at $20 a share, has collapsed to as low as $11.39. The catalyst was a headline-grabbing second-quarter loss of $154 million that likely sent trading algorithms to hit the sell button. The reported loss was an accounting entry, driven by $110 million in nonrecurring, noncash IPO-related stock compensation and transaction fees.
剔除这些一次性费用,其基础业务强劲加速。调整后的息税折旧及摊销前利润达到创纪录的3640万美元,同比增长38.5%,收入增长47.4%。标准的IPO启动噪音可能被与运营衰退混淆,为更多前瞻性投资者提供了进入一家以大幅折扣交易的关键任务国防公司的更好的切入点。更重要的是,随着这家位于阿拉巴马州亨茨维尔的公司加深与颠覆性国防创新者Anduril Industries和太空发射领导者SpaceX的关系,其增长跑道可能会大幅拓宽。
Strip away these one-time charges, and its underlying business accelerated strongly. Adjusted earnings before interest, taxes, depreciation and amortization was a record $36.4 million, up 38.5% year over year, while revenue grew 47.4%. The standard IPO launch noise may have been confused with operational decay, offering more forward-looking investors an improved entry point into a mission-critical defense company trading at a deep discount. What's more, its growth runway could widen materially as the Huntsville, Alabama, company deepens its relationships with disruptive defense innovator Anduril Industries and space-launch leader SpaceX .
在这两种情况下,这些合作伙伴关系可能会转化为多年来对应用航空航天制造的高价值产品的需求加速。
In both cases, these partnerships could translate into years of accelerating demand for the high-value products Applied Aerospace manufactures.
现代战争的隐形骨架:Applied Aerospace并非一家兜售软件承诺、尚未产生收入的 speculative 科技初创企业,而是一家获得Greenbriar Equity支持的并购整合企业,旗下拥有两家历史悠久的航空航天制造商:成立于1954年的Applied Aerospace Structures,以及业务可追溯至1900年的PCX Aerosystems。该私募股权公司于2022年收购Applied Aerospace,2025年底将其与PCX合并,并在推动公司上市前纳入Vestigo Aerospace。
The invisible skeleton of modern warfare Applied Aerospace is not a speculative, pre-revenue technology startup selling software promises. It's a Greenbriar Equity-backed roll-up built around two long-established aerospace manufacturers: Applied Aerospace Structures, founded in 1954, and PCX Aerosystems, whose roots date to 1900. The private equity firm acquired Applied in 2022, merged it with PCX in late 2025, and added Vestigo Aerospace before taking it public.
公司在六个州运营11座专门建设的设施,总面积达150万平方英尺。其产品或许并不光鲜,但高度复杂且难以替代,因为现代飞行、火箭投送和电子战都依赖这些产品才能正常运转。Applied Aerospace的业务覆盖三个结构性繁荣的终端市场:太空与发射系统(约占收入的23%):随着太空准入从少数精英参与的科学探索转向高频商业活动,Applied Aerospace主要制造主结构零部件,包括推进剂贮箱、发动机喷嘴、头锥、热防护有效载荷整流罩和先进可部署太阳能阵列。
The company operates 11 purpose-built facilities spanning 1.5 million square feet across six states. Its products may be unglamorous, but they are also highly complex and difficult to replace as they make modern flight, rocket delivery and electronic warfare functional. Applied Aerospace feeds into three structurally booming end-markets: Space and launch systems (~23% of revenue): In an era when space access is transitioning from an elite scientific pursuit to a high-cadence commercial business, Applied Aerospace manufactures primary structural parts and components. These include propellant tanks, engine nozzles, nose cones, thermal payload fairings and advanced deployable solar arrays.
国防航空与机载系统(约占收入的30%):该部门为先进军用飞机制造复合材料机翼、飞行控制翼面、发动机轴和强化机身结构,帮助盟国在日益动荡的地缘政治格局中保持空中优势。C5ISR与精确打击平台(约占收入的47%):这是Applied Aerospace增长最快的业务板块,为现代指挥与控制、网络情报、监视和侦察网络提供实体硬件,将战场数据转化为行动。
Defense aviation and airborne systems (~30% of revenue): This segment manufactures composite wings, flight control surfaces, engine shafts, and ruggedized fuselage structures for elite military aircraft, ensuring allied air dominance in an increasingly unstable geopolitical landscape. C5ISR and precision strike platforms (~47% of revenue): Applied Aerospace's fastest-growing segment supplies the physical hardware behind modern command-and-control, cyber intelligence, surveillance, and reconnaissance networks, the systems that turn battlefield data into action.
公司制造固体火箭发动机壳体、特种导弹弹体,以及用于保护雷达和拦截器的专用雷达罩。
The company manufactures solid-rocket-motor cases, specialized missile bodies, and radar- and interceptor-protecting radomes.
随着防御从传统装甲转向互联的导弹防御网格和实时瞄准,其组件对于使这些网络发挥作用的武器和传感系统变得越来越重要。灵活定价能力的能力应用航空航天投资论点的皇冠上的明珠在于其87%的单一来源合同组合。在商业领域,垄断企业面临激烈的诉讼。在国防子系统领域,它们代表着令人垂涎的竞争堡垒。当五角大楼或航空航天承包商设计价值数十亿美元的平台时,它会对特定的供应商进行资格审查,直到最小的细节。
As defense shifts from traditional armor toward connected missile-defense grids and real-time targeting, its components become increasingly central to the weapons and sensing systems that make those networks work. Ability to flex pricing power The crown jewel of Applied Aerospace's investment thesis lies in its 87% single-source contract mix. In the commercial sector, monopolies are fiercely litigated. In the defense subsystems sector, they represent a coveted competitive fortress. When a primary Pentagon or aerospace contractor designs a multibillion-dollar platform, it qualifies specific suppliers down to the smallest detail.
Applied Aerospace的专有和针对客户的特定制造工艺,包括Nadcap认证的化学加工和热处理,以及复杂的多材料粘合,都深深嵌入这些长寿命平台中。这一资格历史有助于解释其平均39年的客户关系长度。由于太空和国防资格周期需要多年详尽的安全和性能认证,因此对于主承包商来说,转向更便宜的竞争对手是很有摩擦的。
Applied Aerospace's proprietary and customer-specific manufacturing processes, including Nadcap-accredited chemical processing and heat treating, as well as complex multimaterial bonding, are deeply embedded in these long-lived platforms. That qualification history helps explain its average customer relationship length of 39 years. Because space and defense qualification cycles require multiple years of exhaustive safety and performance certifications, switching to a cheaper competitor is highly frictional for a prime contractor.
这创造了一定程度的客户粘性和定价能力,这在公开市场上很难找到。此外,应用航空航天公司2025年约三分之一的收入来自售后市场和维护计划中使用的系统。这提供了长期的收入可见性,因为基础平台的使用寿命很长。一旦该公司为持久的军事或航空航天平台提供部件,它就可以通过更换、维修、大修和使用寿命延长周期来支持该计划多年(通常是几十年)。
This creates a level of customer stickiness and pricing power that is difficult to find in the public markets. Furthermore, about a third of Applied Aerospace's 2025 revenue came from systems used in aftermarket and sustainment programs. This provides long-term revenue visibility, because the underlying platforms have lengthy service lives. Once the company supplies a component for an enduring military or aerospace platform, it can support that program through replacement, repair, overhaul, and service-life-extension cycles for many years — often decades.
结果是产生经常性且相对可预测的收入来源,从而减少了经济周期性。宝贵的合作伙伴关系:SpaceX与Anduril Applied Aerospace(应用航空航天)故事中最令人印象深刻的方面,在于其拥有观察军工复合体重塑过程的前排座位。过去三十年里,国防采购一直是一个停滞的寡头垄断市场,由少数庞大的传统主承包商主导,研发周期漫长且采用痛苦的成本加成模式。
The result is a recurring and relatively predictable revenue stream that reduces economic cyclicity. Valuable partnerships: SpaceX and Anduril The most impressive aspect of the Applied Aerospace story is its front-row seat to the remaking of the military-industrial complex. For the past three decades, defense procurement was a stagnant oligopoly dominated by a handful of massive legacy prime contractors and painfully slow cost-plus research-and-development cycles.
乌克兰战争和中东冲突凸显了无人机、自主系统、精确打击、电子战和弹性战场网络如何能迅速重塑战区。风投支持的国防技术新进入者正在加速向软件定义、自主系统和更快生产周期的转变,提升了能够快速进行原型制作、认证和规模化复杂硬件的制造合作伙伴的价值。Applied Aerospace已成为这些颠覆者的关键合作伙伴,弥合了数字设计知识产权与大规模生产之间的鸿沟。
The wars in Ukraine and the Middle East have underscored how quickly drones, autonomous systems, precision strike, electronic warfare and resilient battlefield networks can reshape the combat zone. Venture-backed defense-technology entrants are speeding up the shift to software-defined, autonomous systems and faster production cycles, raising the value of manufacturing partners that can prototype, qualify and scale complex hardware quickly. Applied Aerospace has emerged as a key partner for these disruptors, bridging the gap between digital design intellectual property and mass production.
以其与私营国防技术巨头Anduril Industries(安德鲁尔工业)的深度融合为例。根据贝德(Baird)6月29日的研究报告,双方自2025年第二季度起就在Anduril的旗舰自主飞机——Fury协同作战飞机上展开合作。虽然Anduril掌握软件核心,但完全缺乏生产隐身机身所需的制造能力。Anduril依赖Applied Aerospace交付实体飞机,提供从发动机机身、主起落架组件到机翼和水平安定面的一切部件。
Consider its deep integration with private defense technology juggernaut Anduril Industries. The two have partnered on Anduril's flagship autonomous aircraft, the Fury collaborative combat aircraft, since the second quarter of 2025, according to a Baird research report dated June 29. While Anduril owns the software brains, it completely lacks the manufacturing capabilities required to produce stealth airframes. Anduril relies on Applied Aerospace to deliver the physical aircraft, supplying everything from the engine fuselage and main landing gear assemblies to the wings and horizontal stabilizers.
美国空军正将其协同作战飞机项目从原型阶段推向生产阶段,计划到2031财年采购超过150架飞机。这使Applied Aerospace站在了潜在大规模制造扩产的第一梯队。它也是SpaceX“猎鹰9号”平台的重要合作伙伴。
The U.S. Air Force is moving its collaborative combat aircraft program from prototypes to production, with plans to procure more than 150 aircraft by fiscal year 2031. This puts Applied Aerospace on the ground floor of a potentially massive manufacturing ramp-up. It's also a vital partner to SpaceX's Falcon 9 platform.
除了提供有效载荷部署结构——即帮助卫星、传感器、太阳能阵列或其他有效载荷在发射过程中存活并随后在太空中正确展开的硬件——应用航空航天公司还制造着陆装备组件。主要结构铰链可重复使用,但位于着陆腿连接关节处的铝蜂窝缓冲舱每次发射都必须更换。这些高度专业化的缓冲舱旨在吸收着陆冲击。随着SpaceX发射节奏加快,制造这些部件已成为应用航空航天公司的高销量收入来源。
Beyond supplying payload deployment structures — the hardware that helps a satellite, sensor, solar array or other payload survive launch and then deploy correctly in space — Applied Aerospace manufactures the landing gear components. The primary structural hinges are reused, but the aluminum honeycomb crush pods located at the connection joints of the landing legs must be replaced with each launch. The highly specialized crush pods are designed to absorb the touchdown impact. As the pace of SpaceX launches accelerate, manufacturing these parts becomes a high-volume revenue funnel for Applied Aerospace.
该公司未披露来自SpaceX的销售占比,同时也为蓝色起源“新格伦”火箭的可重复使用着陆装备提供支持。
The company hasn't disclosed the percentage of its sales from SpaceX, and it also supports the reusable landing gear for Blue Origin's New Glenn rocket.
在现金流拐点处,针对高增长先进制造企业的传统看空论点是资本支出消耗。人们担心公司将被迫稀释股东权益或背负昂贵债务以建厂履约。应用航空航天公司拥有40%的结构性过剩产能,赋予其竞争优势。仅通过从单班制运营扩展至标准多班制排产,应用航空航天公司即可提升产能,消化其快速增长的11.3亿美元合同订单积压,而无需进行实体厂房扩建。
At a cash flow inflection A traditional bear argument against high-growth advanced manufacturing plays is the capital spending burn. There is a fear that a company will be forced to dilute shareholders or choke itself with expensive debt to build factories to fulfill orders. Applied Aerospace has 40% structural excess capacity, giving it a competitive advantage. Simply by scaling from single-shift operations to standard multishift routing, Applied Aerospace can boost its throughput to clear its rapidly growing $1.13 billion contracted backlog without brick-and-mortar expansion.
其6月IPO带来的财务跑道具有变革性。IPO前,应用航空航天公司深陷6.43亿美元遗留债务泥沼,这是Greenbriar“买入并建设”战略的副作用。利息支出抵消了GAAP盈利,掩盖了其强劲的23.6%经调整EBITDA利润率。IPO后,应用航空航天公司的杠杆率降至经调整EBITDA的2.5倍。随着2026下半年和2027年利息支出下降,盈利有望加速增长。
The financial runway cleared by its June IPO is transformative. Pre-IPO, Applied Aerospace was heavily weighed down by legacy debt of $643 million, a byproduct of Greenbriar's buy-and-build strategy. The interest expense offset GAAP profitability, masking strong adjusted EBITDA margins of 23.6%. Post-IPO, Applied Aerospace's leverage is down to 2.5x adjusted EBITDA. As interest expenses decline in the second half of 2026 and 2027, earnings are likely to accelerate.
一项风险:未开票应收账款没有任何投资论点能忽视结构性风险审视,而对应用航空航天公司而言,一项风险就隐藏在其营运资本账目中。
A risk: Unbilled receivables No investment thesis is complete without a look at structural risk, and for Applied Aerospace one is buried within its working capital accounts.
投资者应密切关注该公司的未开票应收账款情况——这一指标近期从过去12个月销售额的28%升至34%。由于该公司主要承接多年期的航空航天系统项目,根据会计准则,企业必须在尚未达到合同约定的开票条件时便确认在制品收入。这种时间上的滞后性便导致了现金回款延迟。营运资金的持续积压正是近期公司经营性现金流暂时受限的主要原因。为证明其自由现金流转化能力依然强劲,这一指标在未来几个季度内需回落至行业平均水平(即20%左右)。
Investors should monitor the company's unbilled receivables, which recently spiked from 28% to 34% of trailing 12-month sales. Because the company builds multiyear aerospace systems, accounting regulations require them to recognize work-in-progress revenue, often before they reach the contract milestones that allow their billing. The timing differential translates into a lag in cash collection. The working capital buildup is the main reason near-term operating cash flow has been temporarily constrained. To prove the absolute health of its free cash flow conversion engine, this metric needs to return to the mid-20% peer average over the next few quarters.
目前Applied Aerospace的估值水平恐难以维持。截至周四收盘,该股股价为11.69美元,公司市值超过20.7亿美元;按市场共识预期,其2026年EBITDA预计达1.52亿美元,对应的企业估值倍数约为16倍。即便增长势头相对缓慢,像TransDigm与HEICO这类顶尖的航空航天子系统企业所获得的估值倍数也与此相当甚至更高。
A TransDigm in the making Applied Aerospace's current valuation is unlikely to persist. As of Thursday's close, at $11.69 per share, the company has a market cap of more than $2.07 billion and trades at an enterprise valuation of ~16x estimated consensus 2026 EBITDA of $152 million. Elite aerospace subsystems comparables such as TransDigm and HEICO trade at similar or higher multiples despite materially slower growth.
然而Applied Aerospace与这些同行之间的估值差距显得过大:该公司独家供应商模式下的营收占比约为87%,这一数值与TransDigm的90%相近,但Applied Aerospace的增长速度却更快。今年第二季度,该公司营收在计入并购贡献后增长了47%,内生性增长也达到19.8%;相比之下,TransDigm在第三财季的营收增幅仅为23%,内生性增长仅为13%。
The differential appears too steep: Applied Aerospace's sole-source revenue mix is about 87%, which is close to TransDigm's roughly 90% rate, yet Applied Aerospace is growing faster. Its second-quarter revenue rose 47% including acquisitions and 19.8% organically, compared with TransDigm's fiscal third-quarter growth of 23% as reported and 13% organically.
一旦公司能够公布符合公认会计准则的盈利数据,届时以15倍的估值倍数推算,其股价有望回升至上市发行价20美元,这一预期涨幅已属相当保守。据LSEG统计,绝大多数华尔街分析师均建议买入该股,平均目标价定为25.75美元,较当前股价高出一倍有余;而市场给出的最高目标价更是达到30美元,意味着股价较周四收盘价有望实现150%的涨幅。
A 12-month return to its IPO price of $20 per share is a highly conservative target, applying a standard re-rating multiple of 15x estimated 2027 EBITDA once clean GAAP earnings surface. Most Wall Street analysts recommend purchase with an average price target of $25.75, or more than double its current price, according to LSEG. The Street-high target $30 suggests a 150% return versus Thursday's close.
未来两个季度,随着Applied Aerospace剔除IPO相关费用、展现轻资本运营杠杆,并开始从积压订单中收回现金,其估值差距很可能会收窄。Applied Aerospace并不是一家经营陷入困境的公司,问题出在其IPO上,但它为长期回报提供了高质量的增长空间。本内容仅供参考,不构成财务、投资、税务或法律建议,也不构成购买任何证券或其他金融资产的推荐。
As Applied Aerospace strips out IPO charges over the next two quarters, demonstrates its capital-light operating leverage, and starts collecting cash on its backlog, the valuation gap will likely compress. Applied Aerospace isn't a broken business. It's a broken IPO, offering a high-quality runway for long-term returns. THIS CONTENT IS PROVIDED FOR INFORMATIONAL PURPOSES ONLY AND DOES NOT CONSTITUTE FINANCIAL, INVESTMENT, TAX OR LEGAL ADVICE OR A RECOMMENDATION TO BUY ANY SECURITY OR OTHER FINANCIAL ASSET.
本内容具有普遍性,并未反映任何个人的独特情况。上述内容可能并不适合您的具体情况。在作出任何财务决策前,您应认真考虑向自己的财务或投资顾问寻求建议。
THE CONTENT IS GENERAL IN NATURE AND DOES NOT REFLECT ANY INDIVIDUAL'S UNIQUE PERSONAL CIRCUMSTANCES. THE ABOVE CONTENT MIGHT NOT BE SUITABLE FOR YOUR PARTICULAR CIRCUMSTANCES. BEFORE MAKING ANY FINANCIAL DECISIONS, YOU SHOULD STRONGLY CONSIDER SEEKING ADVICE FROM YOUR OWN FINANCIAL OR INVESTMENT ADVISOR.