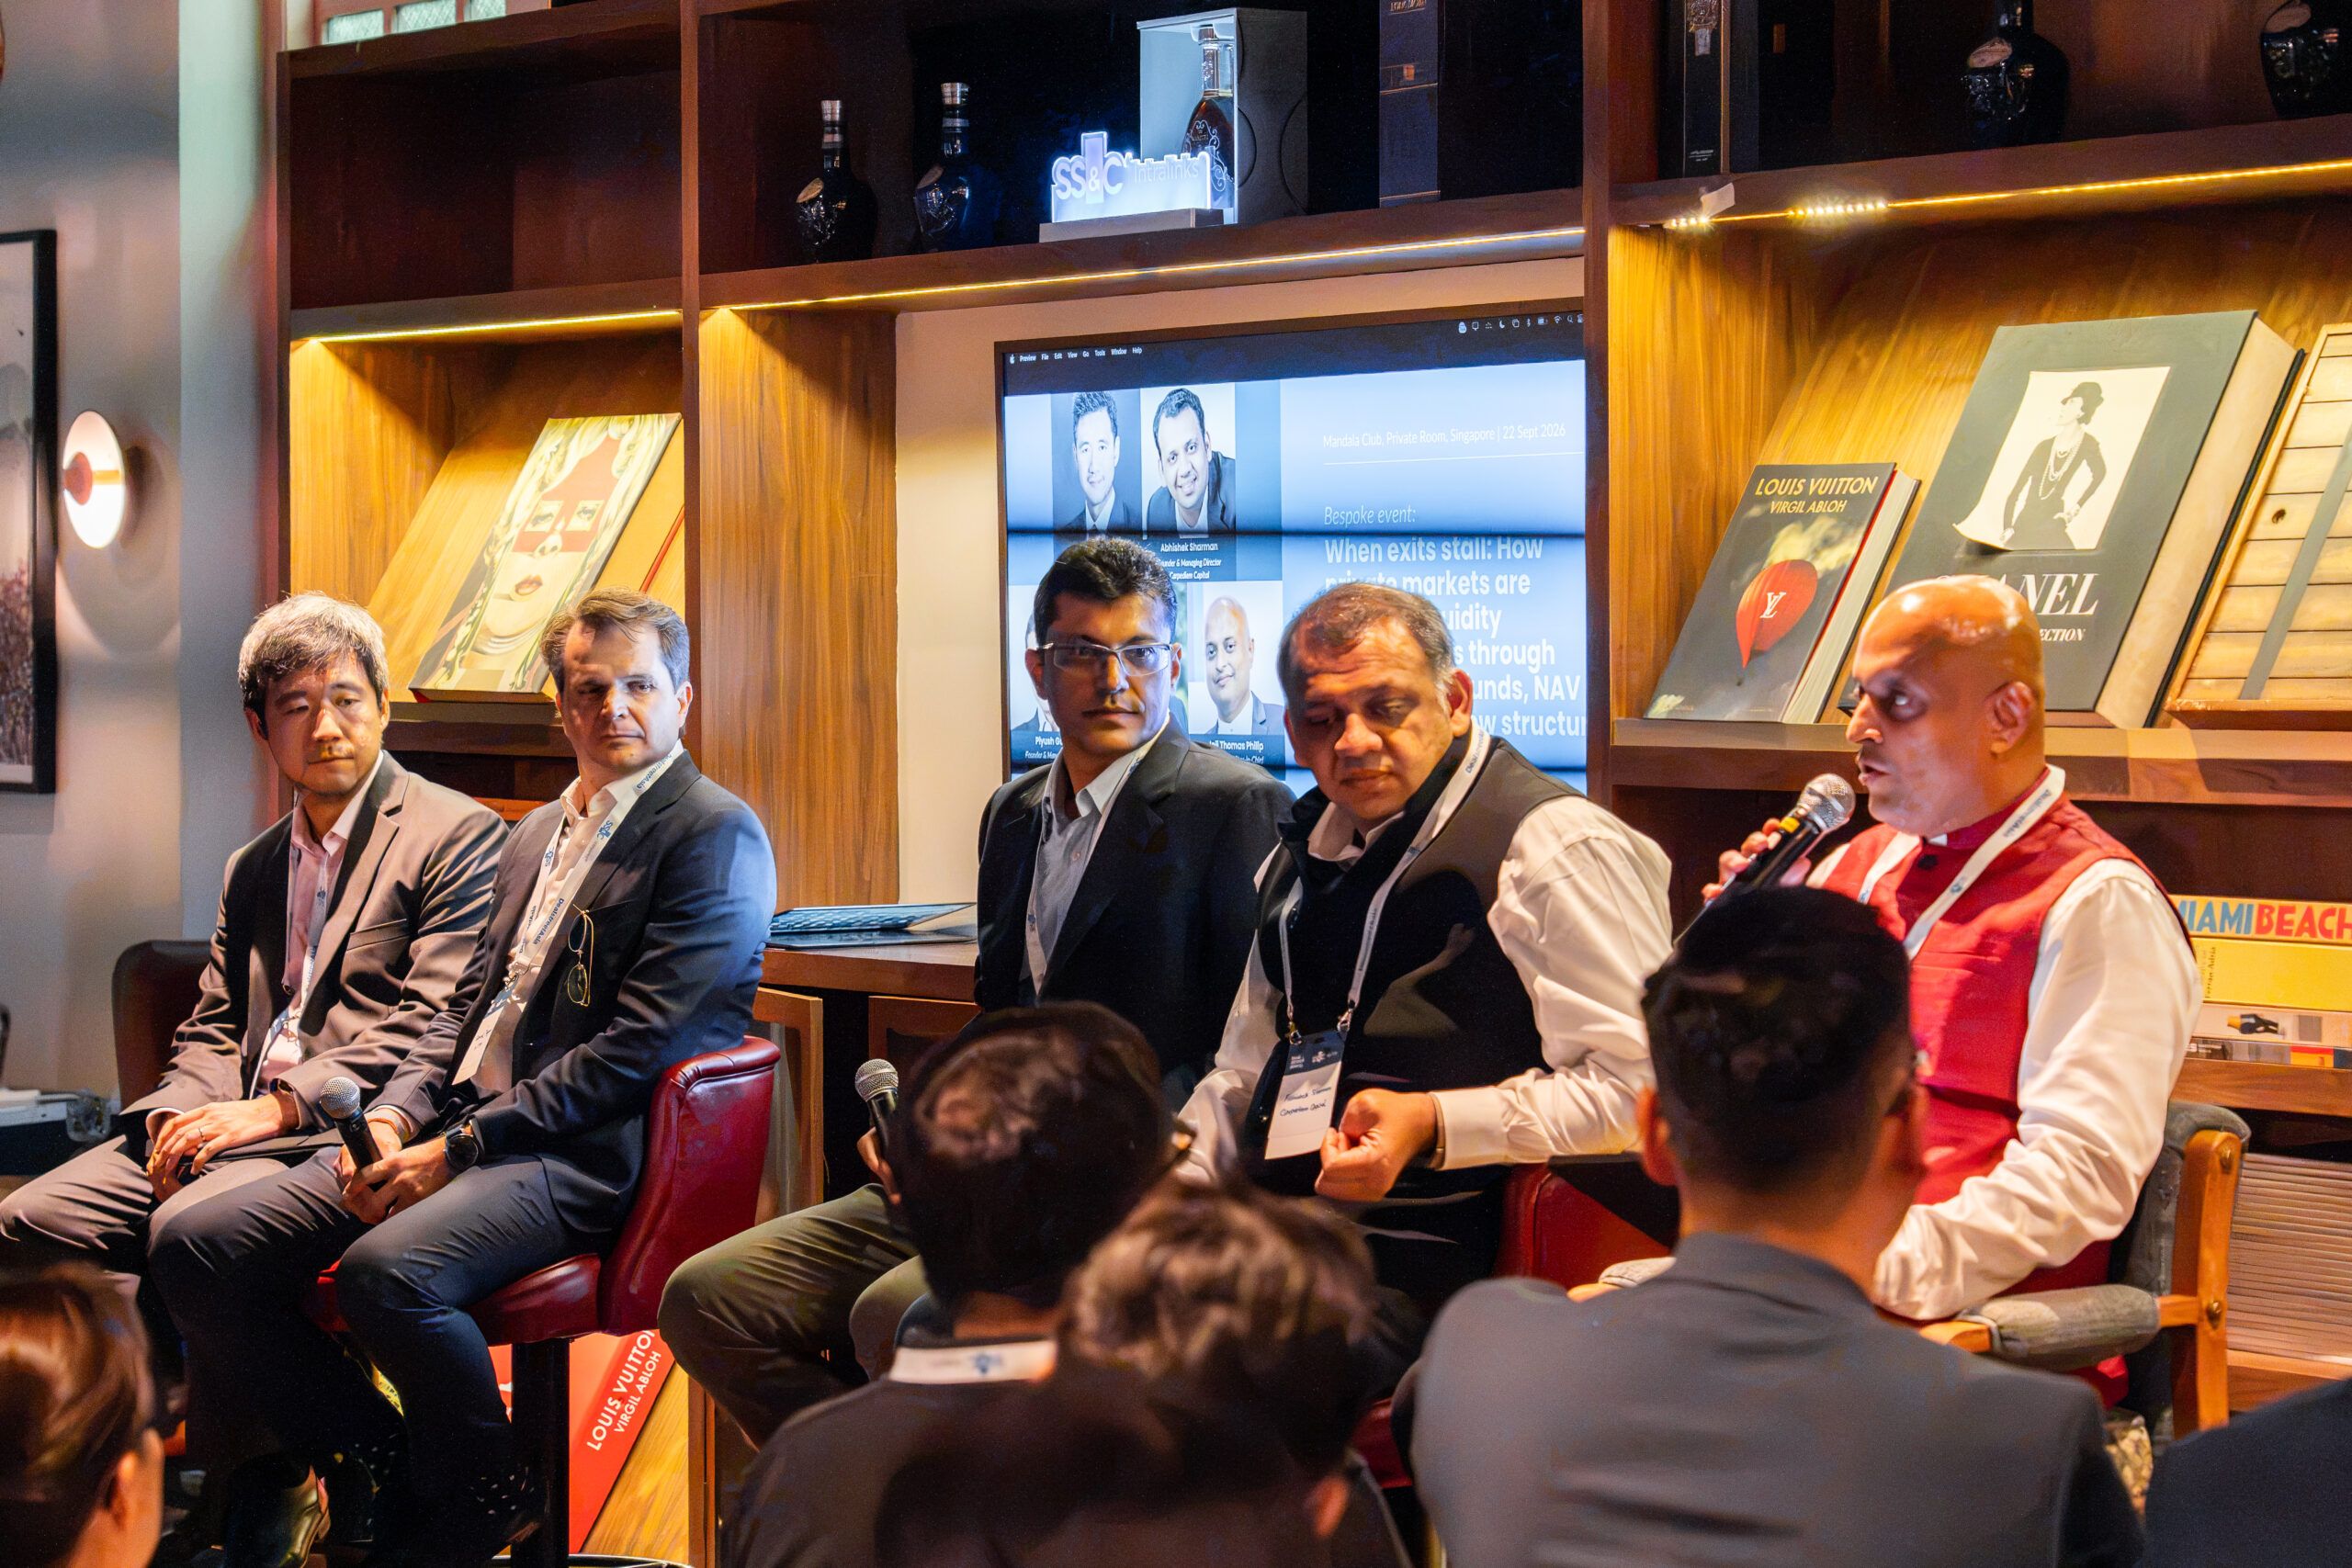
延续基金只是在延迟减值吗?行业专家认为,当结构设置得当时,替代流动性工具可以真正构建长期投资组合价值,尤其是在亚洲,这些工具还有一定的追赶之路。
Are continuation funds just delaying write-downs? Industry experts argue that when structured correctly, alternative liquidity tools could genuinely build long-term portfolio value, particularly in Asia, where these vehicles have some catching up to do.
亚洲私募市场正在面临流动性需求与长期持有资产的愿望之间的日益紧张的矛盾。包括延续车辆(CVs)、净资产值(NAV)融资和新型结构在内的替代流动性解决方案正被用来弥补这一差距。延续车辆:真正的价值创造与错位风险人们对延续基金持有普遍的怀疑态度,即它们只允许GPs推迟不可避免的减值。然而,Carpediem Capital创始人兼董事总经理Abhishek Sharman认为,当使用得当时,CVs是强大的战略工具。
Asian private markets are navigating a growing tension between the need for liquidity and the desire to hold onto assets longer. Alternative liquidity solutions, including continuation vehicles (CVs), Net Asset Value (NAV) financing and novel structures, are being used to bridge this gap Continuation vehicles: Genuine value creation versus misalignment risks A common scepticism surrounding continuation funds is that they merely allow GPs to delay inevitable write-downs. However, Abhishek Sharman, founder and MD of Carpediem Capital, argued that CVs are powerful strategic tools when deployed correctly. He said, “We typically only hold on if we can help companies build capacity for a further period from which we are invested. We of course try to play the horizon, but the other element is also very important.”
他表示:“我们通常只会在我们能够帮助公司在进一步投资期限内建立更多的生产能力时才会持有。我们当然会尝试抓住投资期限,但另一个因素也同样重要。”通过持有Carpediem Capital投资公司的26%以上的股权,Carpediem Capital可以帮助影响并在结构上协助它们。Sharman认为这对于受到像疫情这样的破坏性事件影响的陈旧年份的投资尤其有帮助。
By taking 26% plus stakes in the companies it invested in, Carpediem Capital could help influence and structurally help them. Sharman believed this was particularly helpful for an impaired vintage, after a disruptive event like the pandemic. However, Dominic Goh, MD, HarbourVest Partners introduced a vital caveat.
然而,HarbourVest Partners的董事总经理Dominic Goh提出了一个重要的前提。他指出,在亚洲,GPs通常持有少数股权,因此存在执行“剥离式出售”的诱惑:只将他们的一部分股权转入CV,而将旧基金保持投资状态。Goh敦促买方坚持要求进行干净、完整的转让,并确保GP的利益一致,以避免日后出现冲突。NAV融资如何弥补资金缺口NAV融资作为一种搭桥机制正获得越来越多的关注,但Illiquid Private Assets & Fund Financing(非流动性私募资产与基金融资)的联合创始人兼管理合伙人塞缪尔·普拉尼亚rd(Plagnard)强调,这并不是一张无限期推迟退出的免费通行证。
In Asia, where GPs often hold minority stakes, there is a temptation to execute “strip sales”: moving only a portion of their stake into a CV while keeping the old fund invested. Goh urged buyers to insist on clean, full transfers and to ensure GP alignment to avoid conflicts down the line. How NAV financing can make up for a shortfall NAV financing is gaining significant traction as a bridging mechanism, but Samuel Plagnard, co-founder and managing partner, Illiquid Private Assets & Fund Financing stressed that it is not a free pass to indefinitely delay exits. He said, “There is a path towards a defined value creation in portfolios by using the funding for bolt-on acquisitions, follow-ons, capex or sometimes a rationalisation of existing financing to lower the cost at the portfolio level. In that case, it’s not about DPI or generating distribution for the LPs.”
他表示:“通过使用这些资金进行 bolt-on收购、 follow-on投资、资本支出或有时对现有融资进行合理化以降低投资组合层面的成本,存在一条通往既定价值创造之路。在这种情况下,这不再是关于DPI或为LPs产生分配。”
Another use case was bridging during an absence of liquidity in the market: for instance, for pre-IPO financing.
另一种应用场景是在市场流动性缺乏时提供搭桥支持:例如,pre-IPO融资。普拉尼亚rd表示:“我们越来越多地看到,包括东南亚在内的多个市场上,continuation车辆与NAV融资相结合的现象。你有GPs以及帮助在CV基金中培育奖杯资产的战略投资者,但仍然存在资金缺口。这正是我们可以通过NAV贷款来帮助支持投资组合增长的地方。”
Plagnard said, “Increasingly we see a combination of continuation vehicles and NAV financing across markets including Southeast Asia. You have GPs, and anchor investors who help develop trophy assets in the CV fund, but there is still a shortfall. This is where we can bring an NAV loan on top to help support the growth of the portfolios.”Where AI can and cannot help The panel unanimously agreed that AI is having a transformational impact on operational heavy lifting, even as there were apprehensions about its tendency to hallucinate.
AI的能力与局限面板参与者一致认为,尽管人们对AI的“幻觉”倾向存在顾虑,但AI在操作性繁重工作中所起到的变革性影响不可忽视。尽管目前还不能成为投资等级的输入来源,但它最多扮演了一个高效能的分析员的角色。然而,AI的更广泰影响可以通过对某些资产的价值和表现提出的问题来衡量。AI不仅改变了投资者的工作方式,还改变了他们选择进行投资的方向。
While not yet a source of investment-grade inputs, at best, it played the role of a highly efficient analyst. However, the wider impact of AI could be gauged by questions around the value and performance of certain assets. AI was not just transforming how investors worked but where they chose to make investments. The one area where the panel was confident could not yet be disrupted by AI’s inability was understanding team dynamics, reading a founder’s energy and being able to tap into informal networks of information in the market.
面板参与者唯一确信AI尚无法取代的是理解团队动态、读取创始人的精力状态,以及能够进入市场中的非正式信息网络这一能力。“默认”深度折扣的结束历史上,二级市场一直被视为不良资产和僵尸基金的出售场所,因此买方需要付出较大的折扣。Goh表示:“这一情况已经在全球范围内发生了改变,包括亚洲。15年多前,我们投资的基金——当时最大的二级基金——规模为35亿美元。如今,我们每年部署的资金超过其3倍。要达到这样的规模,不可能全部都是不良资产。大多数二级交易涉及由蓝筹GP管理的高质量资产,这些GP寻求进行投资组合调整。因此,亚洲的优质资产现在交易时折扣非常有限,这是由未来的价值创造而非出售方的困境所推动的。
The end of “default” deep discounts Historically, the secondary market was viewed as a dumping ground for distressed assets and zombie funds, necessitating steep buyer discounts. Goh said, “That has changed across the world, including Asia. Over 15 years ago, the fund that we were investing in — the biggest secondary at that point — was $3.5 billion. Today, we annually deploy over three times that amount. To get to that size, it cannot be all distressed assets.”Most secondary trades involve high-quality assets managed by blue-chip GPs seeking portfolio reallocation.
然而,地理位置仍然影响定价能力。Kenro Capital创始人兼管理合伙人Piyush Gupta表示:“在东南亚,我们很难对我们最终的退出方式进行评估。作为一个基金,我们不以并购为目标进行评估。我们认为一家公司应该具备上市的条件,而由于东南亚的数据点要少得多,我们有时会感觉自己处于中间阶段,对退出点并不清楚。尽管东南亚是我们的 mandate 之一,但由于买方稀缺,我们并未参与其中。”
Consequently, quality assets in Asia now trade at very slim discounts, driven by future value creation rather than seller distress. However, geography still impacts pricing power.
以下是讨论的记录,经过编辑以求简洁和清晰:在什么时候创建延续基金真正实现了价值创造?又在什么时候它纯粹是最后的选择?
Piyush Gupta, founder and managing partner, Kenro Capital, said, “In Southeast Asia, it’s very hard for us to underwrite what our eventual exit is going to be. As a fund, we don’t underwrite to M&A. We believe a company ought to be IPO-able, and since Southeast Asia has far fewer data points, we are sometimes left feeling that we are at an intermediate stage and have no clarity on where the stop will be. We have not participated in Southeast Asia, even though it’s part of our mandate due to buyer scarcity.”The transcript of the discussion is below, edited for brevity and clarity:
Abhishek Sharman(AS):我们通常只有在能够帮助公司在更长的时间内建立能力时才会选择持有。我们当然会尝试把握时间,但另一方面也同样重要:我们在投资的公司中持有26%以上的股权。我们可以影响它们,因此相信我们能够从结构上帮助它们。具体来说,由于COVID影响表现不佳的 vintage 年份,为延续基金提供了一个更有趣的背景。
At what point is creating a continuation fund genuinely value creation? And when is it purely used as a last resort? Abhishek Sharman (AS): We typically only hold on if we can help companies build capacity for a further period from which we are invested. We of course try to play the horizon, but the other element is also very important: we take 26% plus stakes in the companies we invest in.
皮尤什·古普塔(PG):有限合伙人希望在新基金之前看到旧基金的分红率(DPI)。我们发现了市场上的空白点:不是很多普通合伙人专注于直接投资板块。延续性投资车更容易被有限合伙人接受。我们看到了这个空白:我们需要了解资产、行业和生态系统,然后我们就可以进行直接投资板块。
We can influence them and therefore believe we can structurally help them. Specifically, a vintage which wasn’t the best because of COVID makes for a more interesting backdrop for a continuation fund. Piyush Gupta (PG): LPs would like to see distributions to paid-in capital (DPI) in older funds before they come into new ones. We found the gap in the market: not enough GPs were focused on direct segments.
到目前为止,每笔投资都是股东的部分退出。他们喜欢这个资产并希望继续让它复利增长,但他们出售了15%到20%的持仓来实现净资产价值(NAV)并为有限合伙人提供一些分红率。这是一个很好的利益一致性体现。对于超过5000万至6000万美元的投资规模,印度有很多非常擅长拥有优质资产的成长基金。我们专注于低于5000万美元的细分市场,在这里我们发现几乎没有竞争。
The continuation vehicle is an easier investment for LPs. We saw the gap: we had to know the assets, the industry, and the ecosystem, and from there we could make direct segments. Every investment so far has been a partial exit for the shareholders. They like the asset and want to keep compounding it, but they’ve sold us 15% to 20% of their position to realise NAV and give some DPI to the LPs. That’s a great alignment of interests.
净资产价值融资是否解决了一个真正的时机问题,还是只是在延缓退出?
For ticket sizes over $50 million to $60 million, there are a lot of growth funds in India that are very comfortable owning great assets.
塞缪尔·普拉格纳德(SP):作为一家净资产价值融资机构,我们提供临时的流动性支持。最终,我们需要偿还贷款。我们给普通合伙人的时间来发展投资组合,必须用来做有成效的事情。提供的资金将用于并购、跟投、资本支出,或者有时对投资组合中所有资产的现有融资进行合理化。在这种情况下,这与分红率或为有限合伙人提供分红无关。
We are playing in the sub-$50 million segment and find very little competition there. Does NAV financing solve a real timing problem, or is it just postponing an exit? Samuel Plagnard (SP): As an NAV lender, we provide a temporary layer of liquidity. At some point, we need repayment. The time we give the GP to develop the portfolio must be used productively.
第二种情况是弥补市场上缺乏流动性的情况。这可能是一次IPO前融资。但我们越来越多地看到延续性投资车与净资产价值融资相结合的情况。你有普通合伙人和一些战略投资者一起帮助进一步发展延续性投资车中的优质资产,但在资金方面仍然存在短缺。这就是我们可以提供净资产价值贷款来帮助支持投资组合增长的地方。
The funding provided will be used for bolt-on acquisitions, follow-ons, capex or sometimes a rationalisation of existing financing across all the assets of the portfolio. In that case, it’s not about DPI or generating distribution for the LPs. The second case is bridging a situation where there is no liquidity in the market. That could, for instance, be pre-IPO financing. But increasingly we see a combination of continuation vehicles and NAV financing.
印度有一个热火的IPO市场。当你决定将某个资产放入延续性投资车而不是尝试上市或出售它的时候?
You have GPs and some anchor investors who come along to help develop those trophy assets in the CV fund further, but there is still a shortfall in terms of funding. This is where we can bring an NAV loan on top to help support the growth of portfolios.
AS: IPO市场在某些时候非常火热,在其他时候则不是那么热。一项资产今天可能无法进入IPO市场,但如果允许其再运行几年,就有可能进入。IPO市场的估值随着规模的扩大而提高。希望购买Pre-IPO或中间轮融资的潜在买家数量也会增加。
India has a hot IPO market. When do you decide an asset goes into a continuation vehicle rather than trying to list or sell it? AS: IPO markets are hot at certain points and not so hot at others. An asset may be unable to access the IPO market today, but could do so if allowed to run for a few more years.
通常情况下,当市场火热且资产已经达到规模时,人们才会选择IPO。但对于我们和其他专注于中市场的GP来说,并非所有公司都能轻易上市。在这种情况下,等待并让其成长以达到规模是非常明智的选择。
The valuation in the IPO market improves with scale. The number of potential buyers wanting to buy a pre-IPO or interim round also increases. One typically goes in for an IPO if the market is hot and if an asset is already at scale.
东南亚的每一个VC都急切地需要流动性。那么,谁拥有定价权呢?是买家还是卖家?
But for us and other GPs focusing on the mid-market, not all companies can readily go public. In that case, playing the horizon and waiting for it to scale makes a lot of sense. Every VC in Southeast Asia is desperate for liquidity.
PG:在东南亚,我们很难估计我们最终的退出方式,因为我们不进行并购承销。我们认为一家公司应该具备上市潜力,而由于东南亚的数据点较少,我们有时感觉自己处于中间阶段,无法清晰地判断何时会有转机。尽管东南亚是我们的 mandate 之一,但由于买家稀缺,我们还没有在东南亚参与过任何项目。从纸面上看,是什么使得一个投资组合变得可贷款呢?
So who has pricing power? Is it the buyer or seller? PG: In Southeast Asia, it’s very hard for us to estimate what our eventual exit is going to be since we do not underwrite to M&A. We believe a company ought to be IPO-able, and since Southeast Asia has far fewer data points, we sometimes feel that we are at an intermediate stage and have no clarity on where the stop will be.
SP:你可以争论说NAV只是一个会计数字。会计准则可能提供三到四种方法来为资产定价或估值。但归根结底,你所争论的就是标记到模型与标记到市场之间的区别。
We have not participated in Southeast Asia, even though it’s part of our mandate due to buyer scarcity. On paper, what makes a portfolio lendable? SP: You may argue that NAV is just an accounting number.
前者与价格发现有关。在金融资产的市场价值中,你可以看到其实际承担风险的价值。但你也可以看到流动性溢价成分,在私人资产领域,这是一个非常困难的练习,需要加以区分和识别。
Accounting standards give maybe three or four methodologies to put a price or a value to an asset. But ultimately, what you’re debating is between mark-to-model and mark-to-market. The former is related to price discovery.
从我们的角度来看,投资组合的可贷款性在很大程度上取决于转机。我们 structuring 净融资的方式总是围绕着两个问题展开:现金实现和控制权。
In the value of a financial asset on the market, you have a reflection of its actual value at risk. But you also have liquidity premium components, and in the private asset world, it’s a very difficult exercise to distinguish and identify.
我们正在为由全科医生管理的投资组合提供贷款。我们需要对他们在管理资产、实现现金和创造价值方面做好适当工作的能力感到满意。
From our perspective, the lendability against a portfolio depends very much on turnaround. Our way of structuring net financing is always around the two questions of cash realisation and control.
我们对全科医生进行了大量尽职调查:实现方面的跟踪记录和治理流程。这使得我们很难借钱给第一次贷款。
We are lending against a portfolio which is managed by the GP. We need to be comfortable with their ability to do a proper job in managing assets, realising cash down the road, and creating value.
然后,我们分析基础资产、整体投资组合、多元化、每项资产的估值可信度以及杠杆率。
We do quite a bit of due diligence on GPs: track records in terms of realisation, and governance process.
最后,我们通过提出借用基础来真正进入了这个设施的可结构性。在亚洲,与美国或欧洲相比,这是一项非常具体的练习。亚洲非常分散,存在一些严格的限制,例如合法获取资产、承诺的可执行性、现金跨境汇回、外汇错配……所有这些方面都使结构化过程比美国或欧洲复杂得多。但最终,这种内部分析将我们带到了借款基础,该基础在贷款期间随着时间的推移而动态控制。
This makes it quite difficult for us to lend to a first-timer. We then analyse the underlying assets, the portfolio as a whole, diversification, credibility of valuation on each of those assets, and look-through leverage. Finally, we are literally entering into the structurability of this facility by coming up with a borrowing base. In the context of Asia, it’s a very specific exercise compared to the US or Europe.
非常重要的是要确保当我们与GP和LP一起定义这种情况时,我们在贷款便利的有效期内跟踪这个目标或这个目标。
Asia is very fragmented with some hard constraints like legal access to assets, enforceability of your pledge, cross-border repatriation of cash, FX mismatch…all those aspects make the structuring process much more complex than the U.S. or Europe.
最终,尽管我们是贷方,但与银行不同,我们首先是承保全科医生的投资过程,当然还有资产。在某些情况下,我们可能与基础资产有非常强的联系,而在GP层面可能较少。这成为一种特殊的席位情况,或者更像是优先股,因为如果我们相信资产有上涨空间,我们就会以优先股的形式结构贷款,但至少我们看到随着时间的推移,风险敞口会上升。
But ultimately this internal analysis brings us to the borrowing base which is controlled dynamically over time during lending. It is very important to make sure that when we define this scenario together with the GP and the LP on why they need liquidity, we keep track of this target or this objective during the lifetime of the loan facility. Ultimately, even though we are lenders, unlike banks, we are underwriting the investment process first of a GP, and then of course the asset.
当谈到二级资产时,良好的资产通常会吸引出价。但在世界的这个地区是否有出价,或者所有资产都可以打折出售?
In some instances, we may have a very strong connection to the underlying asset, less maybe at the GP level. This becomes a kind of special seat situation, or more like preferred equity because if we believe there is upside on the asset, we will structure the lending in the format of preferred equity, but at least we see an upside exposure over time.
Dominic Goh(DG):全球二级市场在二三十年前开始时非常小众。我们从僵尸基金那里购买了资产,无法出售的资产,已经崩溃的团队:冒险的东西。你显然需要折扣。
When it comes to secondaries, typically good assets attract bids. But in this part of the world are there any bids, or are all assets available at discounts? Dominic Goh (DG): The global secondary market was very niche when it began 20 or 30 years ago.
但这种情况在世界各地发生了变化,包括亚洲。当我15年前加入时,最大的二级基金是35亿美元。如今,我们每年部署的数量超过这个数字的三倍。全球一年的交易额约为2400亿美元。要达到这个规模,不可能都是不良资产。
We bought assets from zombie funds, assets that couldn’t be sold, teams that had fallen apart: dicey stuff. You obviously needed a discount. But that has changed across the world, including Asia. When I joined over 15 years ago, the biggest secondary fund was $3.5 billion. Today, we annually deploy over thrice that amount.
痛苦的部分存在,但已经变得小得多。大多数是由蓝筹股全科医生管理的优质资产,这些名字我们都很熟悉。我们通常会列出一份我们认为有趣的列表。由于亚洲的规模比美国和欧洲小得多,因此从逐个基金的角度来看,战利品资产较少。回报分散度要大得多:你得到了好的资产,但也有一些不太好的资产。另一面是资本可用性。对于亚洲第二,这是明显低于你在其他地方。买家和卖家之间的信息差距在哪里?
One year’s volume of deals globally is about $240 billion. To get to that size, it cannot be all distressed assets. The distressed part exists but has become much smaller. The majority are quality assets managed by blue-chip GPs, names that we are all familiar with. We routinely pull down a list of the ones we find interesting. Since Asia is a lot smaller than the U.S. and Europe, on a fund-by-fund basis, there are fewer trophy assets. Return dispersion is a lot wider: you get good assets, but also a tail of not-so-good assets. The flip side is capital availability.
PG:在私人市场中,信息访问始终是您的首要挑战。无论团队或投资者有多聪明,如果您无法访问MIS数据,您就无法开始。在分散的风险投资基金市场中,必须了解行业、创始人和团队的素质以及业务的质量。我们看到很多风险投资者的谈判风格不同。有些人试图建立长期关系,因此他们希望以公平的价格出售,因为他们想回来。
For Asian secondaries, it is commensurately less than what you have elsewhere. Where is there an information gap between buyer and seller? PG: In private markets, information access is always your first challenge. No matter how smart a team or an investing person is, if you don’t have access to the MIS data, you can’t get started. In the fragmented venture backed funds market, one must know the industry, the quality of founder and team, and the quality of business.
但有一些人会试图让它成为一个双赢的局面。我们只需要意识到这些个性或谈判类型,这不是在公司层面上;而是在个人层面上。
We have seen many VCs have different negotiation styles. Some try to create a long-term relationship, so they will want to sell at a fair price since they’d like to return.
许多直接二级基金难以起步,因为它们必须深耕本地。情报、关系网络皆为本地化且实时更新。一家公司上一季度的表现可能发生剧变。私募市场的信息差异非常显著,尤其是在直接二级市场,因为你无法依赖GP(普通合伙人)来评估、定价资产并给卖方一个关键价格。关于利益一致性破裂,最大的危险信号是什么?
But there are several folks who will try to make it a win-lose situation. We just have to be aware of these personality or negotiation types, and it is not at a firm level; it’s at individual level. Many direct secondary funds have not been able to get started because they must be on the ground. The intelligence, relationships networks are all local and real time. How a company did in the last quarter may change quite dramatically.
DG:在亚洲,我们经常看到一种情况,即在延续基金(CV)交易中,GP喜欢出售资产的部分份额,即我们所谓的“拆分出售”。例如,GP持有某公司20%的股份,他会说:“哦,我将投入10%或15%到CV中,而不是全部20%。”我们担心这种动态。CV本身交易已完成,结构已足够复杂,还要考虑利益一致性问题。而这里你让旧基金继续持有投资,实际上制造了另一个潜在冲突来源。
The information gap in private markets is very significant, especially in direct secondaries because you don’t have the GP to rely on, evaluate, and price an asset and give a key price to a seller. What are the biggest red flags about an alignment having broken down? DG: In Asia, something we see quite often is in CV transactions, GPs love selling parts of the asset or “strip sales” as we call them. For instance, if a GP owns 20% in a company, he says, “Oh, I will put up 10% or 15% and not the full 20% into a CV. We worry about that dynamic. CVs have already a completed transaction that is complex enough to then think about the alignment. And here you are keeping the old fund still invested, effectively creating another source of potential conflict. You’ve got an existing vehicle that may have come in five years ago, maybe sitting on 5x, and now you’ve got a new vehicle? Where does the alignment go? It’s hard enough with one CV. But now you’ve got CVs, the existing fund, and goodness knows how many other funds and co-investments!
你有一个可能五年前入场、现坐拥5倍回报的现有基金,现在又来了一个新基金?利益一致性何在?光一个CV就够难搞了。但现在你有了CV、现有基金,还有天知道多少其他基金和联合投资!
You don’t really see this dynamic in the developed markets in the US and Europe partly because the stakes tend to be controlled. GPs think of retaining control and not selling down partial stakes. That is obviously not the case in Asia, where a lot of it is minority investing. You don’t have many control situations.
在欧美发达市场,你不太会看到这种动态,部分原因是股权往往是控股性的。GP考虑的是保留控制权,而非出售部分股份。但在亚洲显然并非如此,这里多为少数股权投资,控股交易不多。但当GP找我们做这些交易时,我们首先会问:“你能否将所有资产转入CV,使交易结构尽可能清晰,以最大程度减少未来的冲突和利益错位?”为什么CV在亚洲花了这么久才兴起?
But when GPs come to us for these transactions, we start off by saying, “Can you transfer everything into a CV and make it as clean a trade as you can, to minimise conflicts and misalignment down the road?”Why did it take so long for CVs to take off in Asia? AS: Private equity has come of age in India, but it began some 25 years ago. The AIF regulations, which is the guiding thesis for vehicle setup in India came into being in 2012. SEBI, our regulator, has a very nuanced view of a fund’s life.
私募股权在印度已趋成熟,但其起步可追溯至约25年前。作为印度基金架构设立指导原则的AIF(另类投资基金)法规于2012年出台。印度证券交易委员会(SEBI)作为监管机构,对基金存续期持有极为细致的看法。与大多数司法管辖区由LP(有限合伙人)决定是否继续跟投GP(普通合伙人)的特定基金不同,在印度,SEBI仍需确信这样做确实妥当。SEBI法规在GP行为规范方面起到了强制约束作用。
Unlike most jurisdictions, where the LPs decide to continue with the GP on a particular vehicle, in India, SEBI still needs to be convinced that is indeed the right thing to do. SEBI regulations have forced the hand as far as GP behaviour is concerned. Every 10-year vintage has its own set of challenges, but this vintage was remarkable for the amount of disruption. We had demonetisation, where the fiat currency was rendered value-less. Then you had GST, which was a good thing from a long-term perspective, but it was a huge external shock to the system.
每个10年周期的基金都有其自身的挑战,但本周期因干扰因素之多而显得非同寻常。我们经历了废钞令,法定货币瞬间贬值;随后是商品及服务税(GST)的实施,从长远看利好,但当时给系统带来了巨大的外部冲击;紧接着又遭遇新冠疫情。
And then COVID. It was a difficult vintage, with more disruptions than usual.
这是一个充满挑战的周期,干扰因素超出常态。这迫使企业和GP为投资组合公司筹集更多资金,并承担额外的股权稀释。若要重回正向发展区间,他们必须坚持更长时间。
It required companies and GPs to raise more capital for their portfolio companies and take on additional dilution. If they have to come back to a zone of positivity, they must be there for longer. There is also that optimism that after every period of disruption there will be a great movement, and therefore many people also agree that the next 2 to 5 years will also be a particularly good phase.
同时也存在一种乐观情绪:每一段动荡期过后都将迎来巨大的变革机遇,因此许多人也认同未来2至5年将是一个特别好的阶段。
A combination of those factors is why we are seeing more continuation vehicles.
这些因素共同作用,导致我们看到更多延续基金的出现。但随着市场发展,成熟市场的解决方案也将浮现。例如,就印度GP而言,NAV融资(净资产值融资)尚处于起步阶段,但我确信,若五年后我们再次交谈,你可能会看到其获得更大的发展。
But as we develop, the solutions that you see in developed markets will also come to the fore. For example, NAV financing is at its infancy, if I may say so far as far as Indian GPs are concerned. But I’m sure that if we have this conversation five years down the line, you might see much more traction.
亚洲投资组合较低的杠杆率,在NAV融资方面是优势还是被过分夸大了?
Is the lower leverage in Asian portfolios an advantage when it comes to NAV financing or is it overstated?
平均而言,看亚洲企业,尤其是中型企业,其杠杆率可能比美国和欧洲同类公司低两到三倍。从宏观角度看,这是一个优质市场但杠杆不足:非常适合我部署私募信贷。
SP: On average, when you look at corporations in Asia, especially the mid-sized corporates, they are probably two or three times less leveraged compared to similar companies in the US and Europe. From a macro perspective, you’d say great market but not much leverage: great for me to deploy private credit.
按理说,这种宏观情境下的赢家应该是直接放贷人。但由于亚洲市场高度碎片化,在亚洲部署直接放贷资本的边际成本,比美国和欧洲高得多。这就是为什么我们在亚洲很少看到直接放贷业务发展的原因。
You would think the winner in this macro scenario would be the direct lender. But since Asia is very fragmented, the marginal cost of deploying capital into direct lending is significantly higher compared to the US and Europe. That is why we see very little development in the direct lending business in Asia.
谈到净资产值(NAV)融资,你不是基于单一资产放贷,而是针对投资组合。因此,从定义上讲,单笔交易的借贷基数大得多。这项业务具有明显的可扩展性。从募资角度看,我处于相对舒适的位置,可用资本远超需求。
When you think about NAV financing, you are not lending on an asset-by-asset basis, but against a portfolio. So, by definition on one transaction, the borrowing base is much bigger. There is clear scalability in that business. I’m in a relatively comfortable place from a capital-raising perspective.
我现在的位置,是在为亚洲进行教育,让市场了解NAV融资如何提供流动性解决方案。依我之见,这将成为结构性趋势。您如何看待东南亚?
I have much more capital than demand. Where I’m sitting now is in an education process for Asia to get a sense of how NAV financing could bring liquidity solutions. In my view, it will become structural.
SP:东南亚是流动性问题最突出的地区。从我的角度看,这是我应投入最多时间推动NAV融资的地方,因为那里有大量优质资产。看看那些需要获得流动性并易手的未实现净资产值规模。之所以如此,是因为买卖双方不一定能在价格上跨越价差,或延续基金需要时间。如果有合理的故事和好的叙事,我非常乐意填补这些空档。
How do you view Southeast Asia? SP: Southeast Asia is where liquidity is the biggest issue. From my perspective, this is where I should spend most of my time pushing for NAV financing because there are plenty of good assets. Consider the amount of unrealised NAV that needs to get liquidity and change hands. It’s because both sides are not necessarily crossing the spread in terms of price, or continuation funds take some time.
就进展而言,这更多是因为对基金融资和NAV融资认知度低,而非不喜欢。我们在资本认缴信贷额度(另一种基金融资形式)上也观察到过类似现象。
I’m quite happy to bridge those situations if there is a sound story and good narrative. In terms of traction, this is more a function of low awareness of what is fund finance and NAV financing rather than people not liking it.
15年前,亚洲可能有4%或5%的基金在使用资金,现在已经超过90%。我们只有5%的资金使用资产净值融资。但最终,它将改变并转变为基金内部投资组合构建的一个非常结构性的组成部分。
We have observed a similar phenomenon for instance, on capital sub lines which is another form of fund finance. There were probably 4% or 5% of funds in Asia that were using capital 15 years ago, and now it’s over 90%. We have barely 5% of funds using NAV financing.
从全球公司的角度来看,您在亚洲看到的中学教育手册中是否有什么很大不同?
But eventually, it will change and transform into a very structural component of portfolio construction within funds.
DG:技术几乎是一样的:无论是简历、LP转让等。如果你想想世界这一地区的二级资产买家,你会发现很多资本都是通过全球工具获得的。无论是我们还是同行,他们都是全球投资者。在这些全球资金池中,大部分资本都部署在亚洲以外的美国和欧洲。
From the perspective of a global firm, is there anything very different in the playbook that you have seen in Asia when it comes to secondaries? DG: The technology is pretty much the same: whether it’s CVs, LP transfers, etc. If you think about the buyers of secondary assets in this part of the world, a lot of the capital is through global vehicles. Whether it is us or our peers, they are global investors. In those global pools, the majority of capital is deployed outside of Asia into the US and Europe.
相反,亚洲资产的许多卖家都是亚洲以外的有限合伙人。不同的是执行。印度看起来将与中国大不相同,而中国又将与日本或韩国大不相同。
Conversely, many of the sellers of Asian assets are LPs who are also outside Asia. What will be different is implementation. India will look very different from China, which in turn will look very different from Japan or Korea.
你真正需要的是地面上的靴子,无论是我们,全球参与者,印度二级市场参与者的崛起,中国二级基金的崛起,甚至日本:其中很多都是有原因的。这是因为市场变得越来越大,对更专业的承保和执行能力的需求正在推动市场向前发展。与东南亚或印度相比,在发达亚洲进行二级交易是否更容易?
What you really need is boots on the ground, and whether it’s us, the global players, the rise of Indian secondary players, Chinese secondary funds coming up, or even Japan as well: a lot of these are coming up for a reason. It’s because the market is becoming a lot bigger, and the need for more specialised underwriting and execution capabilities is pushing the market forward. Is it easier to do a secondary transaction in developed Asia compared to Southeast Asia or India?
DG:二级活动的最大驱动力是退出市场。作为资产的买家,只有在我们知道最终可以把钱拿出来的情况下,我们才会投入资金。如果退出市场不发挥作用或不如另一个市场发挥作用,那么我们显然要三思而后行。如果考虑当今流动性最强或流动性更强的亚洲资本市场,印度几乎处于领先地位。相反,在东南亚,退出可能更具挑战性。人工智能如何影响您的业务?
DG: The biggest driver of secondary activity is the exit market. As buyers of assets, we put money up only if we know we can get it out at the end. If the exit market isn’t functioning or isn’t as functional as another market, then we clearly think twice. If you consider the most liquid or more liquid Asia capital markets today, India is pretty much at the top. Conversely, in Southeast Asia, exits can be more challenging. How has AI affected your business?
AS:我们投资组合中的某些公司被认为更有可能受到AI的冲击。突然之间,某些服务业务的估值倍数在现金流不变的情况下下降了,因为大家心照不宣地在问:AI将如何影响这些资产?
AS: There are certain companies in our portfolio which are perceived as more likely to be disrupted by AI. Suddenly, the multiples in certain service businesses have gone down on the same cash flow because of the unsaid question: what is AI going to do to these assets?
在评估交易和流程方面,我们使用AI的频率更高了,这确实提高了效率。但我们发现它产生幻觉的情况相当多。数据收集等常规工作变得更容易了,耗时比以前可能减少了20%到30%。但目前还没达到让我们放心直接使用AI生成的投资级成果的阶段。
When it comes to evaluating deals and processes, we are using more AI, and it’s certainly increasing efficacy. But we find that it hallucinates quite a bit. Routine work such as data gathering has become easier and takes maybe 20% to 30% less time than earlier. But it’s not at a stage where we are comfortable with investment-grade outputs coming out of AI.
PG:从投资角度来看,AI使我们的选择在教育服务、金融基础设施、实地运营的非银行金融机构(NBFC)或消费品牌等板块变得非常防御性,因为这些领域很难被AI颠覆。我们正在远离软件赛道,因为我们很难为其合理定价。
PG: From an investment perspective, AI has made our selection very defensive in sectors like education services, financial infrastructure, feet-on-the-ground NBFC, or consumer brands because this is hard for AI to disrupt. We are staying away from software because it’s very hard for us to price that properly.
在工作层面,这确实是一个真正的进步过程。最初感觉就像拥有一位非常聪明的助理,负责行业研究和一些基础分析。我们觉得它的表现不亚于我们任何一位合伙人(GP)。
At a working level, it’s been a real progression. It first felt like having a very smart associate who does industrial research and some basic analysis. We feel it is as good as any of the GPs.
我们正在与首席技术官合作开发一个组织级的AI大脑,它建立在我们所有的邮件、会议记录和模型之上。它能给我们提供实时反馈,告诉我们哪里可以做得更好:我们遗漏了哪些分析。
We are working with our CTO to develop an organisational AI brain, which sits on top of all our emails, meeting notes, and models. It can give us real-time feedback around what we could be doing better: the analysis we are missing.
显然,当我们会见创始人时存在投资判断。我们评估他们、他们的精气神以及领导团队之间的关系。这些是我们无法交给AI的方面,但在大量静态分析工作上,AI的表现极其出色。
There is obviously an investment judgment when we meet founders. We evaluate them, the energy, and the relationship between the leadership team. These are aspects that we cannot leave to AI, but there’s a lot of static analysis where it is phenomenal.