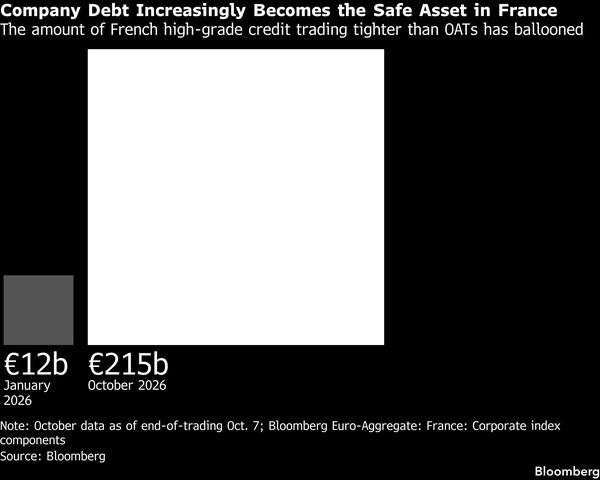
由塔索斯·沃索斯和罗南·马丁撰写法国约有2150亿欧元(2410亿美元)的公司债券目前交易时收益率低于政府债券,较2026年初增长了近18倍,这是一次残酷的主权债券抛售之后的结果。
Nearly €215 billion ($241 billion) of France’s corporate bonds now trade as if they were safer than the government’s, an almost 18-fold increase since the start of 2026, after a punishing sovereign debt selloff.
根据彭博社编译的数据,周三法国约38%的优质公司债务收益率低于同期政府证券。而在年初时,这一数字仅为120亿欧元。
Some 38% of France’s total pool of high-grade company debt was indicated at lower yields than government securities of similar maturity on Wednesday, according to data compiled by Bloomberg. That compares with just €12 billion at the start of the year.
传统市场层级中的这种颠倒现象并非全新,但在法国却迅速升温,原因包括财赤目标未达、新预算陷入僵局,以及即将到来的总统选举可能把国家引向截然不同的方向。
The topsy-turvy dynamic in traditional market hierarchies is not entirely new, but has escalated rapidly in France amid concerns about missed deficit targets, gridlock over a new budget, and a looming presidential election which could set the country in a radically different direction.
随着政府债务信心下降,公司债券——尤其是那些具有国际业务的公司,如法国欧诺化妆品(L'Oréal)和石油天然气巨头道拉能源(TotalEnergies SE)——现在已成为最安全的避险资产。
As confidence in government debt erodes, corporate bonds — especially for internationally-exposed firms like L’Oreal SA and oil and gas giant TotalEnergies SE — are now one of the safest havens.
“法国的主权信事和公司信用信事变得越来越脱节,”通用投资公司的高级信用策略师埃丽莎·贝尔加谢姆(Elisa Belgacem)表示。公司和银行“仍然享有强劲的投资者需求,凸显了对发行人的基本面和整体收益率的吸引力。”巴黎的空气液体(Air Liquide SA)就是最新例证。该工业气体制造商周二在一笔20亿欧元的债券发行中吸引到了约125亿欧元的投资者订单,其中两笔固定利率票据的收益率低于法国政府债券。
“France’s sovereign story and its corporate credit story have become increasingly disconnected,” said Elisa Belgacem, senior credit strategist at Generali Investments. Companies and banks “continue to enjoy strong investor demand, highlighting confidence in issuer fundamentals and the attractiveness of all-in yields.”Paris-based Air Liquide SA is the latest case in point. The industrial-gas maker drew around €12.5 billion of investor orders for a €2 billion debt offering on Tuesday, with the two fixed-rate tranches offering lower yields than French government bonds.
对欧洲投资级公司债券负责人的埃德华·法尔利(Edward Farley)来说,关键因素是公司的收入来源地。以法国欧诺化妆品和LVMH(路易·威登·蒙克·汉塞尔斯酒文集团)为例,“除了他们在法国注册之外,这几乎就是最重要的因素了,”他说道。
For Edward Farley, head of European investment grade corporate bonds at PGIM Ltd., the key factor is where companies generate their revenues. For L’Oreal and LVMH Moët Hennessy Louis Vuitton SE, for example, “other than the fact that they’re domiciled in France, that’s about as material as it gets,” he said.
法利更为谨慎地看待法国银行,因为法国银行与政府债券市场联系更为紧密。无论是通过持有主权债务还是贷款暴露在经济政策的间接影响之下,银行都有直接利益关系,而法国银行债券的违约保险成本已持续超过其他欧洲银行。
Farley is more cautious about French banks, however, which are more closely linked to the government bond market. Banks have skin in the game either through holdings of sovereign debt or by their loans being exposed to the indirect effect of economic policies, and the cost of insuring French bank bonds against default has been surging above that of other European lenders.
虽然法国是典型的企业债与政府债出现反转的情况,但这种趋势在发达经济体中已经酝酿了一段时间。
While France is an extreme case of a corporate-government bond inversion, the dynamic has been brewing in developed economies for some time.
传统上,政府债券一直是债券市场上安全性的基准,因为政府在资金短缺时有能力提高税收。但随着各国赤字持续扩大,以及各派政治人物都难以遏制这一趋势,财务状况良好且财政纪律严格的公司看起来更值得投资。
Traditionally, sovereign debt was the benchmark for safety in the bond market as governments have the ability to raise taxes when they run short of funds. But as national deficits continue to grow, and politicians of all stripes struggle to reign them in, companies with strong balance sheets and fiscal discipline look like a better bet.
去年,微软公司在美国减税对财政预算影响的担忧之下,曾一度交易价格低于国债。更早之前,在欧元区主权债务危机期间,一些西班牙和意大利公司的债券也曾便宜于其政府的债券。这也是新兴市场投资者需要更频繁面对的情况。
Last year, Microsoft Corp. briefly traded cheaper than Treasuries amid concerns about the impact of US tax cuts on the budget. Further back, during the euro zone sovereign debt crisis, some Spanish and Italian corporate bonds were cheaper then those of their governments. It’s also a situation that emerging market investors have to deal with more frequently.
自2024年中以来,法国总统马克龙在其党在欧洲议会选举中遭受惨败后,急于解散选举,法国债券市场一直存在政治不确定性这一突出特点。到那一年年底,有少数公司的收益率已开始低于法国政府债券(即法国国债)。
In France, political uncertainty has been a persistent feature of the bond market since mid-2024, when President Emmanuel Macron called a snap election after his party suffered a heavy defeat in European parliamentary elections. By the end of that year, a small number of companies had started trading at lower yields than French government bonds, or OATs.
但这种现象现已变得更加普遍,企业债的数量可能会继续增加。法国选举仍有超过六个月的时间,而债券抛售潮已开始溢入其他市场。
But the phenomenon has now become much more pervasive, and the tally of corporate bonds may keep growing. France’s election is still more than six months away, while the bond selloff is already spilling over into other markets.
据巴克莱公司信用策略分析师梅丽莎·麦克洛伦(Melissa McCallum)称,国内政府债券收益率曲线作为信用市场支撑的典型情景“在主权压力时期可能会崩盘”。
A typical scenario where the domestic government bond curve acts as a floor for the credit market “can break down during periods of sovereign stress,” according to Barclays Plc credit strategist Melissa McCallum.
她说:“但值得注意的是,情况不仅仅是高质量信用的收益率曲线下滑,许多BBB级债券的交易价差也收窄了。”
“What stands out, though, is that it is not just high quality credit that has broken below the OAT curve, as many BBBs also trade tighter,” she said.