在1.8万亿美元规模的私募信贷市场经历动荡时期之际,越来越多希望甩卖表现不佳基金的私募信贷管理人,正吸引那些寻求廉价交易机会的竞争对手关注。
Private credit managers increasingly looking to offload battered funds are drawing interest from rivals eyeing cheap deals in one of the most turbulent periods for the $1.8 trillion market.
据熟悉此事的人士透露,近几个月来,包括Ares Management Corp.、Barings LLC、BC Partners和Churchill Asset Management在内的多家机构,已对问题基金进行了初步评估。这些人士补充说,相关讨论仍处于早期阶段,未必会促成任何交易,并要求匿名,因为相关谈判属于机密性质。
By Olivia Fishlow Firms including Ares Management Corp., Barings LLC, BC Partners and Churchill Asset Management have run the rule over troubled funds in recent months, according to people familiar with the matter. The talks are still preliminary and may not result in any transactions, the people added, asking not to be identified as the discussions are private.
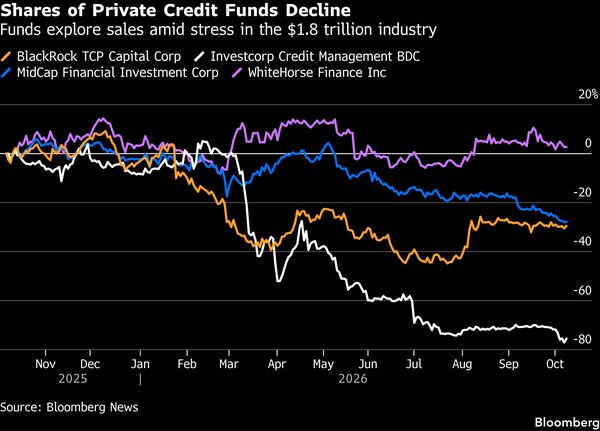
KBW分析师Paul Johnson表示:“我很难想到还有哪个时期会出现如此多的公开交易型BDC(商业发展公司)待售。促使他们彻底出售的原因,是长期以来的业绩不佳。”今年,私募信贷管理人面临巨大压力,投资者从非上市基金中撤出创纪录的资金,并抛售上市实体的股份。包括BlackRock Inc.旗下陷入困境的TCP Capital Corp.、WhiteHorse Finance Inc.以及Investcorp Credit Management BDC Inc.在内的公开交易基金,均已表示正在考虑战略选择,其中可能包括出售。
“I can’t think of another time like this where you’ve seen so many public BDCs up for sale,” said Paul Johnson, an analyst at KBW. “The motivation for an outright sale comes from a long period of underperformance.”Private credit managers have faced intense pressure this year, as investors pulled record amounts from nontraded funds and sold off shares of listed vehicles. Publicly traded funds including BlackRock Inc.’s beleaguered TCP Capital Corp., WhiteHorse Finance Inc. and Investcorp Credit Management BDC Inc. have said they’re weighing strategic options, which could include a sale.
据知情人士称,Apollo Global Management Inc.旗下的MidCap Financial Investment Corp.也已在四处寻找买家。
Apollo Global Management Inc.’s MidCap Financial Investment Corp. has also shopped its portfolio around, the people with knowledge said.
Ares、Barings、BC Partners和Churchill的代表均拒绝置评,Apollo的发言人亦未回应。
Representatives for Ares, Barings, BC Partners and Churchill declined to comment, as did a spokesperson for Apollo.
通常情况下,私募信贷管理人极不愿意出售公开交易的BDC,因为这类产品不仅比其他投资工具提供更优厚的费用结构,还能提供备受青睐的永续资本。然而,随着投资者大规模转向其他资产类别,这一权衡已发生改变。
Private credit managers are typically loathe to sell publicly traded BDCs, since they offer both a more attractive fee structure than other vehicles and provide much-coveted perpetual capital. But as investors have turned away from the asset class in droves, that calculus has changed.
一旦某只公开基金开始表现低迷,其增长能力便会受到限制,因为它无法以低于净资产价值的价格发行新股。同时,直接贷款规模也在萎缩,导致管理人可能面临基金业绩不佳却无太多选择的困境。
Once a public fund begins to trade poorly, its ability to grow can be limited because it is unable to issue equity below net asset value. With direct lending volume also shrinking, a manager can be left with an underperforming fund and few options.
退出路线A的交易可以采取多种形式。管理者可以通过合并收购BDC,也可以购买管理该基金的合同。其他选择还包括从基金中购买资产,这可以让卖方将剩余资产整合到关联实体中,或者直接将现金返还给投资者。
Exit Route A transaction can take several forms. A manager can buy a BDC through a merger or they can purchase the contract to run the fund. Other options include purchasing assets from the fund, which can allow the seller to combine what remains into an affiliated vehicle or simply return cash to investors.
据知情人士透露,一些公司正在探索这些选项,因为它们认为修复陷入困境的基金并无价值。对于全球最大的资产管理公司而言,它们管理着不同资产类别中数千亿美元的资金,一个相对规模较小但表现不佳的基金可能会成为巨大的干扰,尤其是在它们试图拓展退休账户业务之际。
Some firms are exploring these options because they don’t see the value in turning around their challenged funds, according to the people with knowledge. For the largest asset managers in the world, which oversee hundreds of billions of dollars across different asset classes, a relatively small underperforming fund can become an outsized distraction, especially as they look to push into retirement accounts.
例如,在贝莱德15.3万亿美元的庞大帝国中,TCPC的规模微乎其微。该基金已对不良贷款进行了减值处理,并因估值做法受到美国监管机构的调查。今年8月,它将约一半的资产组合出售给了二级市场专家Pantheon,并利用所得现金帮助降低该实体的杠杆水平。
TCPC, for example, is tiny in the scheme of BlackRock’s $15.3 trillion empire. The fund, which has marked down soured loans and been probed by US regulators over valuation practices, sold about half of its portfolio to secondaries specialist Pantheon in August, using the cash to help bring down leverage at the vehicle.
KBW的约翰逊表示:“BDC可能并不值得费心去处理,试图修复信用状况并持续参加公开电话会议讨论业绩,也未必值得投入时间。”他并未提及任何具体的基金。
“BDCs might not just be worth the trouble, and trying to repair the credits and constantly go on public calls to discuss performance not worth the time,” said KBW’s Johnson, without referring to a specific fund.
购买规模整合在直接贷款领域某种程度上已成为一种传统。包括Ares和Blackstone Inc.在内的公司通过收购竞争对手,建立了一些规模最大的业务发展公司(BDC)。BC Partners也整合了多支基金,其首席执行官Ted Goldthorpe在3月份告诉投资者,其两只公开交易基金的合并“扩大了我们的规模,并增强了投资组合的多元化程度”。
Buying Scale Consolidation is somewhat of a tradition in direct lending. Firms including Ares and Blackstone Inc. built some of the largest business development companies through acquisitions of rivals. BC Partners has also rolled up several funds, with Chief Executive Officer Ted Goldthorpe telling investors in March that a combination of two of its publicly traded funds “expanded our scale, and enhanced our portfolio diversification.”
Davis Polk & Wardwell律师事务所专注于私募信贷业务的合伙人Christopher Healey表示:“总体而言,小型业务发展公司可能成为并购目标这一想法本身并无新意。”他还说,如果投资规模不足10亿美元的资金开始考虑出售,他也不会感到意外。
“As a general matter, there’s nothing new about the idea that smaller business development companies can start to become merger targets,” said Christopher Healey, a partner at Davis Polk & Wardwell who specializes in private credit. He said he wouldn’t be surprised if more funds with less than $1 billion in investments started to think about selling.
对于买家而言,此类交易提供了一种快速扩张的方式,既能增加可收取费用的资产规模,也可能带来新的永久性资本来源。对某些机构来说,与公开交易实体合并也是为其现有私募基金提供流动性的一种颇具吸引力的方式。
For buyers, such deals offer a way to expand rapidly, boosting the assets that they can collect fees on, or potentially acquiring a new stream of permanent capital. For some, combining with a publicly traded vehicle is also an attractive way to provide liquidity for their existing private funds.
Healey表示:“这类交易的交易市场实际上非常活跃。尽管零售端出现了一些收缩,但我们仍然看到市场对于收购业务发展公司并扩大其资产规模的需求依然强劲。”
“The marketplace for these transactions is really robust and despite some of the retail pullback, we’re seeing that there is still an appetite to acquire BDCs and grow assets there,” said Healey.
交易方面,Ares和Apollo正在为佛罗里达州电信塔基础设施的所有者和运营商Phoenix Tower International牵头一笔65亿美元的债务融资。Waymo将其首次债务融资规模扩大至50亿美元,向多家贷款机构融资,以支持这家机器人出租车公司在全球扩张时的增长。Apollo计划为收购低成本航空公司EasyJet Plc而安排的35亿英镑债务融资选择飞机融资,而非高收益债券。
LIV Golf Ltd.获得了BC Partners Credit高达3亿美元的融资承诺,这或许能为其启动2027赛季提供所需资金。卖方顾问Lincoln International已启动所谓的“贷款人教育”流程,接触多家私人信贷公司,为IT公司Akquinet潜在剥离其医疗保健业务做准备。融资方面,Janus Henderson Group在其MENA私人信贷基金IV的第二轮关闭中筹集了1.91亿美元,更接近其3亿美元的筹资目标。
人事变动方面,Egan-Jones Ratings Co.聘请了美国证券交易委员会前雇员Kenneth Godwin担任其评级部门的高级总监,此前该公司对私人信贷工具的评级引发了市场担忧,而Godwin曾负责对该类公司的审查工作。
Deals Ares and Apollo are leading a $6.5 billion debt package for Phoenix Tower International, a Florida-based owner and operator of telecom tower infrastructure Waymo increased the size of its inaugural debt raise to $5 billion, tapping lenders to help fuel the robotaxi company’s growth as it expands globally Apollo is set to opt for aircraft financing rather than high yield bonds for a £3.5 billion debt package backing its acquisition of low-cost carrier EasyJet Plc LIV Golf Ltd. receives a financing commitment of as much as $300 million from BC Partners Credit, potentially obtaining the funding needed to launch a 2027 season Sellside adviser Lincoln International has tapped private credit firms in a so-called lender education process for a potential carve-out of IT company Akquinet’s healthcare business Fundraising Janus Henderson Group raised $191 million at the second close of its MENA Private Credit Fund IV, putting it closer to its $300 million target Job Moves Egan-Jones Ratings Co. tapped former US Securities and Exchange Commission staffer Kenneth Godwin, who oversaw examinations of firms like Egan-Jones, as its senior director for ratings amid concerns over its grading of private credit instruments