文/Georgia Hall 和 James Hirai欧洲债券市场的动荡引发了关于政策制定者在更广泛的金融危机发生时用以维持市场运转的工具的辩论。
Turbulence across Europe’s bonds is sparking debate over the tools policymakers use to keep markets functioning in the event of a broader financial crisis.
部分分析师正聚焦于欧洲央行的回购计划,银行可通过提供抵押品换取现金。尽管该计划并非作为危机机制而设计,但若环境进一步收紧,它被视为一项重要的流动性来源。
Some analysts are honing in on the European Central Bank’s repo program, where banks receive cash in exchange for collateral. While not conceived as a crisis mechanism, it’s treated as an important source of liquidity should conditions tighten further.
但所谓的主要再融资操作使用有限:银行在市场上获取资金成本更低。尽管流动性仍然充裕,分析师表示,动用该机制会带来污名效应,因为这可能被视为困境的信号。
But use of the so-called Main Refinancing Operations has been limited: it’s cheaper for banks to get funds in the market. While there’s still ample liquidity, analysts say there would be a stigma around tapping the facility because it can be seen as a sign of distress.
“我从未遇到过哪家银行资金部表示污名效应不是问题,”巴克莱银行欧洲利率策略主管Rohan Khanna表示。
“I have never met a bank treasury that said stigma is not an issue,” said Rohan Khanna, head of European rates strategy at Barclays Plc.
欧洲央行一直鼓励金融机构定期利用此类短期融资作为其流动性管理的一部分。市场分析师建议欧洲央行效仿英格兰银行,使融资成本更具吸引力,这将有助于减少污名效应。
The ECB has been encouraging financial institutions to regularly tap such short-term funding as part of their liquidity management. Market analysts suggest the ECB should follow the Bank of England by making funding costs more attractive, which would help to reduce the stigma.
仅本周,银行从英格兰银行的短期回购工具中借入近创纪录的1320亿英镑(1750亿美元),是从同等期限(一周)的欧元区计划中借入的180亿欧元(200亿美元)的八倍多。
Just this week, banks tapped the BOE’s Short-Term Repo for a near-record £132 billion ($175 billion), more than eight times the €18 billion ($20 billion) borrowed from the equivalent one-week euro-area program.
“欧元区也可以从英国汲取这方面的经验,”伦敦政治经济学院访问高级研究员Eddie Gerba表示,他此前曾为英格兰银行做研究并为欧洲央行提供建议。“有经验可循,关于如何深化回购市场,以及如何提升其在银行业短期融资中的重要性。”
“That’s where the euro zone can also learn from the UK,” said Eddie Gerba, a visiting senior fellow at the London School of Economics, who has previously done research for the BOE and advised the ECB. “There’s lessons to be learned about how can it deepen the repo market and how it increases its importance in the banking sector’s short term funding.”The issue is coming to the fore as the euro area’s excess reserves have declined toward €2 trillion from a peak above €4.5 trillion four years ago. That’s helped drive an increase in euro-area repo rates to their highest since March 2025.
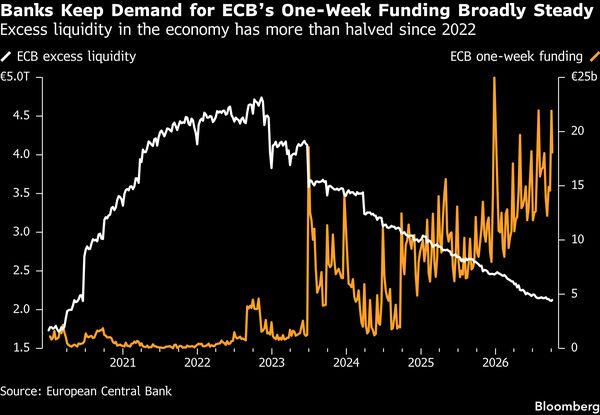
随着欧元区超额准备金从四年前超过4.5万亿欧元的峰值下降至接近2万亿欧元,这一问题日益凸显。这助推欧元区回购利率升至2025年3月以来的最高水平。
RBC Capital Markets said repo rates could rise further due to heavy bond issuance from governments, singling out France’s record funding plan for 2027. The nation’s political and fiscal issues are leading to the risk of contagion in the region, and RBC pointed to an “unusually sharp move” in European repo markets at the end of last month as an “ominous signal” of tighter liquidity.
RBC资本市场表示,由于政府大量发行债券,回购利率可能进一步上升,特别指出法国2027年的创纪录融资计划。该国的政治和财政问题正导致该地区出现传染风险,RBC指出上月末欧洲回购市场出现“异常剧烈的波动”,是流动性收紧的“凶兆”。
Andrea Appeddu, director of research at Citigroup Inc, said so far demand for cash at the MRO is insufficient to make up for falling excess liquidity.
花旗集团研究部总监Andrea Appeddu表示,迄今为止,MRO的现金需求不足以弥补过剩流动性的下降。
Repo programs are not the only mechanism that can help the functioning of markets should conditions deteriorate. The ECB can also buy bonds via its so-called Transmission Protection Instrument, or TPI, a completely separate tool. But that has yet to be activated after being created in 2022. France’s finance minister said the country is far from needing the ECB to step in.
回购计划并非在市场状况恶化时唯一可以帮助市场运作的机制。欧洲央行还可以通过其所谓的传导保护工具(Transmission Protection Instrument,TPI)购买债券,这是一种完全独立的工具。但该工具自2022年设立以来尚未被激活。法国财政部长表示,该国远未到需要欧洲央行介入的程度。欧洲央行和英格兰银行均未置评。
The ECB and the BOE declined to comment.
财政主管们担心的并不是欧洲央行会识别个别借款人——它并不会这样做。但它会公布欧元体系在国家层面的借款数据。如果某国的借款突然上升,交易员和银行家可能会迅速试图找出是哪家机构负责——从而导致市场对其进行押注的可能性。
The concern among treasurers is not that the ECB identifies individual borrowers — it doesn’t. But it publishes Eurosystem borrowing data at the national level. If borrowing suddenly rises in one country, traders and bankers could quickly start trying to work out which institution is responsible — leading to the potential for the market to bet against it.
巴克莱的Khanna说:“如果某个国家的数字上升,谣言就会开始:是谁?是谁?是谁?” “然后局面就会一路下滑。”如果贷款方继续回避这类融资,私人回购市场的需求将保持在更高水平,可能推高有担保借款成本,使流动性状况更难预测。
“If that one country’s number goes up, then the rumor mill starts: Who is it? Who is it? Who is it?” said Barclays’ Khanna. “And then it goes downhill from there.”If lenders continue to avoid this funding, more demand will remain in private repo markets, potentially pushing up secured borrowing costs and making liquidity conditions less predictable.
“这可能意味着:流动性储备不再处于‘过剩’状态的转折点,会比目前市场预期的时间更早到来,”包括彼得·沙弗里克在内的RBC策略师们指出。“未来几个月里,那些对流动性变化敏感的债券利差产品及利率结构值得密切关注。”这对欧洲央行而言形成了一种尴尬的局面:央行希望各银行能更积极地参与其常规再融资操作,但银行家们却表示,目前几乎没有措施能降低参与这些操作所带来的声誉风险。
“It may be signaling that the transition point at which reserves cease to be ‘in excess’ is approaching sooner than the market currently prices,” RBC strategists including Peter Schaffrik said. “Spread products and rate structures sensitive to liquidity dynamics merit close attention in the months ahead.”That creates an awkward dynamic for the ECB. The central bank will want banks to become more comfortable using its regular refinancing operations, yet bankers say little has been done to reduce the perceived reputational cost of doing so.
随着欧洲央行行长克里斯蒂娜·拉加德的任期将于明年届满,瑞银集团的雷努特·德博克预计,她的继任者会通过加强沟通来妥善处理这一问题。
With ECB President Christine Lagarde’s term up next year, UBS Group AG’s Reinout De Bock expects her successor to be “on top of this” with more communication.
“欧洲央行非常希望看到更多银行参与其短期融资操作,”德国商业银行利率与信贷研究主管克里斯托夫·里格尔说道。他认为,欧洲央行有必要降低银行获取资金的成本,从而使其利率水平更贴近当前货币市场的实际利率水平。
“The ECB would love to see more participation in its short term operations,” said Christoph Rieger, head of rates and credit research at Commerzbank AG. He said the ECB would need to lower the cost of accessing its funds to more closely align rates with those currently available in money markets.
对于道明证券的普贾·库姆拉而言,鉴于近期市场的剧烈波动,欧洲央行应当进一步提升该融资工具的吸引力。
For Pooja Kumra at TD Securities, the ECB should make the facility more attractive given the recent volatility in the market.
“若出现更广泛的金融环境收紧现象,欧洲央行就需要采取更强有力的应对措施以稳定市场,”她指出。“一旦出现与银行流动性相关的风险,欧洲央行便可以更低的利率向银行开放这些融资渠道。”另一个可能的方案是设计一种博弈论式的机制:强制所有银行同时使用该融资工具,如此一来市场便难以判断哪家机构正面临流动性压力,从而避免出现针对特定银行的恶意揣测与排挤现象。
“Broader financial tightening may require a more forceful response from the ECB to help stabilize markets,” she said. “If there are risks linked to bank liquidity, the ECB could make these operations more accessible at a cheaper rate.”Another potential option is to create a game-theory scenario in which every bank is required to use the facility at the same time, making it harder for markets to infer which institution is under stress and avoiding any witch hunts.
“欧洲央行已经出台了诸多正确的举措,但要实现政策正常化,不仅需要调整沟通方式及定价机制,还需要有足够多的银行持续参与这些操作,”英国雷丁大学亨利商学院ICMA中心的金融学副教授伊万·桑乔吉说道。
“The ECB has put many of the right elements in place, but normalization requires not only a change in communication and pricing but also repeated use by a sufficiently broad range of banks,” said Ivan Sangiorgi, associate professor of finance at the ICMA Centre in the University of Reading’s Henley Business School.