法国巴黎银行表示,市场对一项曾备受追捧、但最终令人失望的荷兰养老金体系改革利率押注的热情正在回升,该体系规模达1.7万亿欧元(合1.9万亿美元)。
Appetite for a popular, but ultimately disappointing rates bet on the overhaul of the €1.7 trillion ($1.9 trillion) Dutch pension industry is returning, according to BNP Paribas SA.
在去年一度变得拥挤的交易中,投资者押注荷兰的改革将扩大短期与长期利率互换之间的差距。他们的算盘是,随着养老金基金解除对冲,现金流出较长期的欧洲政府债券,利率曲线的长端相对于短端将会走高。
In what became a crowded trade last year, investors wagered the Dutch revamp would widen the gap between short- and long-dated interest-rate swaps. Their calculation was that as pension funds unwound their hedges and cash flowed out of longer-maturity European government bonds, the long end of the rates curve would move higher relative to the short end.
但今年早些时候,随着转变的进行,事情并没有像预期那样发展。过重的持仓意味着行情变动不如预期般大,而美伊战争则导致能源价格飙升,反而推高了短期利率。这缩窄了互换利差,甚至将长期利率压低至短端利率以下。
But it didn’t play out as expected earlier this year, with the shift underway. The heavy positioning meant the moves were smaller than hoped, while the US-Iran war sent energy prices spiraling and drove up shorter rates instead. That narrowed the swaps spread and even pushed long-term rates below shorter ones.
利率策略师史蒂文·蒙哥马利表示,随着过渡期仅剩一年多一点,且欧洲央行的加息预期显得过高,市场兴趣正在重新回升。
With just over a year of the transition still to go and expectations for rate hikes by the European Central Bank looking overdone, interest is picking up again, according to rates strategist Steven Montgomery.
“在过去的一个月里,我被问及关于荷兰养老金的问题比前五个月要多得多,”蒙哥马利说。他认为利率互换曲线在年底前可能会变陡。
“I have been asked a lot more questions in the last month than the preceding five months about Dutch pensions,” said Montgomery, who sees the swaps curve as likely to steepen through year-end.
荷兰央行数据显示,截至6月底,已有5890亿欧元的养老金基金资产转换为新体系,在2028年1月1日的截止日期之前,仍有1.131万亿欧元的养老金资产有待转换。
At the end of June, €589 billion of pension fund assets had been converted to the new system, leaving €1.131 trillion of pension assets still to go by the Jan. 1, 2028 deadline, Dutch central bank data show.
蒙哥马利表示,所谓的陡峭化交易(steepener trade)获得回报的几率更高,因为尝试从中获取转型潜在影响利润的投资者少得多。他说,该交易在曲线长端的受欢迎程度目前仅为其在投机投资者中鼎盛时期的五分之一左右。“共识交易已不再那么具有共识,”蒙哥马利说。
Montgomery said there’s a better chance of the so-called steepener trade paying off because far fewer investors are trying to profit from the potential impact of the transition. Its popularity at the longer end of the curve is now about a fifth of what it was at its peak among speculative investors, he said. “The consensus trades are a lot less consensus,” Montgomery said.
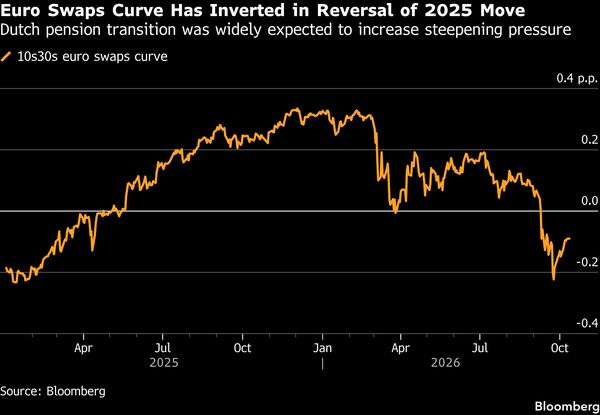
10年期与30年期互换利差曲线目前倒挂在负9个基点左右,该曲线在去年大部分时间里都在走陡,并在12月达到了34个基点的峰值。
The 10s30s curve — the gap between 10- and 30-year swaps — is currently inverted at around minus nine basis points, having steepened for much of last year, hitting a peak of 34 basis points in December.
对该交易的兴趣减退也是因为一项规则的改变,该改变给予了养老金基金在转型后更长的时间来调整其对冲。与此同时,一些基金还表示将保留比预期更多的对冲,从而减弱了陡峭化压力。
Interest in the trade also faded due to a rule change that gave pension funds longer to adjust their hedging after transitioning. Meanwhile, some funds also indicated they would retain more hedges than expected, reducing steepening pressure.
2026年的市场背景也不是交易员们所预期的,油价和欧洲央行货币政策的前景成为了主要驱动力。能源价格走势的不确定性让他们对重新进行陡峭化交易感到不安。
And the market backdrop in 2026 wasn’t what traders were expecting, with oil prices and the outlook for ECB monetary policy the dominant driver. The uncertainty about energy-price moves made them nervous about putting the steepener trade back on.
法国巴黎银行利率策略主管亚当·库尔皮耶尔表示:“欧洲央行的情况将比养老金基金的情况更重要,”他预测到年底10年期与30年期利差曲线将处于负20个基点。“欧洲央行鹰派定价的峰值还在后头。”蒙哥马利对欧洲利率的走势持有不同看法。在他看来,加息预期过高,如果央行政策比市场预测的更加宽松,可能会拉低短期利率,从而对陡峭化交易产生帮助。
“The ECB story will matter more than the pension fund story,” said Adam Kurpiel, head of rates strategy at Societe Generale SA, forecasting the 10s30s curve will be at minus 20 basis points by year-end. “Peak hawkish ECB pricing still lies ahead.”Montgomery disagrees on the path for interest rates in Europe. In his view, rate-hike expectations are overdone and if central bank policy comes in looser than the market predicts, it could bring shorter rates down, helping the steepener trade.
他说:“鉴于我们对欧洲央行的看法比市场更为鸽派,且鉴于我们认为今年荷兰养老金转型的实际影响可能被有些许低估,我们在年底及整个跨年期间将倾向于利率曲线变陡。”
“Given we have a more dovish view on the ECB than the market, and given we think that the Dutch pension transition is probably slightly underappreciated this year, we would have a steepening bias into and across year end,’ he said.