经纪人在欧洲回购市场中的份额升至自2012年以来的最高水平,原因是自动化交易在伊朗战争引发的动荡中失去了优势,而更为隐蔽的融资方式却有所增加。
Brokers increased their share of Europe’s repo market to the highest since 2012 as automated trading lost ground to more discreet ways of raising cash during turbulence sparked by the Iran war.
根据国际资本市场协会(ICMA)对银行及其他机构进行的半年度调查,中介机构在6月份占未到期回购协议的16.2%,较前六个月上升约2.5个百分点。此前,政府债券出现抛售,投资者出现“逐利求流动性”现象。交易系统的份额降至16年来的最低点24.3%。
Intermediaries accounted for 16.2% of repurchase agreements outstanding in June, up about 2.5 percentage points over the previous six months, following the selloff in government bonds and a “flight to liquidity” among investors, according to the International Capital Market Association’s biannual survey of banks and other institutions. The share for trading systems dipped to a 16-year low of 24.3%.
回购交易主要是以抵押品(通常是政府债券)为担保的短期贷款,双方约定在特定日期以利息形式归还本金。尽管该交易日益实现自动化,但通过电话或即时通讯应用程序连接买卖双方的人员自2022年以来卷土重来,尤其在市场流动性不足或波动加剧时表现突出。
Repos are mostly short-term loans secured against collateral, typically government bonds, with an agreement to pay them back at a set date with interest. The trade has become increasingly automated but the people who connect buyers and sellers via phone or messaging apps have staged a comeback since 2022, particularly during times when markets are thin or volatile.
“语音经纪人的核心优势在于,当交易量突然激增时,他们能够立即扩大交易商的市场覆盖范围,”编写ICMA报告的理查德·科莫托写道。“在处理较大规模交易时,语音经纪人可以将其拆分,并将较小的部分逐步纳入市场,同时避免过多信息泄露。”电子交易平台在高频、标准化交易方面表现出色,但在处理期限较长或不规则的交易、大额交易、风险较高的抵押品或更具“信息敏感性”的交易时可能会遇到困难,科莫托写道。
“The core benefit of voice-brokers is that they are able to immediately extend the market coverage of dealers when volumes suddenly surge,” wrote Richard Comotto, who compiled the ICMA report. “In the case of larger transactions, voice brokers can break them up and work the smaller pieces into the market without too much information leakage.”Electronic marketplaces excel at high-volume, standardized trades but can struggle with longer or irregular maturities, larger deals, riskier collateral or more “information-sensitive transactions,” Comotto wrote.
相比之下,经纪人能够依托长期建立的关系,在交易活动突然激增时帮助交易商寻找流动性,且他们往往更不愿主动报价。
By contrast, brokers can draw on relationships built over time to help dealers find liquidity when activity suddenly increases and they tend to be more reluctant to show prices.
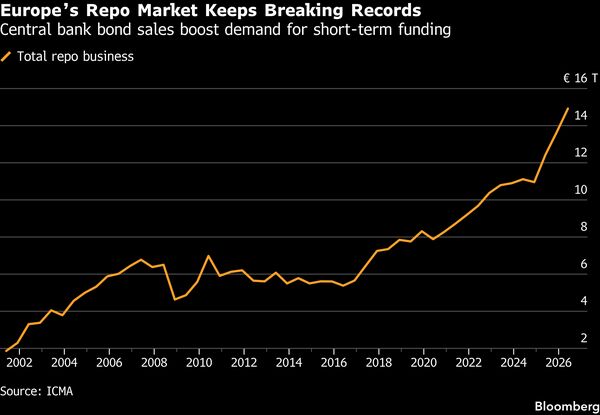
2026年上半年,欧洲回购市场活动持续扩张。调查的60家受访机构账面上的回购和逆回购总额在6月10日达到创纪录的14.92万亿欧元(约16.7万亿美元),较12月增长9.3%。
Activity in European repo markets continued to expand in the first half of 2026. The total value of repos and reverse repos on the books of the survey’s 60 respondents stood at a record €14.92 trillion ($16.7 trillion) on June 10, up 9.3% since December.
BrokerTec(CME Group Inc.旗下的自动化交易系统)全球回购业务负责人Sara Carter表示,在波动期间,电子平台和语音平台的回购市场交易量均有所增加。
Repo market transactions increase across electronic platforms and voice during periods of volatility, said Sara Carter, global head of repo at BrokerTec, an automated trading system operated by CME Group Inc.
她补充道:“市场参与者通常会减少敞口并缩短回购到期日,转向日内交易,以求获得快速平仓 outright 头寸的灵活性。”
“Market participants typically reduce exposure and shorten repo maturities to daily trades, seeking the flexibility to quickly unwind outright positions,” she added.
ICMA调查发现,欧洲相较于美国对能源冲击的敞口更大,导致欧元计价交易的份额上升,并且欧洲抵押品的使用增加,尤其是核心欧元区政府债券。
Europe’s greater exposure to the energy shock than the US led to a rising share of euro-denominated trades and greater use of European collateral, particularly core euro-area government bonds, the ICMA survey found.
然而,尽管波动加剧且央行实施量化紧缩,但上半年回购利率总体保持稳定。量化紧缩可通过增加对短期有担保融资的需求来提升回购活动,因为交易商在融资更大规模的政府债券存货时会产生此类需求。
Despite the increased volatility and quantitative tightening by central banks, however, repo rates were generally stable in the first half of the year. QT can boost repo activity by increasing demand for short-term secured funding as dealers finance larger government bond inventories.
Comotto指出,英国是个例外,因为互换市场从定价英格兰银行降息转为定价加息,“导致对冲基金减少了在 gilt(英国国债)上的长期现金头寸”。他补充说,这些卖出主要被“实盘投资者”吸收,从而降低了对回购融资的需求。
The UK was an outlier as the swaps market switched from pricing Bank of England interest rate cuts to hikes and “caused hedge funds to cut long cash positions in gilts,” according to Comotto. Those sales were mostly absorbed by “real money investors,” reducing the demand for repo funding, he added.