Bassman是美国国债最广泛跟踪指标之一的先驱,他警告称,市场上一个鲜为人知的特征正威胁着加剧数月来的抛售,并推动债券收益率进一步上升。
Bassman, pioneer of one of the most widely followed indicators for US Treasuries, warns that a little-noticed feature of the market is threatening to worsen a monthslong selloff and push bond yields even higher.
他在Convexity Maven通讯的一篇帖子中表示,风险源于交易者提供在期货合约结算时交付的债券的方式。
In a post in his Convexity Maven newsletter, Bassman said the risk stems from the way traders provide the bonds that are delivered when futures contracts are settled.
他指出,最近收益率的急剧上升——这导致长期到期债券价格下跌最为显著——使得最长期限的证券成为所谓的‘最便宜交割’规则下用于满足合约的证券。但这些证券也具有更高的久期,这意味着当利率上升时,它们面临更大幅度下跌的风险。
He said the sharp jump in yields recently — which has driven down the prices of longer-maturity bonds the most — has turned the longest-dated securities into those that will be used to satisfy the contracts under so-called cheapest-to-deliver rules. But those securities also have higher duration, meaning they are at risk of tumbling more when interest rates rise.
为了抵消这种敞口,基金经理可能在合约到期前夕抛售其他长期债券,从而在价格下跌时产生一种放大抛售的动态。他表示,与债券期货相关的负凸性——即与之相关的巨大下行风险——已升至自2007年以来未见的水平,并可能在美国国债抛售的最新阶段中发挥了作用。
To offset that exposure, fund managers may unload other long-dated bonds just before the contracts expire, creating a dynamic that amplifies selling just when prices are declining. He said the negative convexity associated with bond futures — or the outsize downside risk associated with them — has risen to levels not seen since 2007 and may have played a role in the latest leg of the Treasury selloff.
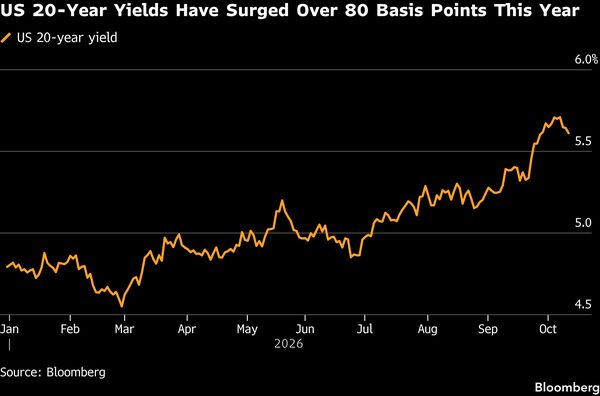
‘经过近二十年,华尔街的债券交易又回到了“美好时光”’,他写道。‘由于这些是超安全的无风险美国国债期货,买家可能没有完全认识到这一具有挑战性的风险特征。’Bassman表示,如果20年期美国国债收益率突破6%,这将构成特别风险,因为这将触发一种‘噩梦场景’的抛售压力,相当于拍卖1100亿美元的这些证券。目前20年期收益率约为5.6%。
“After nearly twenty years, it is back to ‘fun times’ for Wall Street’s Bond trading,” he wrote. “Since these are super-safe risk-free US Treasury bond futures, it is possible buyers did not fully appreciate this challenging risk profile.”Bassman said that poses a particular risk if the 20-year Treasury yield crosses 6%, saying that would create a “nightmare scenario” of selling pressure that would be equivalent to the auction of $110 billion of the securities. The 20-year yield is currently around 5.6%.
面临期货交割相关风险的包括投资经理,他们使用期货来对冲政府债券头寸,以及杠杆基金,它们在诸如流行的基差交易等策略中使用期货。
Those exposed to the risk associated with the futures deliveries include investment managers, who use futures to hedge government bond positions, and leveraged funds, which employ them in strategies such as the popular basis trade.