全球债券抛售正给固定收益投资者提供一个难得的机会,让他们能够锁定类似亚洲垃圾债券的收益率,而无需承担此类债务的信用风险,据KKR & Co.称。
The global bond rout is giving fixed-income investors a rare chance to lock in Asian junk bond-like payouts without the credit risk of such debt, according to KKR & Co.
“我们将其视为一个提升投资组合质量的机会,而非留在场外观望的理由,”该美国公司亚洲流动性信贷主管潘登兆表示,该公司截至6月底管理资产达7960亿美元。“向信用曲线上端移动能给投资者带来更宽的安全边际、更低的预期信用损失。”
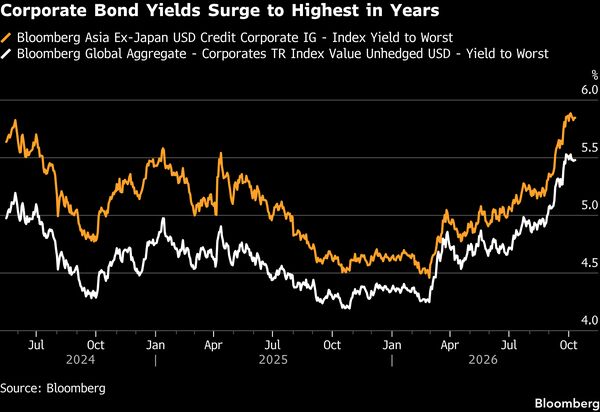
“We view this as an opportunity to rotate the portfolio up in quality, rather than a reason to stay on the sidelines,” said Dengzhao Pan, head of Asia liquid credit at the US firm, which had $796 billion in assets under management at the end of June. “Moving up the credit curve gives investors a wider margin of safety, lower expected credit loss.”Yields on investment-grade corporate bonds, including Asian debt, are near their highest in more than two years after the Middle East conflict drove up oil prices and prompted central-bank tightening. That has pushed yields on some higher-quality debt closer to those typically associated with junk bonds, while investors benefit from issuers with stronger balance sheets and a lower risk of default.
中东冲突推高油价并促使央行收紧政策,导致投资级企业债券(包括亚洲债券)收益率升至两年多来的高位。这使得一些优质债务的收益率逼近通常与垃圾债券相关的水平,而投资者则受益于发行人更强的资产负债表和更低的违约风险。
Asian investment-grade dollar bonds now yield an average 5.8%, with longer-dated and subordinated debt offering even higher payouts, according to data compiled by Bloomberg.
根据彭博汇编的数据,亚洲投资级美元债券目前平均收益率为5.8%,期限较长和次级债务提供的收益率甚至更高。
Sony Life Insurance Co. last month sold a subordinated dollar bond callable in 10 years at a 7.125% yield carrying an A- rating from S&P Global Ratings, a payout more commonly associated with lower-rated debt. A bond sold last month by Mitsubishi UFJ Financial Group Inc., which can be called in seven years and also has an A- rating, currently yields around 6%, according to data compiled by Bloomberg.
索尼人寿保险株式会社上月发行了一只10年可赎回的次级美元债券,收益率为7.125%,获得标普全球评级A-评级,这种收益率更常见于低评级债务。根据彭博汇编的数据,三菱UFJ金融集团上月发行的一只7年可赎回债券,同样获得A-评级,目前收益率约为6%。
“Our conviction area is Japanese financials, large-cap banks, and life insurance companies in particular, where we like the 5 to 7 year part of the curve for the best balance of yield and duration risk,” said Pan, who runs a public debt strategy unconstrained by credit ratings, in an interview last week.
“我们的高信心配置领域是日本金融机构,特别是大型银行和人寿保险公司,我们看好曲线5至7年期段,以获得收益率和久期风险的最佳平衡,”潘登兆在上周的一次采访中表示,他管理的一只公开债券策略不受信用评级限制。
He added that while he isn’t expecting a recession, he is staying clear of distressed situations and prefers to own higher-quality bonds, with no near-term solution to the Middle East conflict in sight.
他补充说,虽然他并不预期会出现衰退,但他正在远离困境局面,更倾向于持有更高质量的债券,目前中东冲突也没有短期解决方案的迹象。
Asian high-grade corporate bonds have lost an average 1.4% this year, compared with a 2.5% decline for US peers, Bloomberg indexes show. Their shorter duration has helped cushion the selloff, averaging about 4.6 years compared with 6.4 years for US debt.
彭博指数显示,亚洲高评级企业债券今年平均下跌1.4%,而美国同类债券下跌2.5%。其更短的久期有助于缓解抛售压力,平均约为4.6年,而美国债务的久期平均为6.4年。
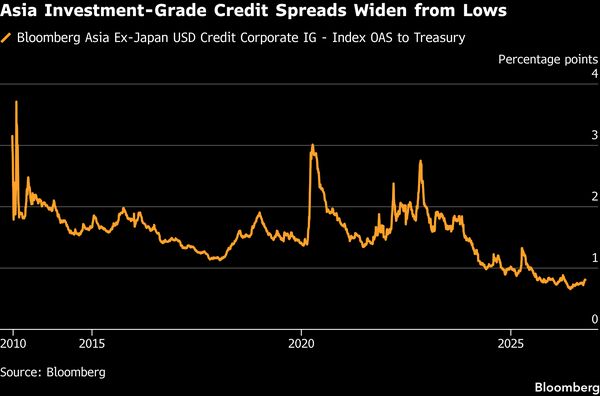
Spreads on Asian high-grade bonds have widened 15 basis points from a more-than-decade low in early June as debt-market volatility increased, though they remain two basis points tighter than at the end of 2025.
随着债务市场波动加剧,亚洲高评级债券的利差较6月初的十年多低点扩大了15个基点,尽管它们仍比2025年末紧2个基点。
“In credit, the first thing that you want to make sure of is that you don’t lose money,” said Pan. The crossover bond space of BB/BBB-rated debt is “where we think the risk reward is most favorable right now,” he added.
“在信贷领域,你首先要确保的是不亏损,”潘说。BB/BBB评级债券的交叉债券领域是“我们目前认为风险回报最有利的领域”,他补充道。另见:华尔街策略师在债券暴跌后认为久期具有价值
Read also: Wall Street Strategists See Value in Duration After Bond Rout