新加坡银行股抛售引发买入低点的呼声,一些分析师指出,随着新加坡巩固其作为全球金融中心的地位,这些贷款机构的长期增长前景值得关注。
A selloff in Singapore banks is sparking calls to buy the dip, with some analysts pointing to the lenders’ long-term growth prospects as the city-state strengthens its position as a global financial hub.
从麦格理集团有限公司(Macquarie Group Ltd.)到杰富瑞金融集团公司(Jefferies Financial Group Inc.)和富兰克林邓普顿公司(Franklin Templeton Inc.),分析师和基金经理正敦促投资者放眼过去一周的抛售潮,该抛售潮抹去了新加坡三大银行合计220亿美元的市值。他们的乐观情绪建立在新加坡作为财富中心日益增长的地位之上,这正直接提升星展集团控股有限公司(DBS Group Holdings Ltd.)、华侨银行(Oversea-Chinese Banking Corp.)和大华银行(United Overseas Bank Ltd.)的利润。
From Macquarie Group Ltd. to Jefferies Financial Group Inc. and Franklin Templeton Inc., analysts and fund managers are prodding investors to look past last week’s selloff, which erased a combined $22 billion in market value from the city state’s three biggest banks. Their optimism rests on Singapore’s growing status as a wealth hub, which is directly boosting profits at DBS Group Holdings Ltd., Oversea-Chinese Banking Corp. and United Overseas Bank Ltd.
“新加坡银行的长期前景仍然保持积极,”富兰克林邓普顿全球投资(Franklin Templeton Global Investments)组合经理廖一平(Yiping Liao)表示。“展望近期之后,我们预计净息差将在随后几个季度触底,而非息收入将受益于财富向新加坡转移的结构性转变。”情绪转变发生在投资者因担心债券收益率升至数十年高点可能削弱其作为股息玩具的吸引力,并可能导致其债券持仓出现亏损而抛售星展、华侨银行和大华银行股票之后。
“The long-term outlook still remains positive for the Singapore banks,” said Yiping Liao, portfolio manager at Franklin Templeton Global Investments. “Looking past the near-term, we expect net interest margins to trough in subsequent quarters and non-interest income to benefit from the structural shift in wealth moving to Singapore.”The shift in sentiment comes after investors dumped shares of DBS, OCBC and UOB on concerns that a run-up in bond yields to multi-decade highs could erode their appeal as dividend plays and saddle them with losses on their bond holdings.
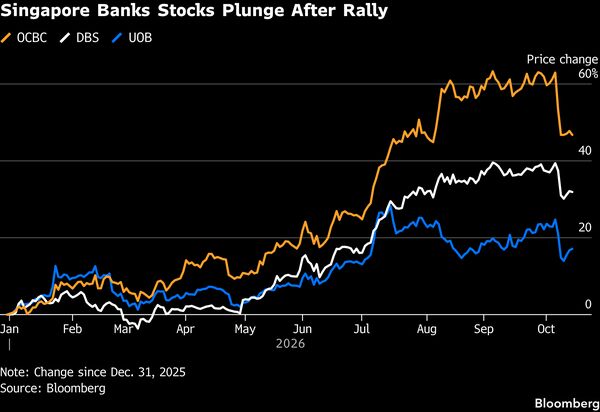
虽然完整影响将在未来几周第三季度财报发布时变得更加清晰,但此次抛售已经削弱了新加坡作为今年亚洲表现最佳的主要股票基准之一的地位。
While the full impact will become clearer when third-quarter earnings are released in the coming weeks, the rout has dented Singapore’s standing as one of Asia’s best-performing major stock benchmarks this year.
抛售使得一些分析师认为估值更具吸引力,新加坡最大贷款机构星展银行目前的市净率为2.9倍的前瞻性收益,较9月峰值的3.1倍有所下降。
The selloff has made valuations more attractive to some analysts, with Singapore’s largest lender DBS now trading at price-to-book value of 2.9 times forward earnings, down from a September peak of 3.1 times.
银行股下跌“为长期投资者提供了良好的买入机会”,杰富瑞分析师贾娜· Cheah(Joanna Cheah)如此表示。她上周称,净新增资金和资产管理规模趋势仍然健康,可以说是衡量特许经营动能更好的指标,而贷款增长也一直保持强劲。
The decline in bank shares “provides a good buying opportunity for long-term investors,” according to Joanna Cheah, an analyst at Jefferies. Net new money and assets-under-management trends remain healthy and are arguably better indicators of franchise momentum, while loan growth has also remained robust, she said last week.
当然,高收益率的担忧仍在持续,周三美国通胀高于预期,助长了美联储将采取更激进加息的押注。
To be sure, concerns of high bond yields persist, with hotter-than-expected US inflation on Wednesday fueling bets of more aggressive rate hikes by the Federal Reserve.
摩根大通公司上周警告称,长期债券收益率上升可能导致银行交易账簿出现高额按市价计价损失,并损害资本活动。花旗集团公司分析师杨永宏也指出,如果当前的风险规避情绪持续,财富管理费用的指引可能会走弱。
Rising long bond yields could trigger high mark-to-market losses on banks’ trading books and hurt capital activity, JPMorgan Chase & Co. warned last week. Citigroup Inc. analyst Yong Hong Tan also flagged the risk of weaker guidance on wealth-management fees if the current risk-off sentiment persists.
虽然该行的交易收入本季度可能面临更大逆风,但麦格理分析师杰登·万塔拉基斯表示,投资者更可能将注意力转向财富管理收入以及在利率上升环境下净利息收入的前景。他说,这次下跌“是一个重新买入的机会”。
While the bank’s trading income may face greater headwinds this quarter, investors are likely to focus more on wealth management income and the outlook for net interest income in a rising rate environment, said Macquarie analyst Jayden Vantarakis. The slide is “an opportunity to buy back in,” he said.