美国财政部长斯科特·贝森特(Scott Bessent)8月份出人意料地决定增加对旧证券的购买规模,令街头交易商措手不及。目前,他们正计划采取更多主动行动,而关键线索可能将于周五浮出水面,届时财政部正准备在11月更新其债务管理计划。
Street traders wrong-footed by Treasury Secretary Scott Bessent’s surprise August decision to upsize purchases of older securities are game-planning for more activism, with key clues potentially surfacing Friday as the department prepares to update its debt management plans in November.
贝森特的“财政部转向”举措是为了应对美国国债收益率的飙升,而这一问题正是特朗普政府曾承诺降低借贷成本的敏感议题——该举措最初确实产生了一定效果。然而,贝森特以这种方式进行干预,实际上也打破了财政部数十年来“行动规律且可预测”的惯例,这一惯例旨在长期实现最低债务成本。
Bessent’s “Treasury twist” came in response to surging US yields, a sore spot for a Trump administration that had promised to deliver lower borrowing costs — and it initially did have an effect. But by intervening as he did, Bessent also effectively tore up the Treasury’s decades-long playbook of being “regular and predictable” with its actions to achieve the lowest debt costs over time.
从宏观角度来看,此举引发了关于此类操作是否可能因引入不确定性而加剧市场波动的争论。不过,从更实际的角度而言,它也让华尔街开始关注财政部在11月下一次季度债务再融资公告中可能采取更多主动行动的可能性——该公告将在中期选举仅一天后发布。
From a high-level perspective, the move sparked debate over whether such tinkering, by injecting uncertainty, might end up making the market more volatile. On a more practical note, though, it put Wall Street on watch for the possibility of further activism at the Treasury’s next quarterly debt-refunding announcement in November, just one day after midterm elections.
周五,在债务再融资之前,财政部将向最大的债券交易商发送一份调查问卷清单。市场观察人士称,这些问题所反映的内容或将成为检验贝森特政策倾向的罗夏墨迹测试。
On Friday, the biggest bond dealers will receive a list of survey questions by the Treasury ahead of the refunding. Market watchers say the nature of the queries may serve as a Rorschach test of Bessent’s leanings.
“你们已经向市场宣布,这些收益率水平存在问题,”摩根士丹利投资管理公司固定收益部门负责人维沙尔·坎杜贾(Vishal Khanduja)表示。“因此,我们认为接下来的两次债券发行(其中11月的发行将在中期选举之后进行)将具有决定性意义。”摩根士丹利银行部门的策略师马丁·托比亚斯(Martin Tobias)指出,财政部有多种选择。
“You’ve announced to the market that these yield levels are problematic,” said Vishal Khanduja, head of broad markets fixed income at Morgan Stanley Investment Management. “That’s why we believe that the next two refundings, with November right after the midterms, are going be pivotal.”There are several ways the Treasury could go, said Martin Tobias, a strategist on the banking side at Morgan Stanley.
最常规的做法是维持现状:至少在未来几个季度内保持当前的债券拍卖规模,并不调整未来的发行计划(就像8月份那样)。另一种选择是调整未来的发行计划,不再增加长期债券的发行量,而是重点增加2至7年期债券的发行。
The most conventional option would be a continuation of the status quo: maintaining current auction sizes at least for the next several quarters with no changes to forward guidance, as it did in August. Another alternative would be to revise forward guidance on issuance to exclude increases to the longer-dated securities, while focusing on increases in two- to seven-year maturities.
还有一种较为非传统的做法是明确规定财政部在债券发行中的份额上限。尽管债券发行规模一直在增加,但官员们至今仍未明确表示他们愿意容忍财政部占据多大的市场份额。
Yet another option — and least conventional — would be to explicitly state how large the Treasury’s share of bills can be. Officials have never articulated how large a slice they’re willing to tolerate, even as the share of bill issuance has grown.
对于哥伦比亚Threadneedle投资公司的投资组合经理埃德·阿尔-侯赛尼(Ed Al-Hussainy)来说,从纳税人的角度来看,最好的选择应该是为政府提供5年期债券的融资,而不是30年期债券。
For Ed Al-Hussainy, portfolio manager at Columbia Threadneedle Investments, the best option from a taxpayers’ perspective would be to finance the government in the five-year area instead of as long as 30 years.
“如果你的目标是阻止收益率继续上升,那么你就真的需要发挥创造力了,”他说。财政部的一位代表没有立即回应我们的评论请求。
“If your objective is to stop the movement of yields higher, then you are going to have to get really creative,” he said. A representative for the Treasury didn’t immediately respond to a request for comment.
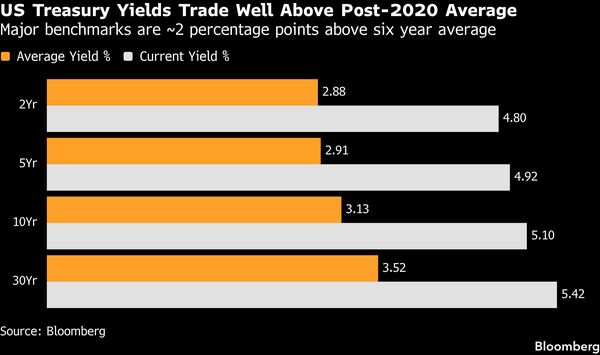
市场参与者认为所有这些选项都有可能被采用,因为目前美国乃至全球的长期基准利率都处于几十年来的最高水平。收益率的上升主要是由于油价上涨以及美联储重新开始加息(这反映了经济扩张带来的通胀压力)。此外,由于人工智能企业需要大量资金来支持其快速增长,全球范围内也存在着对资本的激烈竞争。
Market participants see every option as a possibility, with long-term benchmark yields near their highest in decades in the US and globally. The rise has been fueled by higher oil prices and a Federal Reserve resuming rate hikes that reflects economic expansion replete with sticky inflation. There is also global competition for capital as AI hyperscalers borrow heavily to fund their explosive growth.
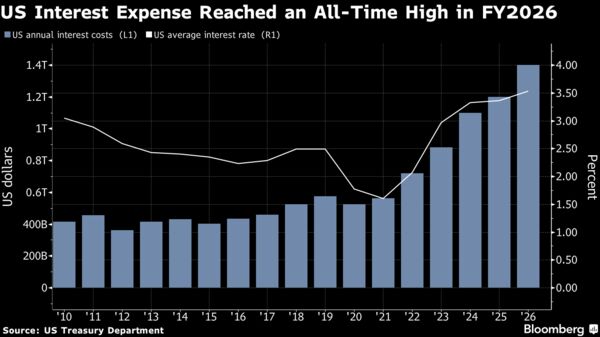
所有这些情况都表明:美国的年度利息支出首次突破1万亿美元大关,债务偿还成本现已超过国防预算,这使得政府的融资工作变得更加困难。尽管贝森特(Bessent)在大幅降低借贷成本方面的能力有限,但他表示自己仍拥有“多种有效的工具”,并表示会利用一切可能的方法来控制长期债券的收益率。
All of this comes as US annual interest expense has surpassed $1 trillion for the first time on record and debt servicing costs are now bigger than the defense budget, making the job of financing the government that much trickier. Even though Bessent is limited in his ability to significantly bring down borrowing costs, he has said he still has a “big tool kit” at his disposal and signaled he will use whatever means he can to rein in long-term yields.
在财政部与一个名为“财政部借款咨询委员会”(Treasury Borrowing Advisory Committee, TBAC)的经销商及投资者团体举行季度会议时,华尔街也将再次有机会发表意见。该会议将于11月初举行,就在相关公告发布之前。虽然贝森特没有义务必须采纳该委员会的建议,但他仍可能会认为在做出进一步决策之前与这些市场参与者沟通是有益的。
Wall Street will also get another chance to weigh in when the Treasury and a group of dealers and investors, called the Treasury Borrowing Advisory Committee, or TBAC, hold their quarterly meeting in early November just ahead of the announcement. While Bessent is under no obligation to take the group’s advice, even declaring himself “the house,” he may still find it useful to want to tap into these market players before making any further decisions.
“TBAC拥有丰富的专业知识和经验,我认为财政部长应该听取他们的意见并予以考虑,”NISA投资顾问公司(NISA Investment Advisors)的首席经济学家斯蒂芬·道格拉斯(Stephen Douglass)说道;他曾担任纽约联邦储备银行(Federal Reserve Bank of New York)的工作人员。“不过,本届政府以及现任财政部长与以往的政府有所不同,他们会按照自己认为正确的方向行事。”
“There’s still a wealth of expertise and knowledge on TBAC and I think the Secretary would be well advised to listen to them and take their suggestions under consideration,” said Stephen Douglass, chief economist at NISA Investment Advisors, and a former staffer at the Federal reserve Bank of New York. “But the objective function of this administration, and this Treasury secretary is just different to previous administrations and they do what they think is right.”
早在8月份,财政部就对其指导方针进行了微调,表示官员们正在评估未来债券发行(包括固定利率债券和浮动利率债券)的潜在变化,而非债券发行量的“增加”——这为未来减少20年期和30年期债券的发行量留下了可能性。花旗集团(Citigroup Inc.)指出,周五进行的经销商调查显示长期债券的发行量可能会减少;贝森特可能会以养老基金对国债需求下降为由(这种需求下降可能是由于企业长期债券发行量增加所致),来决定减少或取消20年期债券的发行。
Back in August, the Treasury made a subtle shift to its guidance, saying officials were evaluating potential future “changes” in coupon and floating-rate note sales rather than potential “increases” — opening the door to potential cuts in supply for 20-, and 30-year bonds. Citigroup Inc. said Friday’s dealer survey may hint at less long-end issuance, and that Bessent may point to poor pension-fund Treasury demand, perhaps caused by increased long-end corporate bond issuance, as a reason to reduce or cancel the 20-year bond.
长期国债拍卖规模的缩减意味着财政部不得不进一步增加短期国债的发行量,甚至有可能推出新的债券品种,比如与担保隔夜融资利率挂钩的1年期浮动利率票据。今年第一季度,财政部官员曾向交易商征询是否应考虑发行此类债券。
Reductions in longer-dated coupon auctions means that Treasury would have to further increase bill supply or potentially introduce another product, such as a one-year floating-rate note tied to the Secured Overnight Financing Rate. In the first quarter, officials queried dealers about whether it should consider issuing such a security.
富国银行策略师上月指出,眼下正是重新探讨这一设想的良机。他们认为,此举能为货币市场基金——这类基金是短期国债的最大买家——提供另一种投资短期政府债券的渠道。
Wells Fargo & Co. strategists said last month it was an “opportune time” to revisit the idea, noting that it would offer money-market funds — the biggest buyer of T-bills — an alternative avenue to shorter-dated government debt.
持续扩大短期国债发行规模一直是财政部的债务融资策略之一,这一做法自珍妮特·耶伦任内便开始实施。不过,由于短期国债在整体国债发行量中的占比已升至22%以上,华尔街对此也心存担忧。如今美联储时隔三年再度开启加息周期,市场预计未来一年利率还将至少上调0.84个百分点,这意味着发行短期国债的成本势必会随之上升。不过也有人并不认为短期国债发行量可能增加会带来问题。
Selling ever larger amounts of bills has been a key part of the Treasury’s debt funding strategy that has carried over from the tenure of Janet Yellen. Such a reliance does worry Wall Street as the share of shorter-term bills has risen above 22%. Now that the Fed has resumed raising rates for the first time in three years, and markets expect at least another 0.84 percentage point of hiking in the next year, the cost of selling bills appears set to rise. Some don’t necessarily see a potential rise in bill issuance as a problem.
“其实完全有理由进一步增加短期国债的发行量,”SMBC日兴证券北美区首席经济学家乔·拉沃尔尼亚说道。他在本届政府上任首年曾担任贝森特的顾问。“我们可以减少长期国债的发行规模,同时与美联储协调行动——毕竟美联储也曾表示希望构建仅由短期国债构成的投资组合。这样一来,增加短期国债发行对市场的影响其实微乎其微,因为这些债券的交易价格与联邦基金利率水平相近,投资者也会乐于认购,各方都能从中获益。”
“A case could be made that you could increase bill issuance more,” said Joe Lavorgna, chief economist at SMBC Nikko Securities North America, who was a counselor to Bessent during the first year of the administration. “What we could do is get rid of some of the longer-end supply and coordinate actions with the Fed because they’ve talked about having a bills-only portfolio. So in effect, having bills wouldn’t be much of a market impact because they trade close to where fed funds and investors would take down coupon issuance and everybody would be happy.”
摩根士丹利投资管理的坎杜贾也不反对相关调整,他认为财政部应将债券回购规模翻倍,并在即将到来的国债再融资操作中缩减长期国债的拍卖规模。不过他也提醒,应避免出现更多出人意料的举措。
Morgan Stanley Investment’s Khanduja isn’t against changes and thinks Treasury should double the size of buybacks and also look at cutting long-dated bond auction sizes at the upcoming refunding. But he cautions against more surprises.
“国债的发行情况必须更加透明、更具可预测性,”他说。“在这种情况下,最不应该做的就是惹恼那些购买国债的投资者——毕竟国债的发行量已经非常庞大,而国债的收益率又充满了不确定性(即难以预测)。”
“Treasury has to be a lot more predictable,” he said. “The last thing you want to do is irritate your buyers given not only this sheer amount of debt that Treasury has to issue, and then be unpredictable on the other end.”