Chloé Meley 报道:华尔街固定收益业务在第三季度的疲软预示着欧洲银行的前景不佳,因为它们同样面临利率上升的压力。布隆伯格情报分析师菲利普·理查兹表示:“我看不出欧洲会有什么不同。”“我们在利率上升、不确定性飙升方面处境完全相同,实际上我认为,这里的情况更糟,因为法国正在发生的事情。”布隆伯格编制的估计显示,法国兴业银行(Societe Generale SA)的固定收益和货币业务收入预计将在第三季度下降10%,这是欧洲投资银行中降幅最大的。
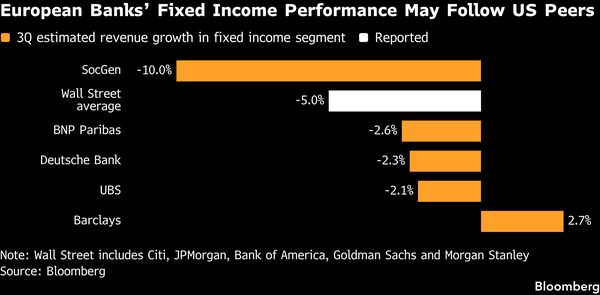
By Chloé Meley Wall Street’s fixed income weakness in the third quarter bodes badly for European banks, as they too grapple with rising interest rates“I can’t see why it’d be any different in Europe,” Bloomberg Intelligence analyst Philip Richards said. “We’re in exactly the same boat in terms of rates going up, soaring uncertainty, and actually I’d say, it’s worse over here with what’s going on in France.”Societe Generale SA’s fixed income and currencies revenue is expected to have plunged 10% in the third quarter, the biggest dip among Europe’s investment banks, Bloomberg-compiled estimates show.
德意志银行(Deutsche Bank AG)、法国巴黎银行(BNP Paribas SA)和瑞银集团(UBS Group AG)都将报告固定收益收入下降,巴克莱银行(Barclays Plc)除外。
Deutsche Bank AG, BNP Paribas SA and UBS Group AG are all set to report a fall in fixed income revenue, with Barclays Plc the exception.
这将与他们的美国同行形成呼应,后者固定收益业务的交易收入平均下降了5%,高盛集团(Goldman Sachs Group Inc.)指出“抵押贷款和信贷产品的净收入显著下降”。摩根大通(JPMorgan Chase & Co.)在超过两年的时间里首次出现固定收益、货币和大宗商品收入的年同比下降,而摩根士丹利(Morgan Stanley)则出现了近三年来第二差的季度表现。
This would echo their US peers, which saw trading revenue from their fixed income desks drop by 5% on average, with Goldman Sachs Group Inc. citing “significantly lower net revenues in mortgages and credit products.”JPMorgan Chase & Co. posted its first year-on-year decline in fixed-income, currencies and commodities revenue in more than two years while Morgan Stanley had its second-worst quarter in three years.
美国银行(Bank of America Corp.)的收入下降了17%,远高于其他银行的平均水平,是降幅最大的,超过集团平均水平的三倍多。只有花旗集团(Citigroup Inc.)逆势而上。
Bank of America Corp.’s 17% slump was by far the steepest, more than three times the group’s average. Only Citigroup Inc. bucked the trend.
由于利率居高不下,债务发行受到压制,债券交易部门面临更为严峻的形势。在美国,对美联储下一步行动的不确定性也导致一些客户不愿持有大额头寸。通胀担忧的再次升温进一步加剧了对利率前景的不确定性。
Bond trading desks face a tougher backdrop as elevated interest rates weigh on debt issuance. In the US, uncertainty over the Federal Reserve’s next moves is also making some clients reluctant to take big positions. Renewed inflation concerns have further clouded the outlook for rates.
随着对法国财政的担忧加剧,债券市场波动只会进一步恶化,法国的债务危机正唤起欧洲范围内蔓延的幽灵。这使得法国贷款机构——法国兴业银行(SocGen)、法国巴黎银行(BNP)和法国农业信贷银行(Credit Agricole SA)——成为焦点,因为它们是法国政府证券的主要持有者。
Bond market volatility is only set to worsen as worries grow over France’s finances, with the country’s debt crisis evoking the specter of contagion across Europe. That puts French lenders – SocGen, BNP and Credit Agricole SA – in the spotlight as key holders of French government securities.
而美国银行可以依靠股票业务来抵消固定收益的疲软,欧洲的贷款机构则难以做到这一点。巴克莱和法国兴业银行等未能复制华尔街第二季度股票交易的爆发式增长,这使得欧洲投行在整个第三季度可能出现普遍疲软的前景。
And while US banks can rely on equities to offset softness in fixed income, European lenders are less able to do so. The likes of Barclays and SocGen failed to replicate Wall Street’s blowout second quarter in equities trading, raising the prospect of third-quarter weakness across the board for European investment banks.
瑞银因信贷敞口有限且更侧重于货币交易——后者已成为固定收益、货币及大宗商品(FICC)中相对亮点——而被KBW分析师托马斯·哈莱特和安德鲁·斯蒂姆森在一份报告中称为“相对位置较好”。BI的理查兹认为巴克莱有潜在的突出表现,但指出实现显著超预期的空间很小。
UBS looks “relatively well positioned” given its limited credit exposure and greater weighting toward currency trading, which has emerged as a brighter spot within FICC, KBW analysts Thomas Hallett and Andrew Stimpson wrote in a note. BI’s Richards sees Barclays as a potential standout, though notes that the scope for a decisive beat is small.
巴克莱和法国巴黎银行在财报发布前的静默期内拒绝置评。法国兴业银行、德意志银行和瑞银未回应置评请求。
Barclays and BNP Paribas declined to comment in the quiet period ahead of earnings. SocGen, Deutsche Bank and UBS did not respond to a request for comment.
巴克莱将于10月22日公布业绩,随后瑞银、德意志银行和法国巴黎银行将在10月28日公布,法国兴业银行则于10月29日公布。
Barclays reports Oct. 22, followed by UBS, Deutsche Bank and BNP Paribas on Oct. 28 and SocGen on Oct. 29.
展望未来,随着全球债券抛售重新唤起对2012年主权债务危机的记忆,以及顽固的高油价激发通胀担忧,该地区最大银行的前景正日益黯淡。
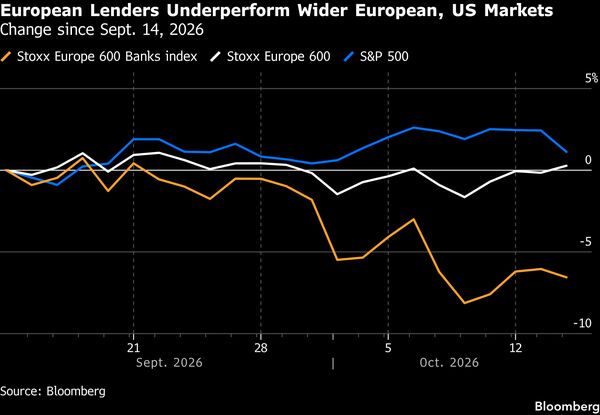
Going forward, the outlook is darkening for the region’s biggest lenders, as the global bond selloff revives memories of the 2012 sovereign debt crisis and stubbornly high oil prices stoke inflation concerns.
BI的理查兹说:“我们看到的风险无处不在:主权敞口、欧洲各国财政状况的崩塌。我当然不会说固定收益市场的困境已经触底,因为它看起来可能会持续下去。”
“We just see so many risks everywhere we look: sovereign exposures, fiscal positions collapsing across Europe,” BI’s Richards said. “I’m certainly not calling the bottom of the trouble in the fixed income market, because it looks like it might stay.”