从雷·达里奥和迈克尔·诺沃格拉茨等亿万富翁对冲基金巨头,到无数其他不为人知的市场观察者,越来越多的专业投资者相信,由于人工智能交易,股市正处于泡沫边缘。
From billionaire hedge-fund titans like Ray Dalio and Michael Novogratz to countless other market watchers who aren’t household names, more and more professional investors are convinced the stock market is flirting with bubble conditions due to the artificial intelligence trade.
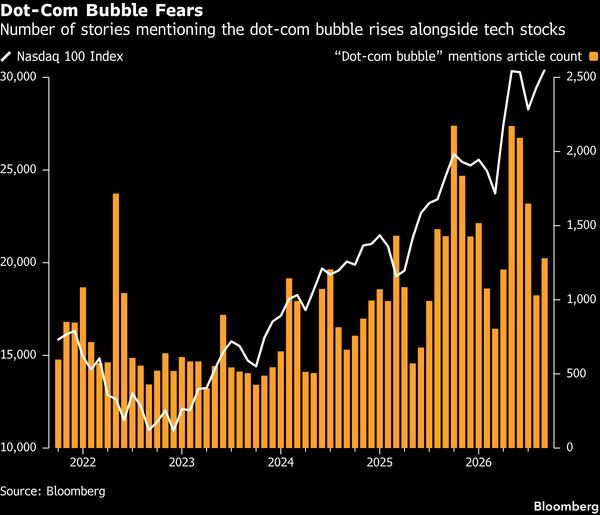
艾米丽·福加什和杰弗里·摩根报道,每当纳斯达克100指数创下新高时,新闻文章中对“互联网泡沫”的引用就会激增,本月初也是如此。所有这些焦虑或许有助于解释上周市场的抛售,该指数下跌了5.5%。
By Emily Forgash and Geoffrey Morgan References to the “dot-com bubble” in news articles soar every time the Nasdaq 100 hits fresh record highs, as it did earlier this month. All of the anxiety may help explain the selling in the market last week that sent the index down 5.5%.
然而,如果这真的是一个泡沫,华尔街投资者却发现它更难以定义。
Yet if this truly is a bubble, it’s proving more difficult for Wall Street investors to define.
以简单的市盈率为例。与四分之一世纪前互联网泡沫时期明显泡沫化的情况不同,标准普尔500指数和纳斯达克100指数等基准指数的远期市盈率今年实际上有所下降,原因是人们对巨额盈利增长的预期。事实上,在2000年市场见顶前一个月,标准普尔500指数中五大科技股的平均远期市盈率约为65倍,而如今五大科技股的远期市盈率约为23倍。
Consider the simple price-to-earnings ratio. Rather than blowing out into obviously frothy levels, as was the case during the dot-com bubble a quarter-century ago, the forward P/Es of benchmark indexes like the S&P 500 and Nasdaq 100 have actually declined this year due to expectations of blockbuster earnings growth. In fact, a month before the market peaked in 2000, the five biggest tech stocks in the S&P 500 traded at an average forward P/E of about 65, compared with around 23 for the five biggest tech stocks today.
那么,是什么让这么多人在这个市场中嗅出泡沫?如果他们是对的,又需要什么才能戳破它?市场专业人士指出了各种泡沫迹象,从天文数字般的债务水平和不可持续的盈利增长预期,到过去泡沫中基于“氛围”的模式。
So what is it about this market that has so many people spotting a bubble? And — if they’re right — what will it take to pop it? Market pros point to a variety of symptoms of frothiness, from sky-high debt levels and unsustainable earnings growth expectations to vibes-based patterns of bubbles past.
“如果你要为泡沫指出一个要素,这可能就是它:泡沫变成了公众的狂热,一种热潮,有些人变得极其富有,而任何不参与的人都会感到愚蠢并懊悔不已,”橡树资本管理公司联合主席霍华德·马克斯说。
“If you had to single out one element for a bubble, this might be it: The bubble becomes a public mania, a craze, and some people are getting ridiculously rich and anybody who’s not in it feels stupid and is kicking themselves,” said Howard Marks, co-chair of Oaktree Capital Management LP.
马克斯 — — 他曾敏锐地预见到互联网泡沫的顶部,去年还警告说他正“关注泡沫” — — 表示,“泡沫”这个词是“模糊的”,但通常要求市场在可测量的程度上达到违背投资者判断的水平,而冒险行为和情绪也会脱离现实。
Marks — who presciently called the top of the dot-com market, and warned last year that he was “on bubble watch” — said the term bubble is “amorphous” but generally requires markets to measurably reach levels that defy investor judgment, while risk-taking and sentiment also disconnect from reality.
“泡沫是非理性的狂热,是鲁莽,”他在电话中说。“盲目乐观也是一个很好的词。”在分析他目前偏好的泡沫指标时,马克斯认为我们尚未达到那个程度。虽然投资者表现出对错过科技进一步上涨的典型恐惧,但对过去泡沫的持续比较意味着他们并未对风险视而不见。至于另一个信号 — — 投资者的鲁莽行为 — — 信号也是混杂的。即使基于过去十年收益的市盈率令人担忧,但当前水平的传统市盈率看起来并不像泡沫。
“A bubble is irrational exuberance, it’s imprudence,” he said by phone. “Obliviousness is another good word.”When analyzing his preferred bubble indicators these days, Marks isn’t convinced we’re there yet. While investors are showing classic signs of fear of missing out on a further rally in tech, the constant comparisons to past bubbles mean they’re not oblivious to the risk. When it comes to another signal — investor imprudence — the signals are also mixed. Traditional price-to-earning ratios do not look bubble-like at current levels, even if they are alarming when the multiple is based on the past ten years of earnings.
投资者的鲁莽行为 在技术层面,交易员已经指出,当前市场与过去泡沫之后出现的股市崩盘存在相似之处。他们引用了诸如在创纪录的股票和债券发行期间出现的极端动量等指标。其他令人担忧的数据包括同一行业中表现最好和最差的股票之间存在广泛分化,以及市场缺乏广度。
Investor Imprudence On the technical side, traders have flagged parallels to stock market crashes that followed past bubbles. They’ve cited metrics like extreme momentum into a period of record stock and bondissuance. Other concerning data include the wide dispersion among the best and worst-performing stocks within a sector and a lack of breadth in the market.
对JonesTrading Institutional Services LLC的首席市场策略师迈克尔·奥鲁克而言,科技巨头股票市盈率的下降是合理的,考虑到他们为建设人工智能基础设施而承担的巨额债务。他指出,当公司激进杠杆时,市盈率会被压缩,这一点尤其令人担忧,因为这些投资具有循环性。
To Michael O’Rourke, chief market strategist at JonesTrading Institutional Services LLC, the decrease in the P/E ratios among Big Tech stocks is justified, given the huge amounts of debt they are taking on to build out AI infrastructure. He notes that multiples compress when companies lever up aggressively, which is especially concerning given the circularity of the investments.
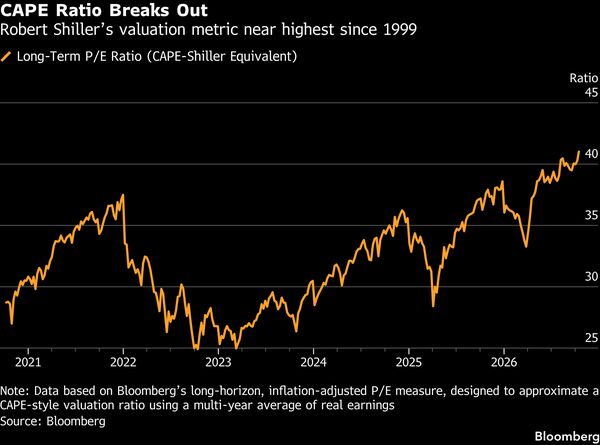
“我们已经将供应商融资提升到了全新的水平”,奥罗克在接受采访时表示,芯片制造商本身需要补贴其产品的采购,“否则这些采购根本不会发生。”一些投资者感到担忧的一个指标是周期性调整的市盈率,即CAPE,它衡量股票价格相对于过去10年通胀调整后利润的水平。该指标常被称为希勒尔市盈率(Shiller P/E),以耶鲁大学经济学家罗伯特·希勒尔命名,他在2000年3月出版了自己的书,恰逢市场达到峰值。
“We’ve taken vendor financing to whole new levels” where chipmakers themselves need to subsidize the purchases of their products, O’Rourke said in an interview. “Otherwise these purchases would not happen.”One gauge alarming some investors is the cyclically adjusted price-to-earnings, or CAPE, which measures stock prices relative to the past 10 years of inflation-adjusted profits. The metric is often called the Shiller P/E, named after Yale economist Robert Shiller who published his book in March 2000, right as the market peaked.
DataTrek Research联合创始人尼古拉斯·科拉斯称该指标为“目前正在流传的最令人恐惧的估值图表”。目前该指标显示的倍数约为41,仅低于1999年创下的44的纪录。
DataTrek Research Co-founder Nicholas Colas called the measure the “scariest valuation chart making the rounds right now.”It currently shows a multiple of about 41, just shy of a record of 44 set in 1999.
另一个令人担忧的领域是股市顶端的高度集中。如今,英伟达公司、苹果公司和微软公司——即按市值计算的美国三大公司——合计占标普500指数的约21%,而在1999年10月,几乎需要10只股票才能达到这一水平。
Another area of concern is the acute concentration at the top of the stock market. Today, Nvidia Corp., Apple Inc. and Microsoft Corp. — the three largest US companies by market value — account for about 21% of the S&P 500, while in October 1999 it took almost 10 stocks to reach that level.
尽管如此,过去10年里,纳斯达克100指数相对于标普500指数的250个百分点的超额表现仍难以忽视,即使伴随着所有这些技术警告。
Nonetheless, the 250 percentage-point outperformance of the Nasdaq 100 relative to the S&P 500 in past 10 years is hard to ignore, even with all the technical warnings.
“即使你对科技有所担忧,也无法放弃它。放弃它几乎显得愚蠢,因为它始终表现优异,”投资行业资深人士吉姆·保罗森说道,他目前撰写一份通讯。
“Even if you’re kind of worried about tech, you can’t give it up. It almost seems stupid to do it because it always outperforms,” said Jim Paulsen, an investment industry veteran who now writes a newsletter.
狂热 投资者情绪是许多泡沫观察者检查清单上的重要项目。今年,无论是在机构层面还是散户层面,投资者情绪都远未达到狂热状态。通胀居高不下、中期选举不确定性以及伊朗战争导致交易者在2026年的不同时间点采取防御姿态,而在此期间纳斯达克100指数出现了多次回调以及一次完整的10%修正。
Exuberance A major item on many bubble watchers’ checklists is investor sentiment, which has been far from exuberant both at the institution and retail level this year. Elevated inflation, midterm election uncertainty and the Iran war have caused traders to play defense at various points in 2026 as the Nasdaq 100 saw multiple pullbacks and a full 10% correction.
然而,也有迹象表明,投资者对人工智能革命所带来的市场机遇感到兴高采烈,包括通过更改公司名称来提振股票回报。即使是该繁荣最大受益者之一的领导者也指出了这种兴高采烈的氛围。博通公司(Broadcom Inc.)首席执行官霍克·谭(Hock Tan)表示,人工智能繁荣吸引了那些“对自己在投资什么一无所知”的投资者,他们表现得就像在赌场一样。
Still, there are signs that investors are feeling euphoric about the market opportunities the AI revolution presents, including corporate name changes that juice stock returns. Even the leader of one of the biggest beneficiaries of the boom has called out the euphoric vibes. Broadcom Inc.’s Chief Executive Officer Hock Tan said the AI boom has attracted investors who “have no clue what they are investing in” and are behaving like they’re in a casino.
就轶事而言,泡沫的另一个常被引用的警告信号是,随机遇到服务人员时会谈到投资。约瑟夫·肯尼迪(Joseph Kennedy)曾被广泛引用地说,他在1929年知道该卖出的时候,是因为他的擦鞋男孩开始提供股票建议。
Anecdotally, at least, another oft-cited warning sign of a bubble is when random encounters with service workers result in discussions about investments. Joseph Kennedy is famously quoted as saying he knew it was time to sell when his shoeshine boy was dishing out stock tips in 1929.
类似的近期遭遇被CFRA首席投资策略师萨姆·斯托瓦尔(Sam Stovall)提及,他说他在与一名在纽约报摊工作的男子交谈时,被要求打印出与人工智能相关的公司——英特尔公司(Intel Corp.)和思科系统公司(Cisco Systems Inc.)的股票报告。
A similar recent encounter was noted by Sam Stovall, CFRA’s chief investment strategist, who said he was asked to print out stock reports on AI-related companies Intel Corp. and Cisco Systems Inc. while talking with a man running a newsstand in New York.
盲目乐观 无论哪种警告信号被重视,华尔街关于泡沫的讨论正在变得越来越常见,因为当前的牛市已经进入第五个年头。在第二季度财报季期间,公司高管和分析师在15次不同的投资者电话会议中讨论了与2008年全球金融危机以及2000年科技泡沫的相似之处,其中包括高盛集团公司(Goldman Sachs Group Inc.)、模拟器件公司(Analog Devices Inc.)和黑石公司(Blackstone Inc.),彭博情报(Bloomberg Intelligence)编纂的数据显示。
Obliviousness Regardless of which warning sign is being heeded, bubble talk on Wall Street is becoming more common as the current bull market enters its fifth year. During the second-quarter earnings season, corporate executives and analysts discussed parallels to the 2008 global financial crisis and the tech bubble during 15 different investor calls, including Goldman Sachs Group Inc., Analog Devices Inc. and Blackstone Inc., data compiled by Bloomberg Intelligence show.
与此同时,利率已飙升至可能对之前市场宠儿构成麻烦的水平。核心微波公司(CoreWeave Inc.)的股价在1月至5月初之间几乎翻了一倍,但上周的暴跌使其年内涨幅回落,因为其债券收益率正在攀升。
Meanwhile, interest rates have spiked to levels that can spell trouble for previous market darlings. CoreWeave Inc. shares had nearly doubled in price between January and early May before last week’s rout sent it down year-to-date as its bond yields climb.
“通常是信贷市场出了什么问题,才会让周期走到尽头,”雷诺兹策略公司(Reynolds Strategy LLC)首席市场策略师布莱恩·雷诺兹(Brian Reynolds)说。“当人们在信贷市场面临无法满足的追缴保证金通知时,真正的麻烦才刚刚开始。”当人们相信技术能改变世界,并将这种信念转化为股市的强烈热情时,泡沫也会破裂。投资者“会变得过度自信,然后支付过高的价格。这就是泡沫思维的真正含义。并非说人工智能不会改变世界,”琼斯交易公司(JonesTrading)的奥罗克(O'Rourke)说。
“Typically it’s something that goes wrong in the credit market that brings the cycle to an end,” said Brian Reynolds, chief market strategist at Reynolds Strategy LLC. “It’s when people get margin calls they can’t meet in the credit market, that’s when the real trouble starts.”Bubbles also pop when beliefs that technology can change the world translate to intense enthusiasm in the stock market. Investors “get overconfident and then they overpay. And that’s really what bubble thinking is. It’s not that AI is not going to change the world,” JonesTrading’s O’Rourke said.
在以往的例子中,包括互联网的兴起,该技术取得了巨大成功并产生了变革性影响,股市涨幅通过首次公开募股(IPO)和股票发行导致股权供应大幅增加。但当盈利令人失望且利率上升时,集中涨幅开始逆转。
In previous examples, including the rise of the Internet, the technology was wildly successful and transformative, and stock market gains led to massive increases in equity supply through IPOs and share offerings. But when earnings disappointed and interest rates rose, concentrated gains began to reverse.
然而,马克斯(Marks)目前在市场上看不到的一个明显迹象是,投资者对风险的“无视”。事实上,华尔街的每个人似乎都在谈论可能出现的泡沫。
Still, one telltale sign that Marks doesn’t currently see in the market is investor “obliviousness” to the risks. Indeed, everyone on Wall Street seems to be talking about a possible bubble.
“如果足够多的人谨慎地怀疑某个领域是否存在泡沫,那么认为如果它是泡沫,那很可能已经受到抑制,这是完全合理的,”马克斯说。
“If enough people are cautiously wondering if there’s a bubble in a given area, then it makes absolute sense to think that if it is a bubble, it’s probably restrained,” Marks said.