如果欧洲的证券公司在该地区的交易时间表加快之前未能解决交易结算效率低下的问题,它们可能会面临每天数百万欧元的额外罚款。
European securities firms could face millions of euros in additional daily penalties if they fail to fix settlement inefficiencies before the region’s trading timetable quickens.
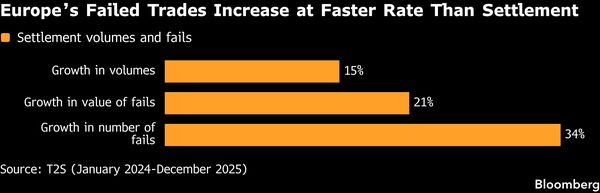
根据 Depository Trust & Clearing Corp. 与研究机构 The ValueExchange 周三发布的一份报告,在 2024 年 1 月至 2025 年 12 月期间,欧洲未能完成的交易数量的增长速度是交易总量的两倍。在未能完成的交易中,其中一方未能在规定的时间内向另一方交付证券或支付款项。
The volume of failed trades in Europe grew twice as fast as the increase in transactions in the January 2024 to December 2025 period, Depository Trust & Clearing Corp. and research firm The ValueExchange said in a report Wednesday. In a failed trade, one side doesn’t deliver securities or payment to the other in the required time.
欧盟、英国和瑞士计划从 2027 年 10 月 11 日起将股票和债券的标准结算周期从两天缩短至一天。美国早在 2024 年 5 月就已经实施了所谓的“T+1”结算制度(即交易完成后第二天完成结算)。
The European Union, the UK and Switzerland are shortening the standard settlement cycle for stocks and bonds to one day from two on Oct. 11, 2027. The US already made the transition to so-called T+1 settlement in May 2024.
报告指出,这一挑战在欧洲尤为严峻:欧洲的证券结算系统由 31 个市场中的 19 家中央对手方和 40 家中央证券存管机构组成,结构极其复杂。
The challenge is particularly acute in Europe, where securities settlement resembles “a complex spider’s web” of 19 central counterparties and 40 central securities depositories across 31 markets, the report says.
报告估计,如果新的结算制度立即生效,欧洲的证券公司将面临每天 1700 万欧元(约合 1910 万美元)的额外罚款;这还不包括因交易失败或延迟而产生的现有每日费用(4700 万欧元)。
The report estimated that European firms would risk €17 million ($19.1 million) in additional daily fines if the new settlement regime was imposed today, adding to the existing €47 million in daily costs from failed or late trades.
欧洲的术后交易规则比美国的制度更具惩罚性:对于那些导致交易失败或延迟的参与者,会处以每日罚款。在美国,清算机构必须迅速平仓某些未完成的股票交易;同时,还可以通过清算系统收取相关费用。
Europe’s post-trade rules are more explicitly punitive than the US system, imposing daily cash penalties on participants responsible for failed or late trades. In the US, clearing firms must quickly close out certain failed equity positions, while financial charges can also be imposed through the clearing system.
报告还发现,大约 68% 的欧洲证券公司仍在依赖某种程度的手动交易匹配机制。许多人认为,提高自动化程度是满足更严格的结算期限要求的关键。
On top of this, about 68% of firms continue to rely on some level of manual trade matching, the report found. Many see a move to greater automation as key to meeting the tighter settlement deadline.
“手动操作中的错误以及繁琐的流程已经不再适用了,”Helaba Invest 公司的交易服务主管 Samuel Choudhury 在上周于 Antibes 举行的行业会议上表示。
“Manual hiccups and stressful processes will not work anymore,” said Samuel Choudhury, head of transaction services at Helaba Invest, at an industry conference in Antibes last week.
“如果‘T+1’规则未能得到遵守,就会直接导致经济损失。这意味着优秀交易员所获得的所有利润都可能被你的中间机构(如经纪公司)所剥夺,”他补充道。
“If T+1 is not fulfilled, it directly costs money. This means that all profits a good trader can gain, your middle office can destroy,” he added.
在英国,金融行为监管局(Financial Conduct Authority)已经警告那些在准备工作中仍滞后于其他公司的企业,称这些企业将面临“严格的监管”以及可能的干预措施。
In the UK, the Financial Conduct Authority has warned of “uncomfortable” supervision and possible interventions for firms that continue to lag in preparedness.
由于结算过程依赖于一系列相互依存的交易,任何一个环节的薄弱都会影响整个流程,从而导致其他环节出现故障或流动性压力。
Because settlement depends on a web of interdependent transactions, one weak link can undermine the whole process, creating failures and liquidity pressures elsewhere in the chain.
“这将是英国和欧盟市场基础设施一个世纪以来最重要的改革之一,”英国财政部经济事务大臣露西·里格比(Lucy Rigby)在上周举行的纪念活动上表示。“改革的成功与否取决于所有相关方的共同准备程度。”
“This will represent one of the most important reforms to the UK and EU market infrastructure in a generation,” said Lucy Rigby, economic secretary to HM Treasury, at an event marking the one-year countdown last week. “Success depends on collective readiness.”