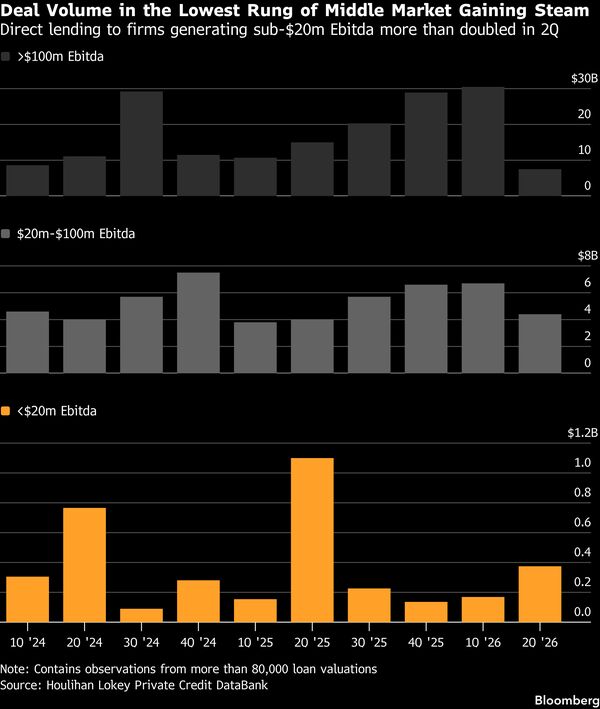
由于直接贷款业务遭遇了三年来最糟糕的业绩表现,一些私人信贷机构开始将业务重心向下延伸(即转向那些规模更小的企业)。
With direct lending deals chalking up their worst quarter in more than three years, some private credit firms are moving downmarket.
那些原本可能被大型直接贷款机构忽视的企业(尤其是年收入低于2000万美元的公司)如今也成为了竞争的焦点,而借款人则在这些竞争中占据了上风。
Business that might have once escaped the attention of large direct lenders — loans to companies with earnings less than $20 million — is suddenly becoming fiercely competitive. And borrowers are coming out on top.
以EOS Corrugated为例:这是一家为瓦楞纸板制造商生产工具和零件的公司,目前由其私募股权所有者Sagard持有控股权。据知情人士透露,Barings和CVC Credit Partners等金融机构已准备为其收购提供融资支持,贷款金额达到了该公司年收入(约2500万欧元/2800万美元)的5.5倍。
Take EOS Corrugated, which makes tools and parts for corrugated cardboard manufacturers and is being sold by its private equity owner Sagard. Barings and CVC Credit Partners are among the lenders ready to finance its acquisition with a debt package amounting to 5.5 times a measure of its annual earnings of about €25 million ($28 million), according to people with knowledge of the matter.
这些贷款的利率可能仅比基准利率高出475个基点(即0.475%)。不过,这样的贷款条件对于那些历史较短、抵御经营风险或经济衰退能力较弱的小型企业来说并不常见。从盈利能力来看,EOS属于典型借款人的“低端”群体。Barings的代表拒绝置评,CVC也未立即回应相关询问。
The loan could be priced to yield as little as 475 basis points above benchmark rates, said the people, asking not to be identified as the details are private. The leverage levels and terms on offer are atypical for smaller companies with shorter track records and thinner cushions to absorb operational setbacks or economic downturns. For both asset managers, EOS is at the lower end of a typical borrower, based on earnings. A representative for Barings declined to comment, while CVC didn’t immediately respond to requests for comment.
Wells Fargo & Co.的分析师将这一趋势比作棒球比赛中的“小打小闹”——贷款机构选择在利率范围的最低端提供贷款,追求的是小幅度的收益增长,而非巨额利润。根据该行本月对美国直接贷款市场的调查,第三季度私人信贷业务中,面向中小型企业及核心中型企业的贷款占比达到了三分之二。
Wells Fargo & Co. strategists liken the trend to playing “small ball” in baseball, with lenders sticking to the very bottom of their range and looking for incremental wins rather than home runs. Deals to lower- and core middle-market borrowers accounted for two-thirds of private credit in the third quarter, according to the bank’s survey of US direct lending this month.
随着整体交易量的急剧下降,这种情况正在发生。据摩根大通的分析师称,第三季度的直接贷款总额为389亿美元,降至2023年第二季度以来的最低水平。分析师们在本周的一份报告中指出,9月份的直接贷款额仅为104亿美元,较去年同期下降了66%,远低于近期的月平均贷款额(约230亿美元)。
That’s happening as overall deal flow slows sharply. At $38.9 billion, direct lending volumes in the third quarter dropped to their lowest quarterly amount since the second quarter of 2023, according to analysts from JPMorgan Chase & Co. September’s $10.4 billion of direct loans represented a decline of 66% from a year ago, and was far below the recent average monthly pace of about $23 billion, the analysts wrote in a note this week.
在过去的这一年里,私人信贷市场的赎回规模创下了历史新高;同时,人们对承销标准以及那些受到人工智能技术冲击的软件企业的风险状况也产生了疑虑。因此,许多资产管理机构开始关注那些陷入困境的基金,并且可用于投资的资金也减少了。这使得华尔街银行在与直接贷款机构的长期竞争中重新获得了优势。
In a year marked by record redemptions from the $1.8 trillion private credit market, as well as questions about underwriting standards and exposure to software businesses threatened by AI disruption, a number of asset managers are tending to troubled funds and have less capital to deploy. That’s allowed Wall Street banks to wrest back some momentum in their long-running battle against direct lenders.
根据摩根大通的数据,今年迄今为止,已有229亿美元的私人信贷贷款被重新转化为银行贷款;而反向转化(即银行贷款转化为私人信贷贷款)的金额仅为92亿美元。这种情况很不寻常,因为通常在市场波动期间,直接贷款机构会趁机扩大市场份额——就像2022年利率飙升时它们所做的那样。
So far this year, $22.9 billion of loans have been refinanced from private credit into bank loans, compared with the $9.2 billion moving the other way, according to JPMorgan. That’s unusual because direct lenders have typically gained ground during periods of volatility, stepping in when banks retreat — as they did when interest rates surged in 2022.
再加上大型杠杆收购交易持续缺席,私人信贷机构自然会抓住一切机会寻找新的投资机会。 HarbourVest Partners的董事总经理Greg Ciesielski表示:“我们确实看到一些大型资产管理机构开始关注较小的投资项目,以便将更多资金投入到市场中。”该机构管理的私人市场资产规模超过1600亿美元。
Add to that environment the persistent absence of large-cap leveraged buyouts, and it’s not a surprise that private credit firms are hunting for deals wherever there’s an opportunity. “We’re definitely seeing larger managers looking at smaller deals to put more money to work,” said Greg Ciesielski, managing director at HarbourVest Partners, which manages more than $160 billion in private markets assets.
在欧洲,也出现了一些大型资产管理机构向小型企业提供贷款的案例。例如,9月份Ares Management Corp.支持了对瑞典工程公司Metalock的收购,Golub Capital为Atoz Services提供了债务融资;BlackRock Inc.则在6月份为法国医疗公司iLC提供了再融资支持。
In Europe, there have been a few recent examples of larger managers lending to smaller businesses. In September, Ares Management Corp. backed the buyout of Swedish engineering company Metalock and Golub Capital provided a debt package for Atoz Services. BlackRock Inc. refinanced French healthcare company iLC in June.
当然,除了直接提供贷款之外,像黑石集团(Blackstone Inc.)和阿波罗全球管理公司(Apollo Global Management)这样的私人信贷机构仍在为那些需要融资用于人工智能建设的优质企业安排价值数十亿美元的交易。
To be sure, beyond direct lending, private credit firms such as Blackstone Inc. and Apollo Global Management are still arranging multi-billion dollar transactions for higher-grade borrowers financing their AI buildout.
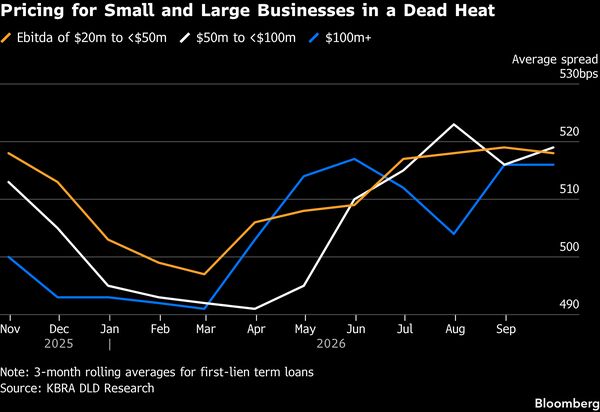
然而,对于规模较小的交易而言,激烈的竞争使得这些小型企业与大型企业之间的借贷成本趋于一致。根据 KBRA DLD 的数据,那些年收入(未扣除利息、税费、折旧及摊销前费用)低于 2000 万美元的企业,现在所支付的借贷成本与年收入超过 1 亿美元的企业大致相同。
But the intense competition for smaller-scale deals has put the businesses on equal footing with their larger counterparts when it comes to borrowing costs. Businesses with less than $20 million in earnings before interest, taxes, depreciation and amortization now pay roughly the same amount as those businesses that generate more than $100 million, according to data from KBRA DLD.
“由于利率上升,企业的资金成本也随之增加,因此企业的退出速度变慢,整体交易量也有所下降,”TIAA 的资产管理公司 Nueen 旗下的 Churchill Asset Management 副董事长兰迪·施维默(Randy Schwimmer)表示。“我将其称为‘零重力时期’——在这个时期,所有企业的竞争环境都变得异常激烈、难以预测。”
“With interest rates higher, increasing the cost of capital, exits are slow and overall deal flow is generally down,” said Randy Schwimmer, vice chairman at Churchill Asset Management, an affiliate of Nuveen, the asset manager of TIAA. “I’ve been calling it the period of zero gravity.”