在收购 Coterra Energy Inc. 并组建成为全球最大的页岩油生产商之一仅五个月后,Devon Energy Corp. 又面临着激进投资者的压力,要求其出售核心资产或进行整体出售。这引发了关于潜在买家的各种猜测。
Just five months after buying Coterra Energy Inc. to create one of the world’s biggest shale producers, Devon Energy Corp. is under pressure from activist investors to offload key assets or sell itself. That’s fanning speculation about potential buyers.
Devon 的首席执行官 Clay Gaspar 于今年 5 月完成了与 Coterra 的收购交易,使得这家总市值达 550 亿美元的新公司成为西德克萨斯州和新墨西哥州二叠纪盆地的行业巨头——该地区是美国最大的油田。他承诺会整合 Devon 的资产结构,并于本月宣布将公司在南德克萨斯州 Eagle Ford 盆地的钻井资产以约 42 亿美元的价格出售给 Crescent Energy Co.。
Devon Chief Executive Officer Clay Gaspar closed the deal with Coterra in May, making the $55 billion combined company a powerhouse in the Permian Basin of West Texas and New Mexico, the largest US oil field. He pledged to streamline Devon’s holdings and this month announced an agreement to sell its drilling portfolio in the Eagle Ford basin of South Texas to Crescent Energy Co. for about $4.2 billion.
然而,Kimmeridge Energy Management Co. 认为 Devon 需要进一步剥离更多资产。尽管今年高油价推动 Devon 的股价上涨了超过 30%,但这一观点依然存在。据 CNBC 报道,TOMS Capital Investment Management LP 曾呼吁在完成 Eagle Ford 盆地的资产出售之前直接出售整个 Devon 公司;截至目前,该投资者并未改变这一立场。
But Kimmeridge Energy Management Co. says Devon needs to divest more assets — a push that comes even as high oil prices have propelled the shale producer’s shares to a gain of more than 30% so far this year. TOMS Capital Investment Management LP called for an outright sale of the company before the Eagle Ford deal, CNBC reported, and the investor has so far given no indication that it’s backing away from that stance.
虽然出售 Eagle Ford 盆地的资产对 Devon 来说是一个积极的举措,但“这还不足以充分释放其在二叠纪盆地中的竞争优势。”Kimmeridge 的管理合伙人 Mark Viviano 在一份电子邮件声明中表示:“我们预计 Devon 应该再出售价值约 100 亿美元的非核心资产;否则,他们应该将整个公司出售给愿意收购的公司。”TOMS 的代表拒绝置评,Devon 的发言人也没有回应任何评论请求。
While the Eagle Ford sale is a positive step for Devon, it’s “insufficient to unlock value in their preeminent Permian position. We would expect them to sell another $10 billion of non-core assets,” Mark Viviano, a managing partner at Kimmeridge, said in an emailed statement. “Absent that, they should sell the company to someone who will.”A representative for TOMS declined to comment.
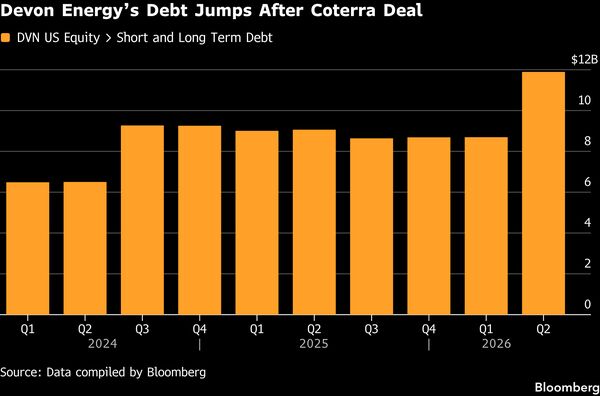
德文(Devon)是几家希望出售资产以偿还债务的页岩油公司之一。这些债务是在大约三年前开始的行业整合浪潮中累积起来的。随着美国石油产量在经历了十多年的快速增长后开始放缓,各大石油公司纷纷合并,以便控制那些剩余的优质资源。与此同时,投资者则敦促这些企业控制成本并提高盈利能力。
A spokesperson for Devon didn’t respond to requests for comment, and the company has not publicly addressed the activist investors’ calls for the driller to sell itself. Devon is among several shale companies looking to sell assets to pay down debt incurred during a massive wave of industry consolidation that kicked off about three years ago.
“我们认为,收购埃格尔福特(Eagle Ford)只是第一步,而非最终目标,”能源分析师蒂姆·施奈德(Timm Schneider)在给客户的报告中指出。
As US oil production growth slows after more than a decade of breakneck expansion, operators are merging so they can lock down the best remaining spots.
根据分析师和投资者的分析,以下是一些可能收购德文公司的潜在买家:
Investors, meanwhile, are urging the producers to keep costs under control and boost returns.
市场价值: 550亿美元
现金储备: 4.62亿美元
“We believe the Eagle Ford was step one, not the endgame,” energy analyst Timm Schneider said in a note to clients.
净债务与息税折旧摊销前利润(EBITDA)的比率: 1.88
Here are a few potential Devon acquirers, according to analysts and investors.
主要资产: 二叠纪盆地(Permian Basin)
Market value: $55 billion Cash on hand: $462 million Net debt to EBITDA: 1.88 US Assets: Permian Basin Rationale: Diamondback has a commanding position in the eastern end of the Permian, known as the Midland Basin.
收购理由: Diamondback 在二叠纪盆地的东部地区(即米德兰盆地,Midland Basin)占据着主导地位。如果收购德文公司,它将在二叠纪盆地的西部地区(特拉华盆地,Delaware Basin)也拥有类似的业务布局。Diamondback 最近提高了市场对其并购能力的预期,承诺如果关键股东的持股比例被稀释,他们仍能保留在董事会中的席位;这种情况可能发生在公司通过发行股票来完成大型交易时。
Acquiring Devon would give it a similar footprint on the Delaware side to the west. Diamondback raised M&A expectations recently by guaranteeing key shareholders board seats if their stake were diluted, something that may occur if the company issued stock for a big deal.
Truist Financial Corp. 的分析师加布·达乌德(Gabe Daoud)表示,合并后的企业将成为“二叠纪盆地的巨头”,每日石油产量将达到约200万桶——这一产量水平可与埃克森美孚公司(ExxonMobil Holdings Corp.)在该盆地的产量相媲美。
Gabe Daoud, an analyst at Truist Financial Corp., said the combined entity would be a “Permian powerhouse” producing roughly 2 million barrels of oil equivalent a day — a level that would rival ExxonMobil Holdings Corp.’s output from the basin.
缺点: 对于Diamondback 来说,收购德文公司将是一项具有较大财务压力的举措。该公司长期以来一直向投资者宣传自己是一家专注于二叠纪盆地业务的石油公司;但如果完成这笔交易,这一定位将会改变。如此大规模的收购可能意味着Diamondback 必须出售其在其他业务中获得的资产,包括德文公司在马塞勒斯盆地(Marcellus Basin)的天然气业务。
Con: Acquiring Devon would be more of a financial stretch for Diamondback than for some of its larger rivals. Diamondback has long pitched itself to investors as a Permian-only operator, but that would change with a deal for Devon. A purchase of that size would likely mean Diamondback would have to sell off a variety of assets gained in the acquisition, including Devon’s natural gas business in the Marcellus.
Diamondback 的相关负责人并未回复我们的咨询请求。
A representative for Diamondback didn’t return messages seeking comment.
手头现金:77亿美元。美国资产:二叠纪盆地、鹰滩、巴肯、粉河盆地、阿拉斯加、路易斯安那州南部。理由:康菲石油的资产将在二叠纪盆地和北达科他州威利斯顿页岩盆地区域与戴文能源的资产重叠,而这家规模更大的公司将具备良好条件来运营马塞勒斯天然气资产。该公司此前已表现出对达成大规模页岩交易的兴趣,尽管其在本十年早些时候进行那些收购时油价更低。
Cash on hand: $7.7 billion US Assets: Permian, Eagle Ford, Bakken, Powder River, Alaska, southern Louisiana Rationale: ConocoPhillips’ assets would overlap with Devon’s in the Permian and in North Dakota’s Williston shale basin, while the larger company would be well-placed to handle Marcellus natural gas. The company has previously shown an appetite for striking sizeable shale deals, although oil prices were lower when it made those acquisitions earlier this decade.
不利因素:上月被提升为首席执行官的安迪·奥布莱恩已承诺延续前任领导人瑞安·兰斯的资本纪律原则,因此如此大规模的收购可能会与这一目标相悖。康菲石油的一位发言人拒绝就潜在收购置评。
Cons: Andy O’Brien, who was elevated to the role of CEO last month, has pledged to continue former leader Ryan Lance’s mantra of capital discipline, so a purchase this large could run counter to that goal. A ConocoPhillips spokesman declined to comment on potential acquisitions.
美国资产:二叠纪盆地、巴肯、丹佛-朱尔斯堡盆地、墨西哥湾。理由:施耐德表示,雪佛龙拥有最强的财务能力,可以20%的溢价收购戴文能源,并在25年的储量生命周期内实现超过8%的年回报率,前提是收购后出售各种其他资产。该公司已在二叠纪盆地拥有庞大的资产组合,与戴文能源存在大量重叠。
US Assets: Permian, Bakken, Denver-Julesburg Basin, Gulf of Mexico Rationale: Chevron has the best financial capacity to buy Devon for a 20% premium and generate annual returns greater than 8% over a 25-year inventory life, assuming various other assets get sold after the acquisition, according to Schneider. It has a vast Permian Basin position already, providing substantial overlap with Devon.
不利因素:雪佛龙最近已放缓其二叠纪盆地的增长,使其进入约每日100万桶油当量的平台期,目的是牺牲产量来提升利润。收购戴文能源似乎与这一战略相悖。雪佛龙的一位发言人拒绝置评。
Cons: Chevron has recently slowed its Permian growth to a plateau of about 1 million barrels of oil equivalent a day with the intent of boosting profits at the expense of production. Buying Devon would appear to run contrary to this strategy. A spokesperson for Chevron declined to comment.
美国资产:二叠纪盆地、鹰滩、粉河盆地、威利斯顿、尤蒂卡、多拉多。理由:梅利乌斯研究公司的分析师詹姆斯·韦斯特在接受采访时表示,EOG被视为页岩行业最强的作业者,可能在管理戴文能源的钻井资产组合方面证明有效。EOG庞大的资产组合也可能与戴文能源的多盆地资产很好地搭配。
US Assets: Permian, Eagle Ford, Powder River, Williston, Utica, Dorado Rationale: EOG is seen as the strongest operator in the shale industry and could prove effective at managing Devon’s drilling portfolio, James West, an analyst at Melius Research, said in an interview. EOG’s vast holdings could also pair well with Devon’s multi-basin assets.
不利因素:EOG对进行大规模收购也非常挑剔,反而更倾向于通过小型交易和自身发现带来的有机增长来扩张。
Cons: EOG is also very selective about doing large acquisitions, preferring instead to expand through small deals and organic growth from its own discoveries.
美国资产:俄克拉何马州的二叠纪盆地、巴肯页岩、伍德福德页岩,以及海恩斯维尔、马塞勒斯、尤蒂卡。
US Assets: Permian, Bakken, Woodford Shale in Oklahoma, Haynesville, Marcellus, Utica Rationale: Exxon has the most significant opportunity for cost savings by buying Devon and has the highest-value stock among potential buyers, making it easier to execute a deal, according to Schneider.
理由:施奈德表示,埃克森美孚通过收购德文能源拥有最大的成本节约机会,并且在潜在买家中拥有价值最高的股票,这使得交易更容易执行。这家石油巨头在新墨西哥州还拥有连片的业务,该州拥有二叠纪盆地一些产量最高的油田。
The oil major also has contiguous operations in New Mexico, which has some of the Permian’s most productive fields.
弊端:施奈德表示,埃克森美孚将不得不出售四个盆地的资产才能使交易可行。这家石油巨头还必须决定如何在全球一系列资产和机会之间分配资本,这意味着潜在交易必须达到很高的门槛。埃克森美孚正在考虑投资阿塞拜疆的页岩油生产、莫桑比克的液化天然气,并正在特立尼达和多巴哥、东地中海及其他地区勘探石油。
Cons: Exxon would have to sell assets in four basins to make the deal work, Schneider said. The oil giant also has to decide how to allocate capital across a global suite of assets and opportunities, meaning potential deals have to clear a high bar. ExxonMobil is looking at investing in shale production in Azerbaijan, liquefied natural gas in Mozambique and is exploring for oil in Trinidad & Tobago, the Eastern Mediterranean and elsewhere.