对于疯狂的富有亚洲人来说,AI 相关股票的抛售带来了新的交易机会。波动性已成为他们的朋友。
For crazy rich Asians, a selloff in AI-related stocks presents new trading opportunities. Volatility has become their friend.
您是否愿意为 CoreWeave Inc. 的股东提供保护?这家数据中心运营商因其信用风险而受到审视。随着这家美国公司的市值从 10 月初的高点暴跌逾三分之一,香港的私人财富管理师一直在兜售诱人的结构性产品。
Would you be willing to provide protection for shareholders of CoreWeave Inc., the data-center operator under scrutiny over its credit risks? Hong Kong’s private wealth managers have been dangling seductive structured products as the US-based firm’s market value tumbled by more than a third from its early October high.
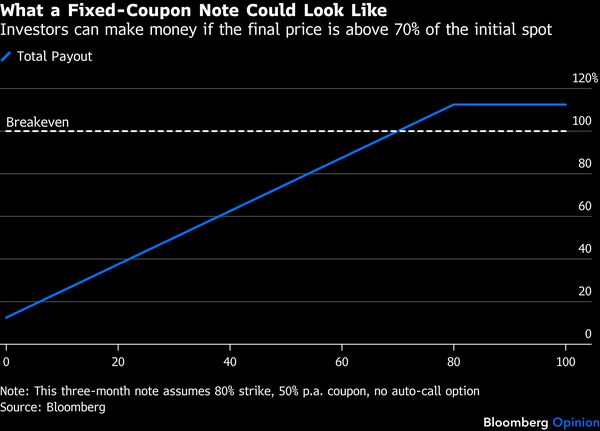
请看这款为期三个月、固定票息的票据(FCN),其年化票息率超过 50%,行权价为 80%。运作方式如下:首先您给银行 25 万美元。如果 CoreWeave 的股价在到期时跌幅不超过 20%,您获胜;您将拿回本金,外加利息。然而,如果三个月后股价暴跌,您将亏损,因为您已同意按今日价格的 80% 买入股份。还有一种中间结果,即股价上涨时发生。从第二个月起,银行将有权提前赎回票据并归还您的本金。您可以保留迄今赚取的利息,但这趟旅程就此结束。
Consider this three-month, fixed-coupon note, or FCN, that pays an annualized coupon of more than 50% and a strike price of 80%. Here’s now it works: First you give the bank $250,000. You win if CoreWeave’s stock doesn’t drop by more than 20% at maturity; you will get your money back, plus interest. You lose, however, if the stock crashes in three months’ time, because you have agreed to purchase the shares at 80% of today’s price. There’s also an intermediate outcome, which happens when the stock goes up. Starting in the second month, the bank will be able redeem the note early and return your principal. You get to keep the interest earned so far, but the ride is over.
这绝非市面上唯一的高收益 FCN。其他由散户驱动的 AI 公司,如甲骨文公司、Bloom Energy Corp. 和美满电子科技公司,经常成为结构性产品的核心标的。那款名字绕口的中银国际 SK 海力士每日最大 2 倍杠杆产品——一种单一股票交易所交易基金,其超额再平衡加剧了 7 月韩国综合股价指数的暴跌——也是另一款热门玩法。根据彭博社观点看到的一份条款表,私人银行巨头瑞银集团近期售出的一款行权价 65%、可赎回价 110%(即证券被回购的价格)的 FCN,其年化利息支付超过 40%。
This is by no means the only high-yield FCN in town. Other retail-driven AI companies, such as Oracle Corp., Bloom Energy Corp. and Marvell Technology Inc., are frequently at the heart of structured products. The mouthful that is the CSOP SK Hynix Daily Max 2x Leveraged Product, a single-stock exchange-traded-fund whose outsized rebalancing exacerbated the Kospi’s rout in July, is another popular play. An FCN with a 65% strike price and 110% callable price (what the security would be bought back at) recently sold by private banking giant UBS Group AG, has an annualized interest payment of more than 40%, according to a term sheet seen by Bloomberg Opinion.
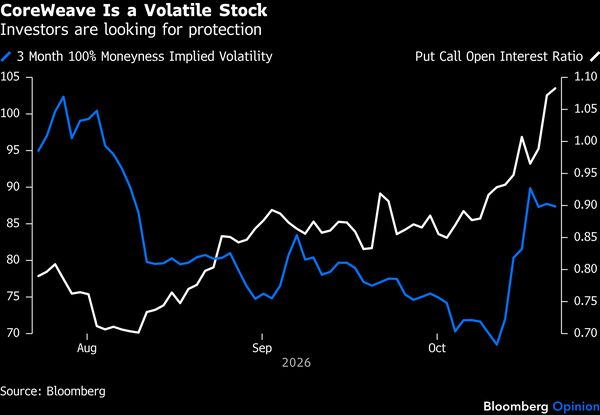
这些巨额收益之所以成为可能,是因为市场波动加剧,且人们担心 AI 泡沫会破裂。当你购买 FCN 时,本质上是在卖出一份看跌期权,充当保险提供者。随着 AI 交易陷入停滞,全球投资者——尤其是对冲基金——自然会寻求下行保护,从而推高了期权费。正如科技债券的保险成本在上升,这些票据的票息也在随之走高。
These massive yields are only possible because of heightened market volatility and fear that the AI bubble would burst. When you buy an FCN, you are essentially writing a put option and acting as an insurance provider. As the AI trade splutters, global investors — hedge funds, in particular — naturally look for downside protection, thereby bidding up the premium. Just as the costs of insuring tech bonds are drifting higher, so are the coupons on these notes.
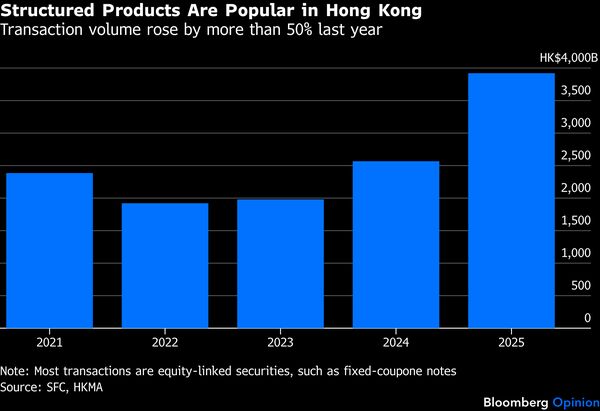
FCN 在香港的私人财富管理客户中很受欢迎。就像单只股票杠杆 ETF 一样,它们比期权更容易理解和交易。据该市金融监管机构称,去年股票挂钩产品的销售额激增 58%,达到 2.7 万亿港元(约 3450 亿美元)。今年也没有任何放缓的迹象。
FCNs are popular with Hong Kong’s private wealth clients. Just like single-stock leveraged ETFs, they are easier to understand and trade than options. Sales of equity-linked products rose by 58% to HK$2.7 trillion ($345 billion) last year, according to the city’s financial regulators. There’s no sign of any slowdown this year, either.
然而,我不禁怀疑,香港这些渴望高收益的投资者是否真正了解这种产品。FCN 内嵌了一种有利于银行的不对称性。如果股票表现良好,银行可以在仅仅一个月后行使赎回权,终止票据。但如果股票表现不佳,合同会强迫你熬满整整三个月,最后把毫无价值的股票交到你手上。你能承受这种精神压力吗?或许还要经历许多个失眠之夜,眼睁睁看着美国市场剧烈震荡?
I wonder if Hong Kong’s yield-hungry investors really understand this product, however. Embedded in an FCN is an asymmetry in the bank’s favor. If the stock is doing well, the bank can call and kill the note after just one month. But if the stock is performing badly, the contract forces you to ride out the full three months before handing you the worthless shares. Can you handle the mental stress, and perhaps many sleepless nights watching the US market gyrate?
根据彭博汇编的数据,自 CoreWeave 于 2025 年 3 月上市以来,大约每三天中就有一天,其股价在随后三个月内下跌了至少 20%。同样,对于在港上市的 SK 海力士杠杆 ETF,约 30% 的可计算交易日,其三个月远期回报率为 -35% 或更差。你的 FCN 表现不佳的可能性非常真实。
Since CoreWeave’s public listing in March 2025, roughly one in three days led to a loss in the stock of at least 20% over the following three months, according to data compiled by Bloomberg. Similarly, for the Hong Kong-listed SK Hynix leveraged ETF, about 30% of calculable trading days had a three-month forward return of -35% or worse. The chance that your FCN will go badly is very real.
私人财富管理客户可以发挥有用的市场功能。当情绪逆转、机构不愿为泡沫化交易提供保险时,银行可以指望那些毫无防备的百万富翁来承担风险。但当这些被美化的散户投资者退场时,市场才会真正崩塌。
Private wealth clients can serve a useful market function. When sentiment turns and institutions balk at writing insurance to bubbly trades, banks can count on unsuspecting millionaires to shoulder the risks. But when these glorified retail investors step back, that’s when the market really breaks.