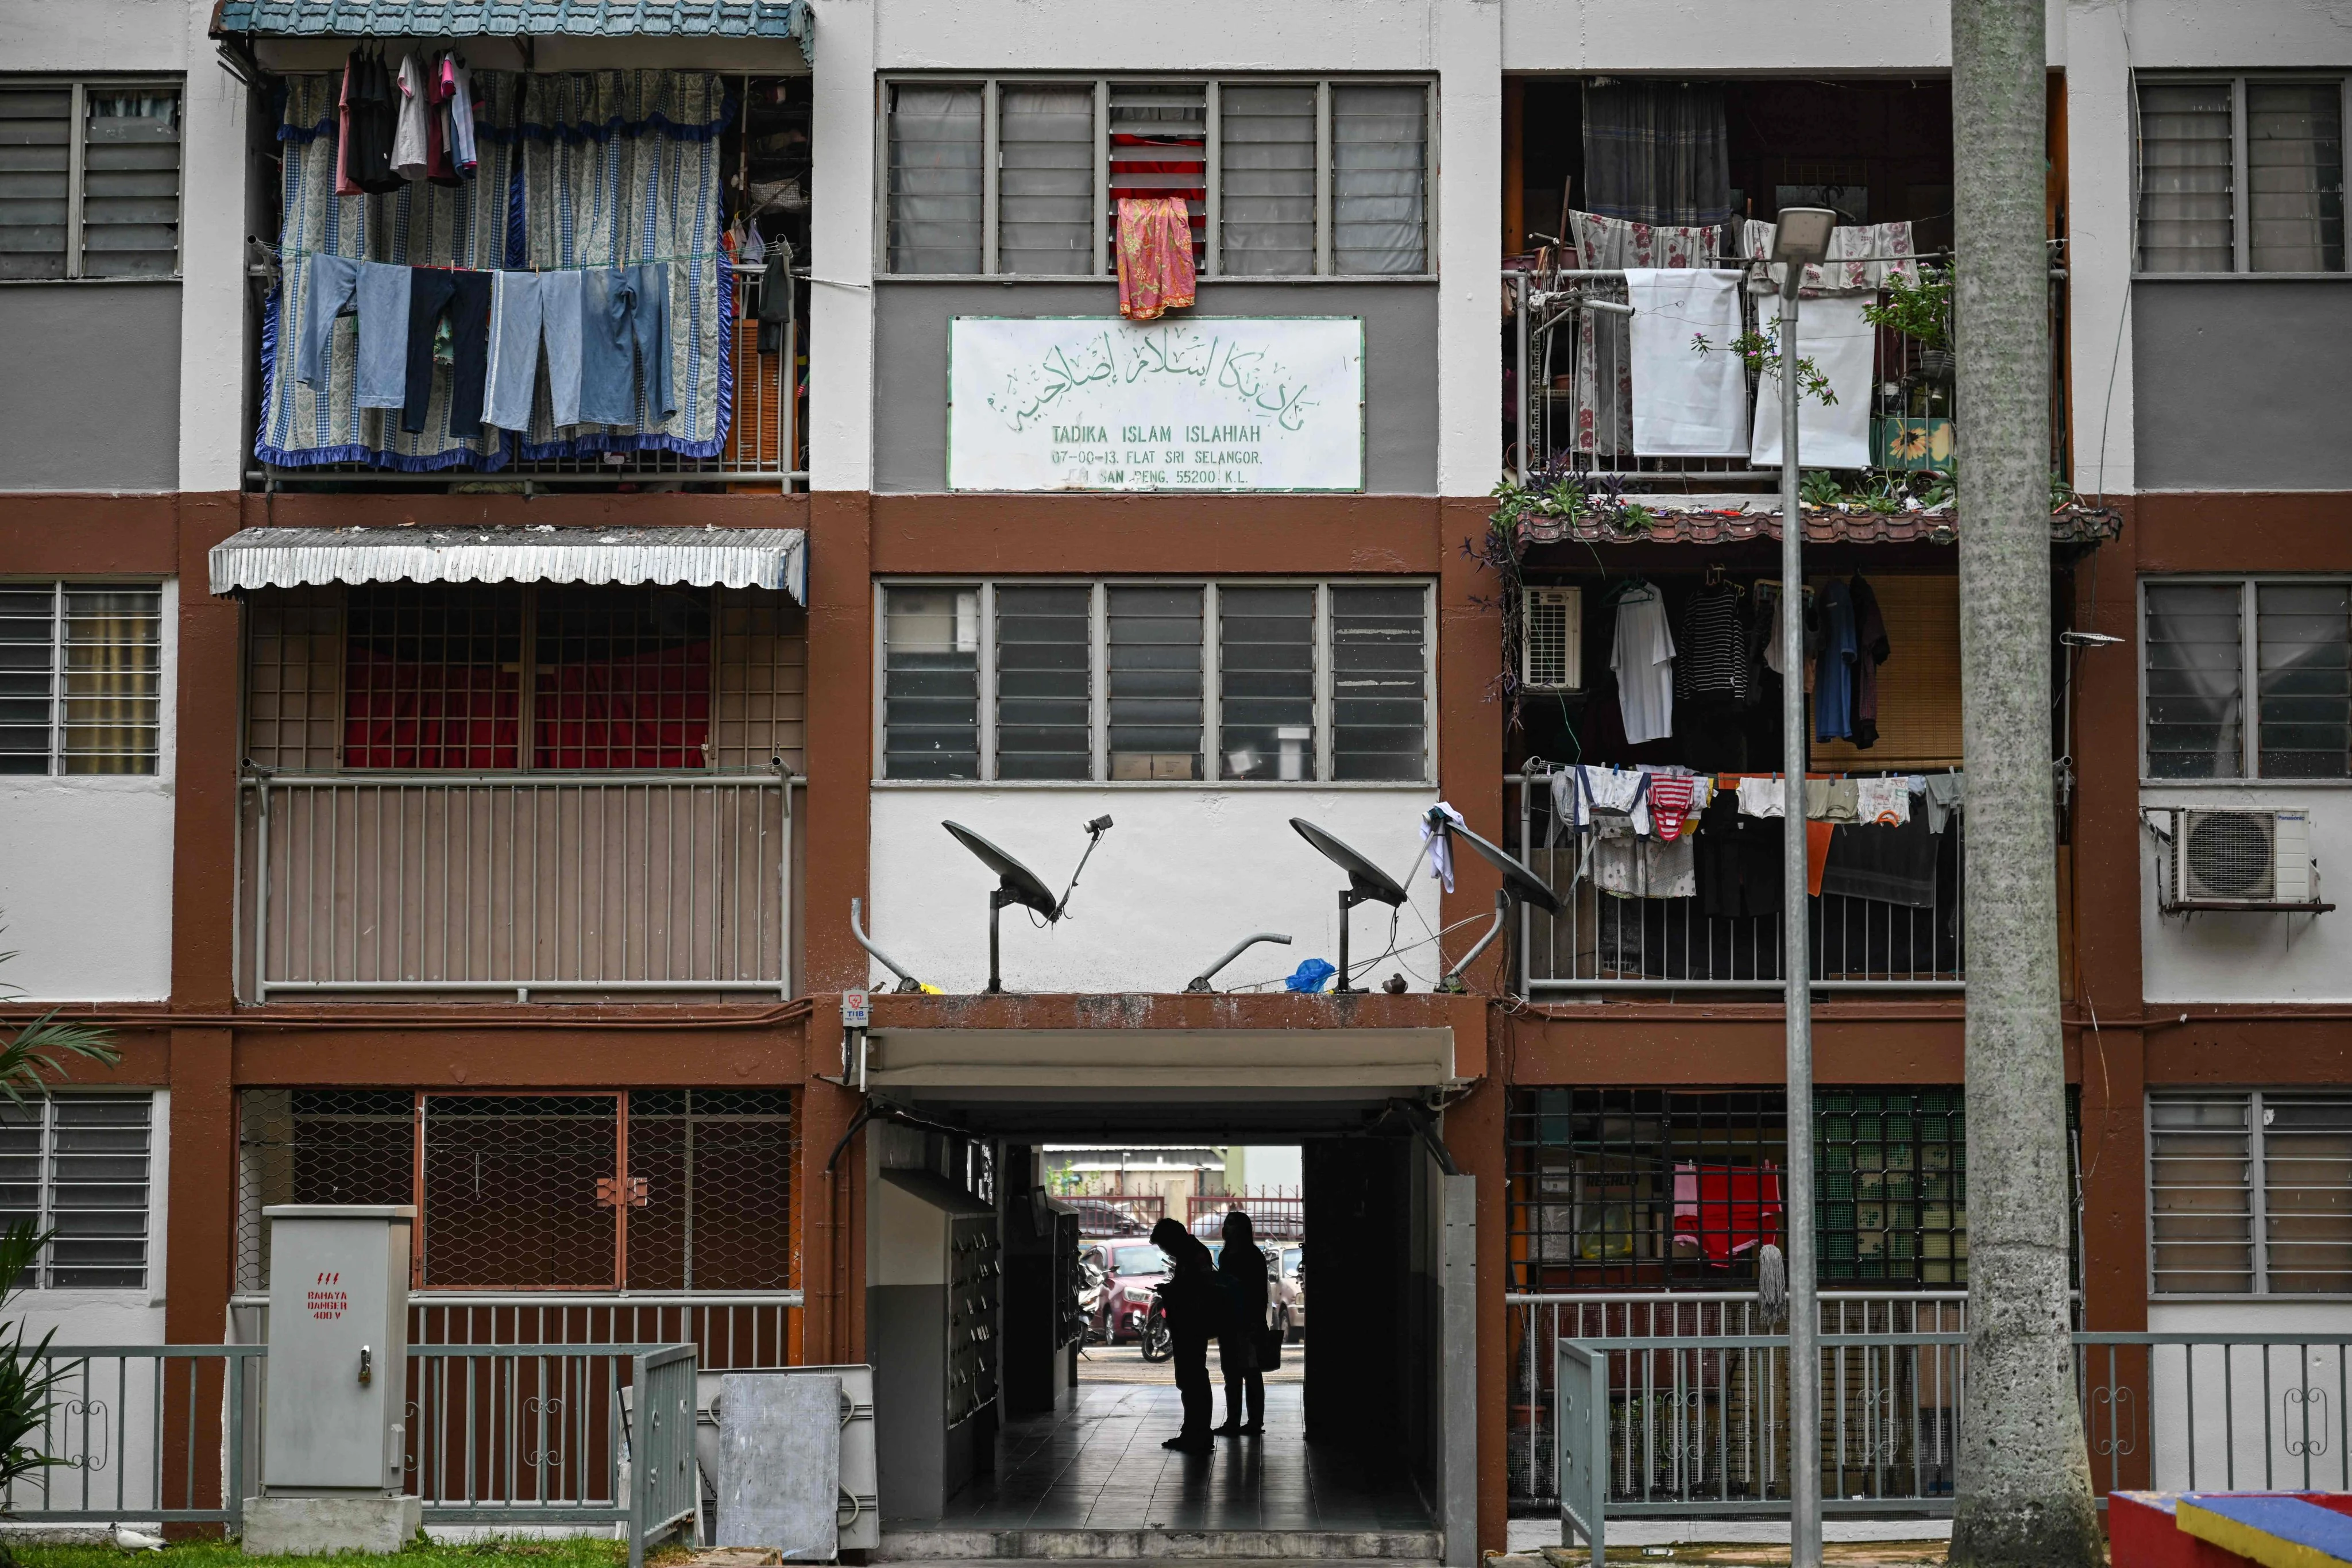
在东南亚部分地区,开发商难以清理住房库存,导致未售出住房堆积如山——然而,渴望购买首套房产的年轻买家依然找不到负担得起的住房。
In parts of Southeast Asia, unsold homes are piling up as developers struggle to clear housing stock – yet young buyers hoping to land their first property still cannot find an affordable home.
分析人士指出,这一悖论反映出所建住房与有购房意向者的支付能力之间日益加剧的错配,并将投机性投资、融资障碍和地段不佳等因素归为导致房产空置的原因,即便在对经济适用房有需求的情况下也是如此。
The paradox reflects a growing mismatch between the homes being built and what aspiring buyers can afford, according to analysts, who point to speculative investment, financing hurdles and poor locations as factors leaving properties empty even amid demand for affordable housing.
据新加坡伊萨·尤索夫东南亚研究院(ISEAS – Yusof Ishak Institute)访问研究员阮克强(Nguyen Khac Giang)表示,在越南,问题的核心在于开发商建造了什么样的房子以及他们预期的回报。他的研究探讨了该国对土地财政的日益依赖如何可能使房地产投资受惠,而非新城市家庭的住房需求。
In Vietnam, the problem centres on what developers have built and the returns they expect, according to Nguyen Khac Giang, a visiting fellow at Singapore’s ISEAS – Yusof Ishak Institute. His research examines how the country’s increasing reliance on land to finance growth can favour property investment over the housing needs of new urban families.
在菲律宾,压力呈现出不同形式,投资驱动的公寓项目和低首付方案导致部分买家无法完成购房。
The pressures take a different form in the Philippines, where investment-led condominium projects and low initial payment plans have left some buyers unable to complete their purchases.
而在马来西亚,已建成未售出住房中有相当大比例处于传统上被描述为“经济适用”的价格区间,这引发了另一个问题:为何这些房产无法满足有购买能力人群的需求?利益博弈据越南建设部称,该国报告的房地产库存在2026年第三季度达到约51,950套单元和地块。该数字涵盖了34个省级行政单位中的27个,包含住房和土地,不仅限于已建成空置公寓。
In Malaysia, meanwhile, a substantial share of completed unsold homes falls within the price range conventionally described as “affordable”, raising a different question: why do these properties not meet the needs of the people who could buy them? Competing interests According to Vietnam’s construction ministry, the country’s reported property inventory reached about 51,950 units and land plots in the third quarter of 2026. This number covered 27 of 34 provincial-level localities and included housing and land, not just completed empty flats.
与此同时,据越南房地产协会称,单价在7,000万盾至1亿盾(约合2,707美元至3,867美元)每平方米的公寓约占第三季度新推项目的48%。另有23%的项目单价在1亿盾至2亿盾之间。
Meanwhile, flats priced at 70 million dong to 100 million dong (US$2,707 to US$3,867) per square metre accounted for about 48 per cent of third-quarter launches, according to the Vietnam Association of Realtors. Another 23 per cent cost between 100 million dong and 200 million dong.
江表示,地方政府对土地财政的追求以及开发商对房价上涨的预期,有助于解释这种失衡。较高的土地成本促使开发商推出更昂贵的项目以收回投资。
Giang said local governments’ pursuit of land revenue and developers’ expectations of rising prices helped explain the imbalance. Higher land costs encouraged more expensive projects to recover the investment.
“在繁荣时期,服务普通购房者的吸引力不如押注房价进一步上涨,”他说。
“During a boom, serving ordinary buyers becomes less attractive than betting on further appreciation,” he said.
江8月发表的一篇论文指出,2025年土地相关收入达575.5万亿越南盾,占国家收入的21.7%。然而,他警告称,将公共财政和银行贷款与房地产价值挂钩,使两者都容易受到房价下跌的冲击。
A paper Giang published in August put land-related revenue at 575.5 trillion dong in 2025, or 21.7 per cent of state revenue. However, linking public finances and bank lending to property values left both vulnerable to falling prices, he warned.
“更便宜的土地可以改善负担能力,但也会削弱公共收入和基础设施融资。因此,国家面临相互竞争的目标:既要住房负担得起,又要土地保值。” 价格大幅下跌也会损害持有房地产抵押贷款的开发商和银行。江表示,能够再融资或持有库存的开发商,降价销售的压力较小。
“Cheaper land could improve affordability, but it would also weaken public revenues and the financing of infrastructure. The state therefore has competing objectives: affordable homes and valuable land.”Sharp price falls would also hurt developers and banks holding property-backed loans. Developers able to refinance or hold inventory faced less pressure to discount, Giang said.
“这些压力可以推迟调整,但无法无限期地阻止调整。” 他的论文以中国为警示,提醒依赖房地产关联收入的风险,并呼吁更透明的土地分配,以及将土地增值收益投资于补偿和保障性住房。
“These pressures can delay a correction, although they cannot prevent one indefinitely.”His paper cited China as a warning about dependence on property-linked revenues and called for more transparent land allocation and investment of land-value gains in compensation and affordable housing.
对购房者而言,普通收入难以企及的住房短缺,使得首付和还款令人望而却步。
For buyers, the shortage of homes within the reach of ordinary incomes made deposits and repayments daunting.
“抵押贷款利率的不确定性增加了另一道门槛,因为买得起优惠利率的购房者,在利率重定价时可能就会举步维艰。仅放宽贷款审批无法解决这一问题,”江说。
“Mortgage-rate uncertainty adds another barrier, because a buyer who can afford the introductory rate may struggle when it resets. Easier loan approval alone cannot fix that,” Giang said.
入门门槛低 在菲律宾,进入房地产市场与维持房屋所有权之间的差距,从部分公寓的销售方式中可见一斑,科莱恩菲律宾研究总监Joey Roi Bondoc表示。
Low entry In the Philippines, the gap between entering the property market and sustaining home ownership is evident in the way some condominiums are sold, according to Joey Roi Bondoc, research director at Colliers Philippines.
开发商将分期付款宣传为仅略高于买家每月的“星巴克预算”,Bondoc说,这意味着买家可以在楼盘建设期间,将少量首付分摊到数年内支付。
Developers marketed instalments as little more than a buyer’s monthly “Starbucks budget”, Bondoc said, meaning buyers could spread a small down payment across several years while the building was under construction.
例如,邦多克测算,一套售价 700 万比索(约合 10.956 万美元)公寓的 10% 首付款可分 60 个月缴纳。但房屋交付后,买家需通过银行贷款融资支付剩余的大额尾款。
For example, Bondoc calculated that the 10 per cent down payment on a 7-million peso (US$109,560) flat could be spread over 60 months. But once the unit was completed, the buyer would need to finance the much larger outstanding balance through a bank loan.
他表示,月供届时可能翻三倍或四倍,部分买家无力承担差额,或无法获得贷款批准。
Monthly payments could then triple or quadruple, he said, with some buyers unable to afford the difference or obtain loan approval.
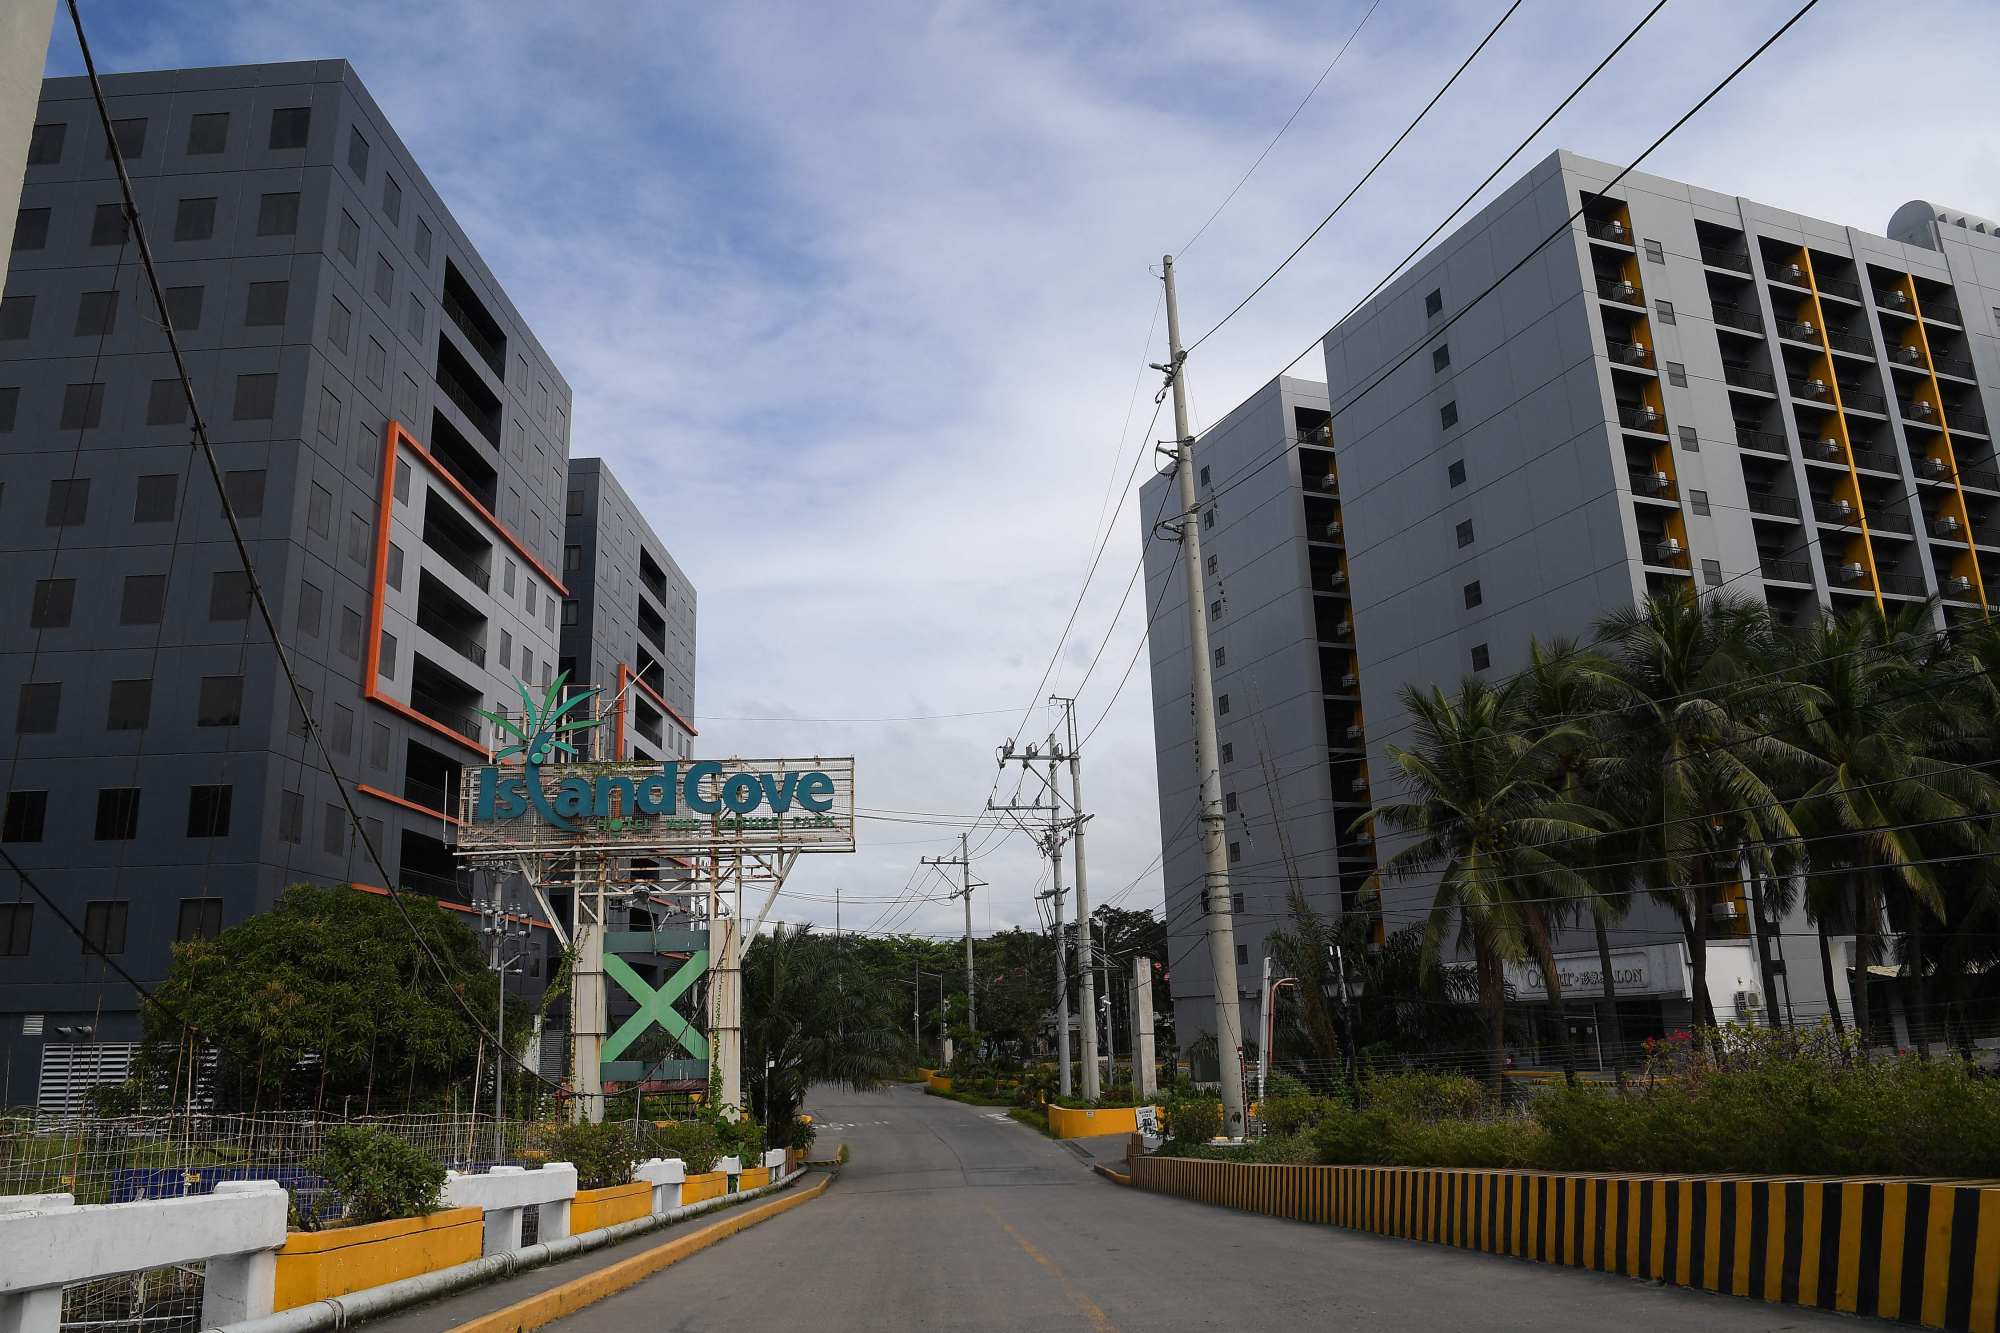
菲律宾离岸博彩运营商(POGO)先涌入后撤离,加剧了这一问题。邦多克说,公寓热潮期间,这些从业者提供了租赁需求,投资者原本指望靠租金收入帮衬还款。
The problem was compounded by the influx, then retreat, of Philippine offshore gaming operators (Pogos), whose workers had supplied rental demand during the condominium boom. Investors had expected that income to help cover their payments, Bondoc said.
邦多克指出,投机性需求在 2017 年至 2019 年达到顶峰,当时开发商每年交付近 1.4 万套公寓。他预计 2027 年至 2029 年,受市场疲软影响,年交付量将降至 6000 套左右。然而,未售库存并不一定能为购房者提供触手可及的替代选择。
Bondoc noted that speculative demand peaked between 2017 and 2019, when developers were completing almost 14,000 condominium units annually. From 2027 to 2029, he said he expected annual completions to range around 6,000 in response to weaker market conditions. Yet the unsold stock does not necessarily offer an accessible alternative for homebuyers.
仲量联行数据显示,大马尼拉地区 3.26 万套未售公寓中,逾 40% 属于该机构划定的“中低价”区间,即 360 万至 700 万比索之间。但这只是一个市场分类,并不代表职场新人就买得起。
Colliers’ data shows that more than 40 per cent of Metro Manila’s 32,600 unsold units fall within the company’s “lower-mid” price segment of between 3.6 million and 7 million pesos. But this is a market category, not a guarantee of affordability for an early-career worker.
邦多克估算,考虑购买该价位房产的买家月收入至少应达 7 万比索。然而,根据 2024 年全国工资调查,大马尼拉平均月薪为 29,310 比索,该门槛约为平均工资的 2.4 倍。
Bondoc estimated that buyers considering homes in that segment should earn at least 70,000 pesos a month. That figure, however, is about 2.4 times more than the average monthly wage in Metro Manila of 29,310 pesos, according to the 2024 national wage survey.
对部分打工者而言,在就业中心附近租房同样负担不起。邦多克描述,有员工从甲米地、布拉干和拉古纳三省通勤至大马尼拉,单程耗时一两小时,只因买不起工作地附近的住房。马来西亚的市场错配表明,未售住房并非仅集中在高价房段。
For some workers, even renting near employment centres remains too expensive. Bondoc described employees commuting from Cavite, Bulacan and Laguna to Metro Manila, with journeys taking an hour or two because they could not afford accommodation nearer their jobs. Market mismatch Malaysia shows that unsold housing is not confined to expensive properties.
马来西亚国家房产资讯中心的最新数据显示,2026年上半年有33,094套已竣工住宅单位滞销,其中37.3%(12,340套)售价在30万令吉(约合73,400美元)或以下。
Recent data from Malaysia’s National Property Information Centre revealed that 33,094 completed residential units remained unsold in the first half of 2026, of which 37.3 per cent (12,340 units) were priced at 300,000 ringgit (US$73,400) or below.
房产顾问公司Rahim & Chestertons的Siva Shanker表示,住宅滞销可能反映了产品、地段、定价不当,或这三者的组合。依他的经验,地段往往是主要问题。
Siva Shanker of Rahim & Co Chestertons, a property consultancy, said unsold homes could reflect the wrong product, location, price, or a combination of all three. In his experience, location was often the main problem.
他表示,远离工作地点和学校的低价住宅可能迫使家庭承受难以负担的通勤。“当事人或家庭宁愿不买,只会在附近租房。”对于年轻买家,Siva指出了另一个单独障碍:即使月供看似负担得起,也难以筹集所需现金。
Lower-priced homes built far from workplaces and schools could force households into unmanageable commutes, he said. “The person or household would rather not buy, they would just rent something nearby.”For younger buyers, Siva identified a separate obstacle: raising the cash needed even when monthly repayments appeared manageable.
他以一套假设的50万令吉住宅为例,若申请八成贷款,买家仅首付就需要10万令吉,还未计算律师费、印花税等其他前期开支。更别提可能还需要一笔五位数的装修费。
Using a hypothetical 500,000 ringgit home financed with an 80 per cent loan, he said a buyer would need 100,000 ringgit for the deposit alone, before other upfront expenses such as conveyancing fees and stamp duty. Not to mention potentially another five-figure sum for home renovations.
他说:“他们可能负担得起月供,却凑不齐首付。”潜在买家也可能推迟置业以攒首付,结果发现房价已上涨。“他们最终陷入永远追赶的境地,”他说。
“They may be able to afford the repayment” but lack the down payment, he said. Potential buyers might also postpone ownership to save for the down payment, only to find prices had increased. “They end up chasing forever,” he said.
在马来西亚近期的2027年财政预算案宣读中,政府宣布推出措施助首次置业者,包括通过国家管理的住房信贷担保计划提供200亿令吉融资担保,目标惠及多达8万名首购者,特别是没有固定收入的自雇人士。
In Malaysia’s recent Budget 2027 reading, the government announced measures to help first-time buyers, such as 20 billion ringgit in financing guarantees through the state-managed Housing Credit Guarantee Scheme targeting up to 80,000 first-timers, particularly the self-employed without fixed incomes.
总理安瓦·易卜拉欣还提议,对售价不超过50万令吉的首套住宅,其转让文件和贷款协议的印花税全免,涵盖2027年1月至2030年12月期间签署的买卖协议。
Prime Minister Anwar Ibrahim also proposed full stamp duty exemptions on transfer documents and loan agreements for first homes costing up to 500,000 ringgit, covering purchase agreements signed between January 2027 and December 2030.
同样在越南,建设部于4月提出推广低成本商品房,并加速一项总额145万亿越南盾的社会住房和工人住房信贷计划,其中包括对35岁以下购房者的支持。
Similarly in Vietnam, the construction ministry proposed in April to promote lower-cost commercial housing and accelerate a 145 trillion dong credit programme for social and worker housing, including support for buyers under 35.
但Giang表示,仅靠融资支持无法解决房价与收入之间的差距。
But financing support alone would not resolve the price-income gap, Giang said.
“即使对昂贵的公寓给予大幅折扣,对年轻的首套房购买者帮助也不大。”
“Even a sizeable discount on an expensive flat can’t help much for young first-home buyers.”