总部位于诺伊达的B2B在线市场IndiaMART InterMESH预计,在其黄金和白金订阅用户持续参与的支持下,其每用户平均收入增长将保持在8%左右。
Noida-based B2B online marketplace IndiaMART InterMESH expects its average revenue per user growth to remain around 8%, supported by continued engagement from its gold and platinum subscribers.
IndiaMART InterMESH有限公司首席执行官兼创始人迪内什·阿加瓦尔表示:“大约有10万名黄金和白金客户。他们继续与我们保持着非常高的互动度,我们也将继续为他们提供越来越多的增值服务。我认为这一方面不会有什么问题。”
Dinesh Agarwal, CEO and Founder of IndiaMART InterMESH Ltd, said, “There are about one lakh customers which are gold and platinum customers. They continue to be very highly engaged with us, and we continue to provide them more and more value-added services. I don't think there should be a problem on that side.”
然而,订阅用户的增加仍然是一个挑战,特别是银牌会员细分市场。阿加瓦尔表示,公司正多管齐下以解决该类别的疲软问题。由于大多数订阅都是年度的,旨在改善续费率的措施需要时间才能显现出效果。
However, subscriber additions remain a challenge, particularly in the silver-tier segment. Agarwal said the company is working on multiple fronts to address the weakness in this category. Since most subscriptions are annual, the impact of measures aimed at improving renewals will take time to become visible.
IndiaMART还一直在应对业务询盘下降的问题,阿加瓦尔将此部分归因于季节性因素和人工智能的影响。
他表示,询盘量比峰值低了约10%,这促使公司采取步骤来保护专有信息,并适应企业在网上发现和获取信息方式的变化。
IndiaMART has also been dealing with a decline in business inquiries, which Agarwal attributed partly to seasonal factors and the impact of artificial intelligence .He said inquiry volumes were around 10% below their peak, prompting the company to take steps to protect proprietary information and adapt to changes in how businesses discover and access information online.
与此同时,该公司正在利用人工智能为其顶级客户开发新产品。这些产品最早可能从第四季度开始为收入做出贡献,在现有订阅业务之外提供额外的增长机会。
At the same time, the company is using AI to develop new products for its top-tier customers. These offerings could begin contributing to revenue from the fourth quarter onwards, providing an additional growth opportunity alongside its existing subscription business.
对于2027财年,IndiaMART预计收入增长约为10%,下半年通常表现好于上半年。
For FY27, IndiaMART expects revenue growth of around 10%, with the second half typically performing better than the first.
尽管递延收入同比增长了16%,公司的Busy软件业务板块正以25%至30%的速度扩张,但总体增长可能上限在双位数左右。
While deferred revenue grew 16% year-on-year and the company's Busy software segment is expanding at 25% to 30%, overall growth will likely cap near the double-digit mark.
每用户平均收入的持续增长、高端客户互动度的增强以及新的人工智能驱动的产品预计将支撑其前景,而付费订阅用户增加的复苏仍然是一个需要关注的重要因素。
Continued ARPU growth, stronger engagement among premium customers and new AI-led offerings are expected to support its outlook, while the recovery in paying subscriber additions remains an important factor to watch.
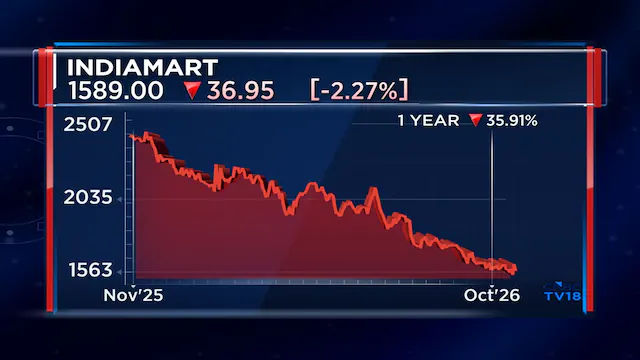
IndiaMART InterMESH目前的市值约为9527.88亿卢比。请观看随附视频
IndiaMART InterMESH’s current market capitalisation is ₹9,527.88 crore. Watch accompanying video for more