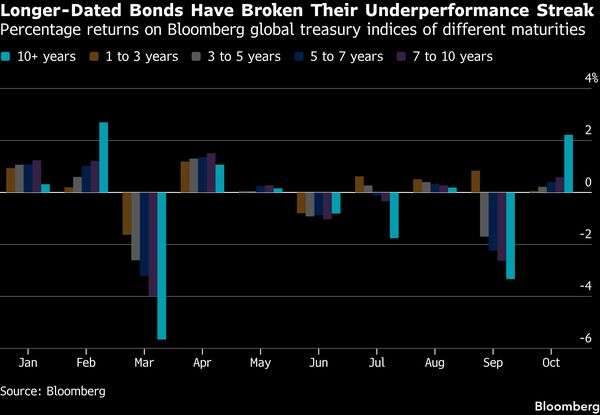
长期政府债券在今年大部分时间里都在惩罚那些敢于持有它们的人。如今收益率已高到足以让投资者重新回流。
Long-dated government bonds spent much of the year punishing anyone brave enough to own them. Now yields are high enough that investors are coming back.
接近数十年高点的无风险回报正变得难以抗拒,尤其是在股票看起来昂贵且波动较大的情况下。本月,美国10年期国债收益率一度升至近5.4%的峰值,为2002年以来最高;日本国债收益率则达到30年来的高点3.14%。
Risk-free payouts near multi-decade highs are becoming difficult to resist, particularly with stocks looking expensive and volatile. Ten-year US Treasuries yields peaked at almost 5.4% this month, their highest since 2002, while those in Japan reached a 30-year high of 3.14%.
长期债券的回归交易吸引了摩根大通资产管理、荷宝资产管理、Ninety One和安联全球投资等至少几家机构的投资组合经理。收益率现在开始回落,以期限在10年或以上的全球政府债券衡量,投资者在10月获得了2.2%的回报,这一水平轻松超过了1至3年期主权债持平的表现,也是自2月以来较长债券首次跑赢。
The comeback trade in long bonds has enticed portfolio managers at JPMorgan Asset Management, Aegon Asset Management, Ninety One and Allianz GI, to name just a few. Yields are now in reverse, rewarding investors with a return of 2.2% in October on a gauge of global government bonds maturing in 10 years or more, a level that’s handily beaten the flat performance of sovereign debt due in one to three years — and the first month since February in which longer bonds outperformed.
这些利润促使投资者至少暂时忽略最初推高收益率的危险。能源驱动的通胀、收紧的货币政策以及恶化的政府财政状况并未消失。承担这些风险的价格只是变得更有吸引力了。
Those profits have encouraged investors to overlook, for now at least, the dangers that sent yields so high in the first place. Energy-driven inflation, tighter monetary policy and deteriorating government finances haven’t disappeared. The price of taking those risks has simply become more attractive.
摩根大通资产管理全球固定收益主管鲍勃·米歇尔表示:“长端只是变得太便宜、太缺乏锚定。”他一直在买入澳大利亚和日本的较长期债券以及美国国债。
“The long-end just got too cheap and too unanchored,” said JPMorgan Asset’s head of global fixed income Bob Michele. He’s been buying longer-dated from Australia and Japan as well as US Treasuries.
随着投资者质疑科技公司在人工智能方面是否承诺过度,政府债券看起来又像避风港。交易所交易基金的资金进出情况印证了这一点。iShares美国国债ETF连续第二个月吸引资金流入,而iShares核心标普500 ETF则从上月的流入转为流出。
As investors question whether tech companies have overpromised on AI, government bonds are looking like a haven again. That’s borne out by movement in and out of exchange traded funds. The iShares US Treasury Bond ETF drew inflows for the second consecutive month while the iShares Core S&P 500 ETF flipped to outflows from inflows the previous month.
确实,政策焦虑——包括美联储、财政部以及选举相关的因素——仍在压制对期限更长的美国国债的需求。它们在美联储决定维持利率不变后抛售,因为此举重新点燃了市场对主席凯文·沃什是否坚定致力于央行2%通胀目标的怀疑。
To be sure, policy angst — Fed, Treasury and election-related — continues to weigh on demand for longer-dated US Treasuries. They sold off in reaction to the Fed’s decision to leave interest rates unchanged, which rekindled doubt that Chairman Kevin Warsh is committed to the central bank’s 2% inflation target.
期限更长的欧洲政府债务也在周四下跌,投资者将欧洲央行行长克里斯蒂娜·拉加德的言论解读为央行不会介入以遏制因法国政治和财政动荡引发的抛售。
Longer-dated European government debt also fell Thursday after investors interpreted comments from European Central Bank President Christine Lagarde to signal the central bank wouldn’t intervene to stem a selloff caused by France’s political and fiscal turmoil.
AJ Bell 投资总监希拉里·温表示:“我更倾向把它称为暂停,而不是转折点,因为今年抛售背后的压力并未消失。我们仍然倾向于质量更好、期限更短的资产,而不是追逐长期的反弹。”下个月的美国中期选举也让债券多头保持谨慎。国会分裂可能会限制财政扩张,从而有利于期限更长的国债;但若共和党意外控制两院,则可能重新点燃支出与通胀的争论。
“I’d call it a pause rather than a turning point, as the pressures behind this year’s selloff haven’t gone away,” said Hilary Winn, investment director at AJ Bell. “We still lean towards quality and shorter duration, rather than chase a long-dated rally.”Next month’s US midterms give even bond bulls reason for caution. A divided Congress could put a lid on fiscal expansion and help long-dated Treasuries, while a surprise Republican hold of both chambers risks reopening the spending-and-inflation debate.
与此同时,经济放缓和避险需求可能会拉低收益率,而宽松的财政政策或加剧通胀的战争升级则可能触发另一轮抛售,雷蒙德·詹姆斯财富管理固定收益研究主管奥利弗·法伊扎拉赫说。
At the same time, an economic slowdown and flight to safety could pull yields lower, while looser fiscal policy or an escalation of the war that fuels inflation could trigger another selloff, said Oliver Faizallah, head of fixed-income research at Raymond James Wealth Management.
法伊扎拉赫指出,国债市场的长期端“很难得到一个合理的公允价值”。
The long end of the Treasury market is “hard to get a good fair value on,” Faizallah said.
尽管如此,十月份收益率的回落为美国财政部长斯科特·贝森特在其部门的季度再融资声明前提供了一定缓解,该声明将阐明其借贷计划。市场猜测美国可能会削减20年期和30年期债券的发行,因为后者的收益率已飙升至自2002年以来的最高水平。此次反弹降低了该讨论的紧迫性,尽管许多银行仍预计此类变化可能要到2027年才会出现。
Still, October’s retreat in yields offers some relief to US Treasury Secretary Scott Bessent ahead of his department’s quarterly refunding statement, where it lays out its borrowing plans. Speculation has grown the US may cut sales of 20- and 30-year bonds, after yields on the latter soared to the highest since 2002. The rally reduces the urgency of that discussion, though many banks still expect such changes could come in 2027.
这一趋势的影响不止于美国。收益率上升正吸引买家买入长期日本国债,而德国国债则因法国动荡引发的避险需求而受益。在英国,英国央行减少长期债券发行,加上市场对首相安迪·伯纳姆新政府情绪改善,帮助长期英国国债表现优于其他债券。
The appeal extends beyond the US. Higher yields are drawing buyers to long-dated Japanese bonds, while German debt is benefiting from a flight to safety amid France’s turmoil. In the UK, reduced long-bond sales by the Bank of England and improving sentiment toward Prime Minister Andy Burnham’s new government have helped long gilts outperform.
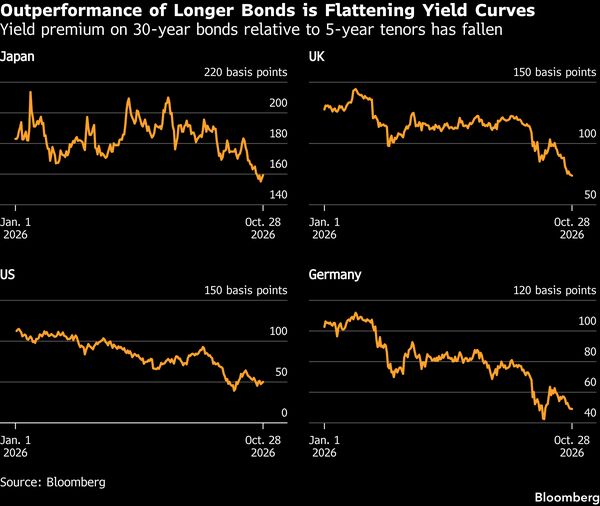
皇家伦敦资产管理公司过去几个月转为增持30年期英国国债。该公司利率与现金主管克雷格·英奇斯一直向客户表示,现在是延长久期的合适时机。
Royal London Asset Management moved to an overweight position on 30-year UK gilts over the past few months. Craig Inches, head of rates and cash, has been telling its clients it’s the right time to extend duration.
“我们看到债券收益率一路走高、走高、再走高、再走高,”英奇斯说。
“We’ve seen bond yields go higher, higher, higher, higher,” Inches said.