苹果公司将于今天下午公布全年业绩,这一罕见的周一发布安排使其再次成为全球市值最高的上市公司。苹果之所以能重登榜首,是因为其他科技巨头股在上月的人工智能抛售潮中遭受重创。对多数投资者来说,11月开局似乎将更为愉快:股指期货预示上涨,油价因中东外交突破的希望而回落。关注我们的实时市场数据和报道。
Apple, which reports full-year results this afternoon in an unusual Monday reveal, is again the world’s most valuable public company. It got there because other megacap tech stocks were battered in last month’s AI selloff. November looks set to start in a more pleasant fashion for most investors with stock futures pointing to gains and oil retreating on hopes for Middle East diplomatic breakthroughs. Follow our live markets data and coverage.
一条金融经验法则告诉我们,不要理会那些说美国股票估值过高的杞人忧天者。这只是一厢情愿的想法吗?
A financial rule of thumb tells us to ignore the worrywarts who say American stocks are expensive. Is it just wishful thinking?
一个衡量标准要想流行起来,必须满足几个条件。它必须易于计算,但又不能过于简单——一点点数学运算能增加可信度。朗朗上口的名字也有帮助,尤其是当它与某位名人和机构联系在一起时。最后,它必须经得起实践检验。
Yardsticks have to tick a few boxes to become popular. They must be easy to calculate, but not too easy—a little bit of math lends credibility. Catchy names help, especially if they’re associated with some famous person or institution. And finally, they need to have worked.
巴菲特指标、萨姆规则、格雷厄姆数字、席勒市盈率和托宾Q值各有拥趸。但在上世纪90年代末的牛市中,没有哪个指标像美联储模型那样受欢迎。如今,它正重新进入人们的讨论。
The Buffett Indicator, Sahm Rule, Graham Number, Shiller P/E and Tobin’s Q have their fans. None was as popular during the late 1990s bull market as the Fed Model. Now it’s re-entering the conversation.
它的做法很简单:将标普500指数的预期市盈率倒过来,换算成收益率,然后与基准10年期美国国债收益率进行比较。如果股票的收益率更高,那就值得持有。
It simply flips the S&P 500’s forward price/earnings ratio upside down, converting it to a yield, and compares it with the benchmark 10-year U.S. Treasury note. If stocks have a higher yield then they’re worth owning.
在盈利预期上升和国债收益率下降的背景下,该模型目前正是这样显示的。根据FactSet的普遍预期,标普500指数的“收益率”为5.3%,而10年期国债收益率仅为4.92%。
That’s what it says now amid rising earnings expectations and easing Treasury yields. The S&P 500’s “yield” is 5.3%, according to FactSet consensus, and the 10-year note is at just 4.92%.
这个简单的公式得名于华尔街策略师埃德·亚德尼,他在1997年美联储的一份出版物深处发现了它。
The simple formula got the name after Wall Street strategist Ed Yardeni spotted it deep in a 1997 Federal Reserve publication.
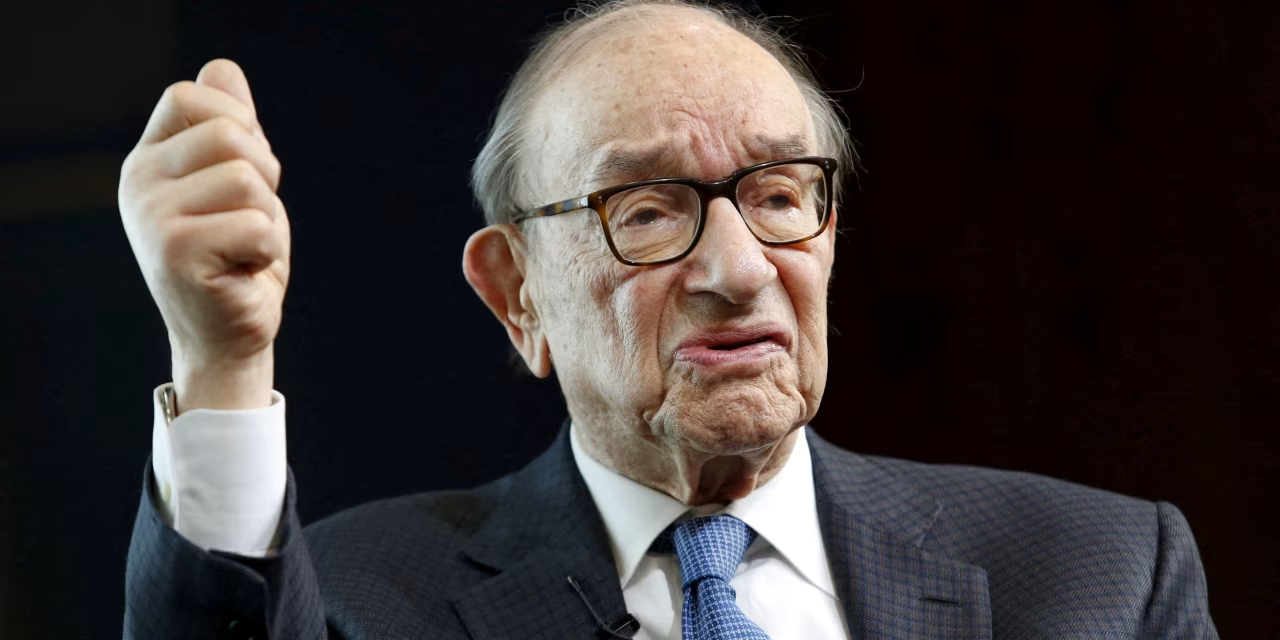
这个令人鼓舞的模型间接与美联储主席艾伦·格林斯潘联系在一起,在那轮经济繁荣接近顶峰时,格林斯潘被称为“大师”。但格林斯潘从未认可过美联储模型,而且他当时刚刚就科技股的“非理性繁荣”发出警告。
n-encouraging model was indirectly associated with Fed Chairman Alan Greenspan, dubbed “Maestro” near the height of that economic boom. But Greenspan never endorsed the Fed Model and had just warned about “irrational exuberance” in tech stocks.
在2000年初见顶的漫长长期牛市中,美联储模型大部分时间恰好是“对的”,但它也有很多批评者。
The Fed Model happened to be “right” for much of the long secular bull market that peaked in early 2000, but it had plenty of detractors.
量化投资公司AQR的克利夫·阿斯尼斯在一篇措辞尖锐的批驳文章中写道:“这看起来像是常识,但实际上并非如此。”
“This has the appearance, but not the reality, of common sense,” wrote Cliff Asness of quant firm AQR in a stinging takedown.
亚德尼后来与该模型保持了距离,尤其是在美联储人为压低债券收益率之后。但他在8月写道,该模型可能又重新适用了。
Yardeni later distanced himself from it, especially after the Fed artificially forced bond yields lower. But he wrote in August that the model might be working again.
问题在于,它混淆了股票与债券之间的关系,在企业利润率接近历史高位之际,将名义收益率与短期市盈率进行比较。一种更精细的方法则认为,股票相当昂贵。
The problem is that it muddies the relationship between stocks and bonds, comparing a nominal yield with a short-term P/E at a time of near-record corporate profit margins. A more refined approach says stocks are pretty expensive.
以席勒市盈率闻名的诺贝尔经济学奖得主罗伯特·席勒采用这种长期的、周期性调整后的基准,并将其与经通胀调整后的债券收益率进行比较。由此得出的“超额CAPE收益率”表明,股票曾经达到过这样的昂贵水平,但并不常见。目前的超额收益率与格林斯潘发表“非理性繁荣”演讲时相同。
Nobel Prize-winning economist Robert Shiller of Shiller P/E fame takes that long-term, cyclically-adjusted benchmark and compares it with inflation-adjusted bond yields. The resulting “excess CAPE yield” says stocks have been this expensive before, but not often. They’re at the same excess yield as at the time of Greenspan’s “irrational exuberance” speech.
英特尔、英伟达、SpaceX:这些股票在盘前均上涨,此前在上周科技股抛售中下跌。英特尔股价周五创下有史以来最差单日表现,此前其业绩令投资者感到恐慌。
Intel, Nvidia, SpaceX: The shares all rose premarket, after falling in last week’s tech selloff. Intel stock had its worst day ever on Friday, after its results helped spook investors.
万豪和福克斯将于开盘前发布财报,苹果(AAPL)和Palantir将在收盘后发布。
Marriott and Fox are due to report earnings before the bell, followed by Apple (AAPL) and Palantir after the close.
铠侠:这家日本存储芯片公司股价下跌16%,此前其季度利润未达到分析师预期。
Kioxia: The Japanese memory-chip company’s shares fell 16% after its quarterly profit missed analysts’ expectations.
阿尔斯通:这家法国列车制造商因部分产品的技术和生产问题下调了业绩指引,股价随后暴跌。
Alstom: Shares plunged after the French train maker cut guidance due to technical and production issues with some products.
在Netflix历史的大部分时间里,投资者关心的不是有多少人观看,而是有多少人注册并留下来。在这一点上,Netflix一直是流媒体行业羡慕的对象:其用户很少取消订阅。但这种态势正在改变。
For most of Netflix’s history, investors cared less about how much people watched than whether they signed up and stayed. On that score, Netflix has been the envy of streaming: Its customers rarely cancel. But that dynamic is changing.
1988年的这一天,一名计算机科学专业的学生向互联网释放了第一个蠕虫病毒。它使当时规模仍然很小、几乎无人听闻的网络中约十分之一的系统瘫痪。
On this day in 1988, a computer science student released the first worm onto the internet. It crippled about one-tenth of the still tiny network that hardly anybody had heard of.
《华尔街日报》| 买方:简化你的债务义务,并查看债务整合贷款是否能帮你省钱。
WSJ | Buy Side: Streamline your obligations and check to see if you could save money with a debt-consolidation loan.
商业和金融长期以来一直令我着迷。在撰写这份简报之前,我在《华尔街日报》的“街头听闻”团队担任了十年的编辑,写了两本投资书籍,并在一家全球投资银行管理过一个股票分析师团队。
Business and finance have fascinated me for a long time. Before writing this newsletter, I edited The Wall Street Journal’s Heard on the Street team for a decade, wrote two investment books and managed a team of stock analysts at a global investment bank.
《市场晨报》简报为您即将到来的交易日做好准备,提供关于有望推动市场的公司和行业的专家见解。请将您的反馈发送至 markets.am@wsj.com(如果您是在收件箱中阅读此内容,直接回复即可)。
The Markets A.M. newsletter prepares you for the trading day ahead, with expert insight into the companies and industries set to move markets. Send your feedback to markets.am@wsj.com (if you’re reading this in your inbox, you can just hit reply).