发布时间:2026-11-19T02:04:19+08:00 特立尼达·纳瓦罗(Trinidad Navarro)懂得如何追查不法行为。
Published: 2026-11-19T02:04:19+08:00 Trinidad Navarro knows how to hunt down wrongdoing.
这是他在竞选时的主打卖点。特拉华州选民选举这位资深警察兼治安官出任州保险专员,正是看中了他承诺让保险公司负责。
That was his pitch when Delaware voters picked the longtime police officer and sheriff to become their state’s insurance commissioner, drawn to his pledge to hold companies accountable.
但在随后的十年里,他的办公室错过了如今该行业最引人注目的丑闻:联邦调查聚焦于两家由亿万富翁体育大亨马克·沃尔特(Mark Walter)拥有、以该州为总部所在地的人寿保险公司。
But in the decade that followed, his office missed what’s now the industry’s most high-profile scandal: Federal probes centered on a pair of life insurers owned by billionaire sports mogul Mark Walter that call the state their home.
这属于一系列爆发事件之一,引发了人们对美国监管人寿保险公司的方式无法跟上行业快速演变的担忧。私募股权公司正在收购保险公司——据一位监管机构统计,疫情以来已增加约50家。许多公司押注的范围远超传统债券,购买复杂或高风险资产,有些通过不透明渠道或离岸渠道进行。
It’s among a spate of flareups raising concerns that the US approach to regulating life insurers is failing to keep pace with the industry’s rapid evolution. Private equity firms are snapping up insurance companies — adding about 50 since the pandemic, according to one regulator’s tally. Many are making bets far beyond traditional bonds, buying complex or risky assets, some through opaque channels or offshore.
保护保单持有人安全的艰巨任务落在州保险专员肩上,他们既面临监管保险公司的压力,又面临吸引保险公司入驻本辖区以提供就业和增加税收的压力。在11个州,监管者由选举产生,这给资金雄厚的行业参与者提供了在竞选中斥资并帮助挑选监管自己业务人选的机会。
The daunting work of keeping policyholders safe rests with state insurance commissioners facing pressure to both police insurers and attract them into their jurisdictions to provide jobs and boost tax collections. In 11 states, the watchdogs are elected, giving deep-pocketed industry players an opening to spend on campaigns and help pick who oversees their business.
批评者称,这正在引发一场监管“逐底竞赛”。在人寿保险和年金销售上升之际,一些监管机构正在放松监管或松绑规则。即使发誓保持警惕的监管者,也因人手不足而应接不暇。
Critics say that’s setting off a regulatory race to the bottom. Amid rising sales of life insurance and annuities, some watchdogs are easing oversight or loosening rules. Even those vowing to stay vigilant are getting stretched thinner.
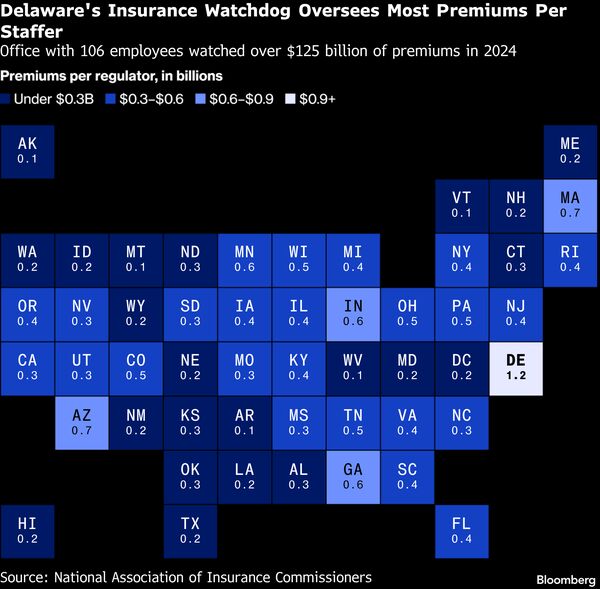
纳瓦罗的办公室尤为突出。它现在负责监管的人寿保险保费收入按每名员工计算——约12亿美元——高于任何其他州监管机构。
Navarro’s office stands out. It’s now in charge of overseeing more life insurance premiums per staffer — about $1.2 billion — than any other state regulator.
同一个办公室还负责审查阿奎里安控股(Aquarian Holdings)创始人鲁迪·萨海(Rudy Sahay)收购光明金融(Brighthouse Financial Inc.)的41亿美元竞购案——该交易因监管机构深入调查其资金来源而被推迟。
The same office is in charge of scrutinizing Aquarian Holdings founder Rudy Sahay’s $4.1 billion bid to buy life insurer Brighthouse Financial Inc. — a deal that has been delayed as the regulator digs into his sources of capital.
与此同时,对沃尔特旗下特拉华州保险公司的调查,由一组联邦检察官牵头,他们位于该州东北部100多英里之外。他们正在深挖为何沃尔特的两家公司——特拉华人寿保险公司和清泉人寿及年金公司——未披露其超过200亿美元的投资流向为资助这位大亨其他业务的实体。
Meanwhile, the probe of Walter’s Delaware-based insurers is being led by a team of federal prosecutors more than 100 miles northeast of the state. They’re digging into why two of his firms — Delaware Life Insurance Co. and Clear Spring Life and Annuity Co. — failed to disclose that more than $20 billion of their investments went to entities that finance the mogul’s other ventures.
向关联方放贷并非被禁止,但必须披露——而这两家公司直到司法部发出传票询问后才进行披露。
Lending to affiliates isn’t banned but must be disclosed — something they didn’t do until after the Justice Department sent subpoenas asking questions.
这一披露在监管专家中引发警觉:如果保险监管机构未能追踪洛杉矶道奇队和湖人队老板对保单持有人人寿积蓄的依赖程度,那么各州还在忽视什么?
The revelation has raised alarms among regulatory experts: If insurance watchdogs weren’t tracking how much the owner of the Los Angeles Dodgers and Lakers leaned on policyholders’ life savings, then what else are states overlooking?
“我不知道特拉华州监管机构在做什么,”明尼苏达大学专注于保险法的法学教授丹尼尔·施瓦茨在接受采访时表示,“这本应早就进入他们的视野。”
“I don’t know what the Delaware regulators were doing,” Daniel Schwarcz, a law professor at the University of Minnesota who focuses on insurance law, said in an interview. “This should have been on their radar for a long time.”
纳瓦罗办公室的一位代表拒绝置评。调查人员尚未指控沃尔特或其企业存在不当行为。他的TWG Global控股公司表示,“这里没有受害者。没有人受到损害,也没有人声称自己受到了损害。”这并非唯一引发担忧的情况。
A representative for Navarro’s office had no comment. Investigators haven’t accused Walter or his businesses of wrongdoing. His TWG Global holding company has said “there is no victim here. No one has been harmed, and no one has claimed they were harmed.”It’s not the only situation stoking concerns.
在康涅狄格州,监管机构过去几年一直在应对PHL可变保险公司数十亿美元的资金缺口。在该问题的全貌浮现之前,这家保险和年金提供商在私募股权公司金门资本的管理下重塑了资产负债表——此举曾获得监管批准。
In Connecticut, watchdogs have been dealing for the past couple of years with a multibillion-dollar shortfall at PHL Variable Insurance Co. Before the full extent of those problems emerged, the insurance and annuity provider had its balance sheet reshaped under the stewardship of private equity firm Golden Gate Capital — after obtaining regulatory approvals.
在南卡罗来纳州,监管机构近期试图接管Advantage Capital Holdings旗下两家保险公司,指控因投资出现问题,这两家公司处于“财务危险”境地。该案实际上是监管机构基于新信息作出的第二次干预尝试——去年一名法官推翻了此前禁止这两家保险公司承保新业务的命令,质疑州政府认定它们陷入困境的调查结果。
In South Carolina, authorities recently sought to take control of a pair of insurers from Advantage Capital Holdings, alleging they were in a “financially hazardous” position because of troubled investments. That case actually marks the regulator’s second attempt to intervene — based on new information — after a judge last year overturned an earlier order barring the insurers from writing new business, disputing the state’s findings that they were in distress.
彭博社上周报道,由Walter长期商业伙伴经营的其他保险公司,将其投资组合中相当大一部分——约210亿美元——借给了疑似作为Walter财务渠道的公司。
Bloomberg reported last week that other insurance firms run by Walter’s longtime business associates loaned a significant chunk of their portfolios — about $21 billion — to companies that appear to serve as Walter financial conduits.
尽管这些安排可能合法,并不意味着所有资金最终都流向了Walter或其公司,但这增加了外界对他从保险公司获取融资情况的了解。
While those arrangements may be legal, and don’t mean that all of the money ended up with him or his companies, it adds to what’s known about his financing from insurers.
对其商业帝国的调查引发了不同寻常的广泛批评,批评者包括亿万富翁Marc Rowan和美国参议员Elizabeth Warren。
The probe of his empire has set off an unusual range of critics, including billionaire Marc Rowan and US Senator Elizabeth Warren.
Rowan领导Apollo Global Management Inc.及其庞大的Athene年金和保险业务。他在最近一次会议上表示,Walter旗下公司能将保单持有人资金大量投向关联方,正在动摇公众对该行业的信心。
Rowan, who leads Apollo Global Management Inc. and its massive Athene annuities and insurance arm, told a conference recently that the degree to which Walter’s firms have been able to plow policyholder money into affiliates is undermining public confidence in the sector.
“我们本应是纵横全球的金融巨头,结果却要面对可能失去信任的局面,”Rowan谈到行业现状时说,“信任的丧失源于监管套利,也源于允许出现类似Delaware Life的情况。”身为马萨诸塞州民主党籍参议员的Warren,预计将于明年1月出任参议院银行委员会主席,她建议美国立法者需要更多介入。
“We should be financial giants striding the globe. Instead we are dealing with the potential loss of trust,” Rowan said of the industry. “Loss of trust comes from regulatory arbitrage. It also comes from allowing situations like have happened with Delaware Life.”Warren, a Massachusetts Democrat who’s poised to become chair of the Senate Banking Committee in January, suggested US lawmakers need to get more involved.
“国会需要了解当前的监管缺口,”她在致全美保险专员协会(National Association of Insurance Commissioners,该组织协调各州监管机构的标准)的一封信中写道。美国政策制定者必须“更好地缓解私人信贷对保险市场和保单持有人构成的风险”。这一信息很可能激怒州监管机构,自国会八十年前授予它们对保险业的唯一监管权以来,它们一直强烈抵制联邦监管。它们一直试图通过非营利组织NAIC建立一个全国性框架。一些州甚至试图取消联邦政府的最低限度监管。
“Congress needs to understand the current regulatory gaps,” she wrote in a letter to the National Association of Insurance Commissioners, which coordinates standards for state watchdogs. And US policymakers must “better mitigate the risks private credit poses to the insurance markets and policyholders.”That message is likely to rile up state regulators, who have vociferously rebuffed federal oversight in the eight decades since Congress granted them sole authority over the industry. They’ve sought to create a national framework through the nonprofit NAIC. Some states have tried to do away with even minimal oversight from the federal government.
2024年,九位州监管官员公开呼吁预计将领导政府效率部的埃隆·马斯克和维韦克·拉马斯瓦米,取消规模很小的联邦保险办公室。
In 2024, a group of nine state regulators publicly called on Elon Musk and Vivek Ramaswamy, who were expected to lead the Department of Government Efficiency, to abolish the small Federal Insurance Office.
这些监管机构在信中辩称,该办公室为财政部监控保险业,但成效不彰,并对其数据收集提出异议。
The watchdogs argued in a letter that the unit, which monitors the industry for the Treasury Department, was ineffective and they took issue with its collection of data.
NAIC随后也加入了撤销该办公室的行动,称该办公室的存在造成了关于谁拥有监管权的混淆。联邦保险办公室目前仍保留。
州监管机构正面临社会一些最大的金融挑战——试图改善健康保险的可及性,确保购房者在日益易发自然灾害的地区能买到保险,并帮助车主应对不断上涨的保费。
The NAIC later joined efforts to shut it down, saying the office’s existence creates confusion about who has authority. The FIO remains. State regulators are confronting some of society’s biggest financial challenges — trying to improve access to health insurance, make sure homebuyers can find coverage in regions increasingly prone to national disasters and help drivers deal with rising prices for policies.
除此之外,它们还必须确保销售人寿保险和年金的公司几十年后仍能履行义务。
On top of that, they have to make sure that firms selling life insurance and annuities will be around to make good on their obligations decades from now.
据批评人士称,监管这些资产负债表的一个问题是,公司可以改变其注册地。
One problem when regulating those balance sheets, according to critics, is that the companies can change where they call home.
这意味着“保险公司在很大程度上可以自行选择监管机构”,施瓦茨教授说。
That means “insurers can for most part choose who their regulator is,” said Schwarcz, the professor.
一些保险公司对此相对坦诚。阿波罗旗下的雅典娜收购自由人寿保险公司后不久,就将注册地从南卡罗来纳州迁至特拉华州。雅典娜时任负责人吉姆·贝拉尔迪直言不讳:“我们想要一个监管机构。我们更喜欢他们。”一些公司则反复更换注册地。
Some insurers have been relatively open about this. Shortly after Apollo’s Athene acquired Liberty Life Insurance Co., it changed its domicile to Delaware from South Carolina. Athene’s then-leader Jim Belardi put it simply: “We wanted one regulator. We liked them better.”Some firms jump domiciles repeatedly.
被沃尔特旗下的古根海姆收购后不久,Equitrust从爱荷华州迁至伊利诺伊州。后来,它又将注册地迁至亚利桑那州,那里的监管机构允许它采用爱荷华州法律允许的一种有利的会计做法,这种做法近年来美化了其净利润。亚利桑那州监管机构的发言人拒绝置评。
Shortly after its acquisition by Walter’s Guggenheim, Equitrust moved to Illinois from Iowa. Later, it redomiciled to Arizona, where the regulator permitted it to use an advantageous accounting practice allowed by Iowa law that has burnished net income in recent years. A spokesperson for Arizona’s office declined to comment.
2023年,在犹他州监管机构的检查报告指出多种报告错误(包括该公司对其中一家再保险公司的定性方式)以及其投资组合中潜在的利益冲突之后,SILAC保险公司将注册地迁至印第安纳州。
In 2023, SILAC Insurance Co. moved its domicile to Indiana after an examination report from Utah regulators highlighted a variety of reporting errors, including how the firm characterized one of its reinsurers, as well as potential conflict of interest in its investment portfolio.
这些监管机构要么拒绝置评,要么未立即回复消息。印第安纳州监管机构后来也指出了违规问题,包括该公司未向监管机构通报其向母公司支付的股息。
The agencies either declined to comment or didn’t immediately respond to messages. Indiana regulators later flagged irregularities, too, including the firm’s failure to notify the regulator of dividend payments the company made to its parent.
“更换注册地有正当理由,”密西西比州前保险审查员、行业冒险行为的批评者汤姆·戈伯说。但在某些情况下,“看起来他们从一个地方搬到另一个地方是为了逃避监管打击。”美国全国保险专员协会在一份声明中表示,通过迁移州份来逃避监管是不可能的,因为所有监管机构执行相同的核心标准。如果保险公司确实想更换注册地,只有在两个州都审查并批准的情况下,迁移才能进行。
“There are legitimate reasons to change domicile,” said Tom Gober, a former Mississippi insurance examiner and a critic of industry risk-taking. But in some cases, “it looks like they move from one to the other to avoid regulatory takedown.”In a statement, the NAIC said it isn’t possible to escape oversight by moving states because all regulators enforce the same core standards. If an insurer does want to change domicile, the move can only proceed if both states review and approve it.
“这不是一种逃避监管的机制,”该组织表示。此外,“基于州的体系非常适合与不断演变的市场同步并走在前面,并始终专注于确保保险公司能够兑现对保单持有人的承诺。” SILAC 和 Equitrust 的发言人(古根海姆后来出售了 Equitrust)未回复置评请求。为防止保险公司迁离,一些监管机构愿意通融规则。
“It is not a mechanism to evade supervision,” the organization said. Moreover, “the state-based system is well suited to adapt alongside and ahead of an evolving marketplace and remains focused on ensuring insurers can meet their promises to policyholders.”Spokespeople for SILAC and Equitrust, which Guggenheim later divested, didn’t respond to messages seeking comment. To prevent insurers from decamping, some regulators have been willing to bend rules.
一个令人担忧的领域涉及各州关于所谓再保险专属公司使用的规则。
One area of concern relates to state rules governing use of so-called reinsurance captives.
再保险被称为保险公司的保险,帮助公司将风险从资产负债表上转移出去以释放资本。在最近几十年里,更多再保险公司设立关联公司提供这种缓释。这些安排消除了第三方再保险公司提供的外部视角。如果没有适当的制衡,它们可能给公司及其客户带来毁灭性后果。
Reinsurance, known as insurance for insurers, helps firms shift risks off their balance sheets to free up capital. In recent decades, more reinsurers set up affiliates to provide that relief. Those arrangements eliminate the outsider perspectives that third-party reinsurers provide. Without the proper checks, they can lead to devastating consequences for firms and their clients.
在康涅狄格州,PHL 设立的专属公司是其财务恶化的核心。该公司面临超过 20 亿美元的资本缺口,预计明年将面临清算程序。客户仍在缴纳保费,却不确定是否能最终获得承诺的利益。
In Connecticut, the captives set up by PHL are central to its sinking finances. The firm is confronting a capital hole of more than $2 billion and is expected to face liquidation proceedings next year. Clients are still paying premiums, unsure they’ll ever see the promised benefits.
有时,单一州监管机构愿意为其辖区内的一家保险公司做出的迁就,最终可能使其与其他州的同行发生冲突。
Sometimes, the contortions that a single state regulator is willing to make for one of its domestic insurance firms can eventually end up putting it at loggerheads with counterparts in other states.
堪萨斯州至少几次为亿万富翁托德·博利的 Security Benefit Life Insurance Co. 出面支持。
Kansas stepped up for billionaire Todd Boehly’s Security Benefit Life Insurance Co. at least a couple of times.
十多年前,该公司及其监管机构支持一项法案,取消对资产支持证券投资的上限。这些工具已成为该公司回报的关键。
More than a decade ago, the company and its regulator supported a bill to lift a cap on investments in asset-backed securities. The instruments have become essential to the firm’s returns.
“堪萨斯州 2014 年对保险公司资产支持证券投资的修改,是作为一项两党倡议的一部分通过的,且在整个堪萨斯州立法机关未投出一张反对票,”该公司在声明中说。
“Kansas’s 2014 change to insurers’ investments in asset-backed securities was adopted as part of a bipartisan initiative and without a single dissenting vote in the entire Kansas legislature,” the firm said in a statement.
今年,该州保险监管机构成功游说同行推迟了影响抵押贷款的新资本规则,这是一种相对不常见的债务类型。这又给了 Security Benefit 一次喘息机会,该公司在这些工具上投入巨资。
This year, the state’s insurance regulator successfully lobbied peers to delay new capital rules affecting collateral loans, a relatively unusual type of debt. That was another reprieve for Security Benefit, which is heavily invested in the instruments.
但这一次,监管机构的举动激怒了该公司销售保险产品的其他州。当时,爱荷华州官员在一封公开信中称这些贷款是“最容易被利用进行资本套利的资产类别”。这一插曲也让另一个问题浮出水面:一些监管者必须通过选举才能保住职位,且一些人有竞逐更高职位的野心。这导致密西西比州保险专员迈克·钱尼呼吁将其职位改为任命制,他于 2007 年首次当选。
But that time, the regulator’s move irked other states where the firm sells coverage. In a public letter at the time, officials in Iowa called the loans “the most easily exploited asset class for capital arbitrage.”The episode also put a spotlight on another issue: Some watchdogs have to win election to keep their posts, and some have ambitions for higher office. That has led Mississippi Insurance Commissioner Mike Chaney, first elected in 2007, to call for his role to become appointed.
就在堪萨斯州游说的几周前,博利及其关联人士向该州保险专员维基·施密特的州长竞选活动捐赠了约 30 万美元。博利的主要控股公司 Eldridge Industries 表示,该公司及其关联企业“投资于我们信任的领导人。”
Only a few weeks before Kansas’ lobbying this year, Boehly and his associates donated about $300,000 to the gubernatorial campaign of its insurance commissioner, Vicki Schmidt. Boehly’s main holding company, Eldridge Industries, has said the firm and its affiliates “invest in leaders we believe in.”
施密特未回应置评请求。但今年早些时候,她的竞选团队表示,捐款“对保险部做出的政策决定没有任何影响。”她最终在共和党州长初选中排名第三,未出现在 11 月的选票上。
Schmidt didn’t respond to requests for comment. But earlier this year, her campaign said that donations “have no bearing on policy decisions made at the Insurance Department.”She ended up placing third in the Republican primary for governor and didn’t appear on November’s ballot.