突发性抛售法国债券引发担忧:欧洲主权债务危机重演?近期,法国债券的突然抛售让人们回想起2009年至2015年间席卷整个欧洲的主权债务危机。目前,市场关注的重点是欧洲中央银行(ECB)将如何应对这一局势。
A sudden selloff of French bonds has stirred memories of the sovereign debt crisis that cascaded across Europe between 2009 and 2015. Attention is now turning to how the European Central Bank might respond.
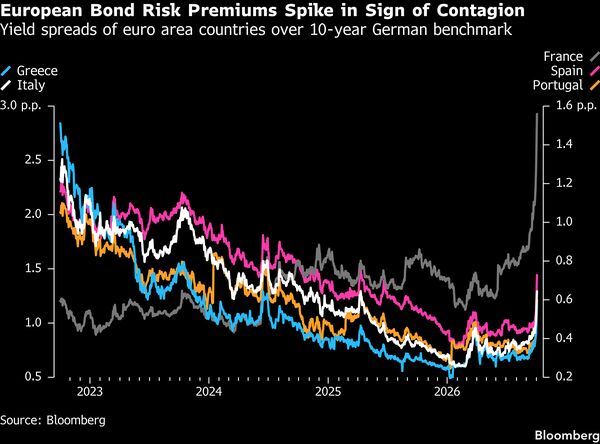
法国一直是欧元区预算赤字最大的国家之一。近期,投资者要求持有法国10年期债券所获得的额外收益(相对于德国债券而言)已达到2011年以来的最高水平;包括意大利、希腊和比利时在内的其他负债国家的债券也面临同样压力。
France has been running one of the euro area’s largest budget deficits. The extra yield demanded by investors to hold French 10-year bonds compared with those of Germany recently hit its highest since 2011. The bonds of other indebted European nations including Italy, Greece and Belgium have also come under pressure.
这表明投资者担忧“债务传染”风险:一旦对某个国家的财政状况失去信心,其他国家的债券价格也会随之下跌。
This suggests investors see a growing risk of “contagion,” in which a loss of confidence in one country’s finances causes the bonds of other nations to slump, too.
为应对这一挑战,欧洲央行拥有两种债券购买机制。其中,较为新颖且更具灵活性的“传输保护工具”(Transmission Protection Instrument,简称TPI)备受关注。该工具于2022年推出,旨在“遏制市场中的无序波动”。
To address this, the ECB has two bond-buying mechanisms at its disposal. Of these, it’s the newer, more flexible Transmission Protection Instrument — devised in 2022 to “counter unwarranted, disorderly market dynamics” — that’s drawing most attention.
目前,包括欧洲央行行长克里斯蒂娜·拉加德(Christine Lagarde)和法国央行行长埃马纽埃尔·穆兰(Emmanuel Moulin)在内的政策制定者认为,目前尚无需采取行动。
For the moment, policymakers including ECB President Christine Lagarde and Bank of France chief Emmanuel Moulin say there’s no need to act.
2009年债务危机爆发后,许多欧元区国家(包括法国)未能迅速缩减预算赤字;后来,它们为了应对新冠疫情而增加了借贷规模。持续的通货膨胀进一步加剧了这些债务的偿还成本。尽管许多政府正在努力控制债务规模,但高生活成本使得民众对削减开支和增税措施极为不满。
Many euro-area nations, including France, failed to quickly close their deficits in the aftermath of the 2009 debt blowup. Later, they borrowed even more to support populations through the coronavirus pandemic. Since then, a sustained period of higher inflation has increased the cost of servicing all that borrowing. Many governments are trying to rein in their debts, but voters are being squeezed by high living costs and are hostile to spending cuts and tax increases.
连续的法国政府在未能让分裂且两极化的议会批准紧缩预算后相继倒台。投资者已失去耐心,法国的借贷成本现在高于意大利。政府提出的2027年预算大体符合欧盟财政规则,旨在确保支出和公共债务的可持续性。但如果再次出现政府倒台,预算可能会错失赤字目标。
Successive French governments have fallen after failing to get belt-tightening budgets approved by a divided and polarized parliament. Investors have been losing patience, and France now has higher borrowing costs than Italy. The government’s proposed 2027 budget is broadly in line with European Union fiscal rules designed to ensure spending and public debt are sustainable. But there’s a risk that it will miss its deficit targets if there’s another government collapse.
明年四月的总统选举前景增加了不确定性。总统埃马纽埃尔·马克龙不能再次参选,两位主要候选人承诺将与他的中间派议程决裂。极右翼领袖玛丽娜·勒庞承诺大幅削减赤字,但她的党派没有国家政府经验,经济学家认为她的计划缺乏可信度。她还呼吁欧洲央行介入,帮助降低法国的借贷成本。左翼的让-吕克·梅朗雄提出通过取消法国银行和欧洲央行持有的一部分债务来应对法国的债务山。
The prospect of a presidential election in April next year adds to the uncertainty. President Emmanuel Macron cannot run for office again, and two of the leading candidates to replace him are promising a decisive break with his centrist agenda. Far-right leader Marine Le Pen has pledged to drastically reduce the deficit, but her party has no experience of national government and economists say her plans lack credibility. She has also called on the ECB to intervene to help bring down France’s borrowing costs. Leftist Jean-Luc Mélenchon has proposed to tackle France’s debt mountain by canceling a portion of what is held by the Bank of France and the ECB.
欧洲央行需要其货币政策在所有21个使用欧元的国家顺畅传导。这并不意味着各国应面临相同的借贷成本:通胀、经济增长和公共债务的差异应体现在债券收益率上。
The ECB needs its monetary policy to be transmitted smoothly across all 21 countries sharing the euro currency. That doesn’t mean governments should face the same borrowing costs: Differences in inflation, economic growth and public debt should be reflected in bond yields.
关注的重点在于市场波动过快或无法用经济基本面解释——尤其是当债券动荡从一个国家蔓延至其他国家时。这种碎片化会干扰欧洲央行在整个货币区调控融资条件的能力。
The concern is instead about market moves that are too rapid or can’t be justified by economic fundamentals — particularly when bond turmoil spreads from one country to others. Such fragmentation can interfere with the ECB’s ability to steer financing conditions across the currency bloc.
欧洲在2010年代的主权债务危机期间就经历过这种情况,当时始于希腊的麻烦波及了该地区的大部分南部边缘地带。随着欧洲央行准备加息,且投资者将目光投向意大利等负债累累的国家,这些担忧在2022年再次浮现。那一年,欧洲央行设计了其TPI购债工具。
That’s what Europe experienced during the sovereign-debt crisis of the 2010s, when trouble that began in Greece infected much of the region’s southern periphery. Concerns resurfaced in 2022 as the ECB prepared to raise interest rates and investors focused on highly indebted countries such as Italy. That year, the ECB devised its TPI bond-buying tool.
这一构想是在市场上进行临时干预,在某个国家的债券遭到突发抛售时支撑其价格。欧洲央行表示,可以启动TPI来“应对威胁货币政策传导的不必要、无序的市场动态”。央行实际上会印钞并用这些钱买入被投资者抛售的债券。该工具没有预设的支出限额,且TPI的某些方面被刻意保持模糊,以便央行能够针对其可能面临的任何危机灵活做出反应。
The idea would be to intervene temporarily in the market to support the price of a nation’s bonds during a sudden selloff. The ECB says the TPI can be activated to “counter unwarranted, disorderly market dynamics” that threaten the transmission of monetary policy. The central bank would effectively print money and use it to buy up bonds being dumped by investors. There would be no preset spending limit, and some aspects of the TPI have been deliberately left vague so the central bank could react flexibly to whatever crisis it might be facing.
真正使用TPI将是一个重大举措,并且会消除一些可能为其威慑力做出贡献的神秘感。欧洲央行在2022年从未需要部署它,自那以后它一直被闲置。
Actually using the TPI would be a major step, and would remove some of the mystery that may have contributed to its deterrent power. The ECB never needed to deploy it in 2022, and it has remained on the shelf ever since.
在动用TPI之前,决策者可能会尝试通过口头安抚市场,并敦促受影响的国家解决其财政问题。
Before reaching for the TPI, policymakers would probably try to calm markets verbally and urge the affected country to address its fiscal problems.
一方面,正值通胀率超出欧洲央行2%的目标且利率不断上升之际,此举会向欧元区经济注入数额可观的资金。因此,欧洲央行官员需要考虑TPI对通胀的影响以及缓解这种影响的方法。
For one thing, it would inject a potentially significant amount of money into the euro-zone economy just when inflation is overshooting the ECB’s target of 2% and interest rates are on the rise. So ECB officials would need to consider the inflationary impact of the TPI and ways to mitigate it.
他们还需要考虑市场观感。欧洲央行的职责是金融系统的仲裁者,而不是参与者。它不希望被视为在充当最后贷款人,去支撑那些财政上不负责任的政府。
They’d also need to think about the market optics. The ECB is there to be an arbiter of the financial system, not a player. It doesn’t want to be seen propping up fiscally irresponsible governments as a kind of lender of last resort.
因此,欧洲央行(ECB)只有在相关国家遵守欧盟的财政框架时,才会实施“直接货币交易”(TPI)计划。这意味着该国的公共债务必须具有可持续性,其政府也应实施稳健的经济政策。
For that reason, the ECB would only make TPI purchases if the country concerned is complying with the bloc’s fiscal framework. That means its public debt must be sustainable and its government should be following sound economic policies.
法国的情况较为复杂:其市场问题至少部分源于自身的财政和政治问题——而这正是欧洲央行无法解决的领域。
France is a difficult case. Its market troubles are rooted at least partly in its own fiscal and political problems — precisely the kind of issues the ECB isn’t there to fix.
如果政策制定者认为市场抛售行为正在加剧,且其他地区的市场走势与经济基本面越来越脱节,那么实施TPI计划或许会变得更加合理。
The TPI could become easier to justify if policymakers conclude that a selloff is intensifying and market moves elsewhere are becoming increasingly detached from economic fundamentals.
法国官员表示,当前的情况还远未达到需要欧洲央行干预的程度。法国央行行长穆兰(Moulin)指出,目前尚未满足欧洲央行采取行动的条件,并强调“欧洲央行的职责并非解决各国的财政问题”;他认为解决问题的关键在于法国自身——即必须通过预算并承诺将财政赤字控制在国内生产总值的5%以下。
French officials have said the situation is nowhere near the point at which ECB intervention is warranted. Bank of France Governor Moulin said the conditions for ECB action aren’t currently met, and that “the ECB is not there to deal with the fiscal problems of countries.”He argued that the solution lies with France itself: passing a budget and committing to keep the deficit below 5% of gross domestic product.
其他欧洲央行官员也认为,仅凭较高的借贷成本并不足以成为干预的理由。德国联邦银行行长约阿希姆·纳格尔(Joachim Nagel)表示,欧洲央行的债券购买计划并非用于维持特定的利差水平;另一位欧洲央行理事会成员、芬兰的奥利·雷恩(Olli Rehn)则认为,目前没有理由为法国动用欧洲央行的救助机制。
Other ECB policymakers have said higher borrowing costs alone don’t warrant intervention. German Bundesbank President Joachim Nagel said the ECB’s bond-buying tools aren’t designed to defend particular “spread” levels. Another ECB Governing Council member, Finland’s Olli Rehn, said there’s currently no reason to deploy the ECB’s safety net for France.
此外,欧洲央行还拥有“直接货币交易”(OMT)计划——这一债券购买计划始于2012年,当时欧洲央行行长马里奥·德拉吉(Mario Draghi)承诺“不惜一切代价”维护欧元的稳定。不过,OMT计划至今尚未被实际使用过。
No. The ECB also has the Outright Monetary Transactions plan, a bond-buying program created in 2012 after its then-President Mario Draghi vowed to do “whatever it takes” to preserve the euro. OMT has also never been used.
与TPI计划相比,OMT计划的适用范围更为有限,且对参与国的要求更为严格:该国必须参与欧洲的救助计划并遵守相应的政策规定。因此,OMT计划更适合应对全面性的主权债务危机,而不仅仅是控制市场秩序的混乱。
It’s a narrower tool than TPI and carries much more stringent requirements. A country must be part of a European rescue program with policy conditions, making OMT better suited to a full-blown sovereign-debt crisis than simply containing disorderly markets.