在法国试图恢复公共财政和街头秩序之际,政府面临着一项重大财务挑战:异常依赖外国投资者,而这些投资者已不再有强烈理由前来“救场”。
As France tries to restore order to the public finances and the streets, the government faces a significant financial challenge: an unusual reliance on foreign investors who no longer have a strong reason to come to its rescue.
与大多数其他主要经济体相比,法国政府更依赖海外贷款人,尤其是日本的贷款人,来为其赤字融资。根据欧盟数据服务机构的数据,去年法国近55%的债务由境外持有。在美国,这一比例为31%,在日本为13%。
More than most other major economies, the French government depends on overseas lenders, especially in Japan, to fund its deficit. Almost 55% of French debt was owned outside the country last year, according to the European Union’s data service. In the U.S., the figure stood at 31% and in Japan, 13%.
多年来,外国人都喜爱法国的债务市场,这是世界上最大的市场之一。债券交易便利,收益率略高于其他经济体,但被视为安全,因为有欧盟第二大经济体作为支撑。每当收益率上升时,外国人就会涌入,以利用所提供的更高回报。
For years, foreigners loved France’s debt market, one of the world’s biggest. The bonds were easy to trade and yielded a bit more than other economies, but were perceived as safe, backed up by the European Union’s second-largest economy. Whenever yields rose, foreigners would swoop in to take advantage of the higher returns on offer.
但这次感觉不同。投资者表示,为法国融资的外国资本可能正在逆转,这是导致抛售的一个因素,而上周末的骚乱使抛售进一步加剧。
This time feels different. The foreign capital that finances France may be going into reverse, investors say, a factor in a fall selloff that worsened after riots last weekend.
“我将其视为法国的一大脆弱性,”研究机构潘泰宏观经济学的欧元区首席经济学家克劳斯·维斯特森说。“因为日本的国内收益率现在非常高,存在这样一种想法,即资金会回流。”由于官方数据存在滞后,目前尚不清楚境外投资者在最近的波动中表现如何。但一些资产管理人和分析师表示,对法国预算谈判和明年全国选举的严重不确定性,将使海外贷款人对购买更多债券三思而后行,或促使一些人出售。
“I rank it as a big vulnerability in France,” said Claus Vistesen, chief eurozone economist at research firm Pantheon Macroeconomics. “Because Japan’s domestic yields are now so high, there is this idea that money will go home.”It is unclear yet from official data, which have a lag, how investors outside France have behaved during the recent volatility. But some money managers and analysts say severe uncertainty about French budget negotiations and next year’s national elections will give overseas lenders pause for thought about buying more bonds, or encourage some to sell.
另一个原因是:现在除了法国之外还有诱人的选择,尤其是在日本,经过长期超低利率,投资者不再需要到国外寻找收益率了。
Another reason: There are now tempting options beyond France, especially in Japan, where investors no longer need to hunt for yields abroad after a long stretch of ultralow rates.
法国债券自九月初开始承压,起初是受全球收益率上升推动,这使投资者关注债务市场中的薄弱环节。赤字削减计划不受欢迎,加剧了压力,而本周的骚乱则可能使政府削减开支变得更加困难。
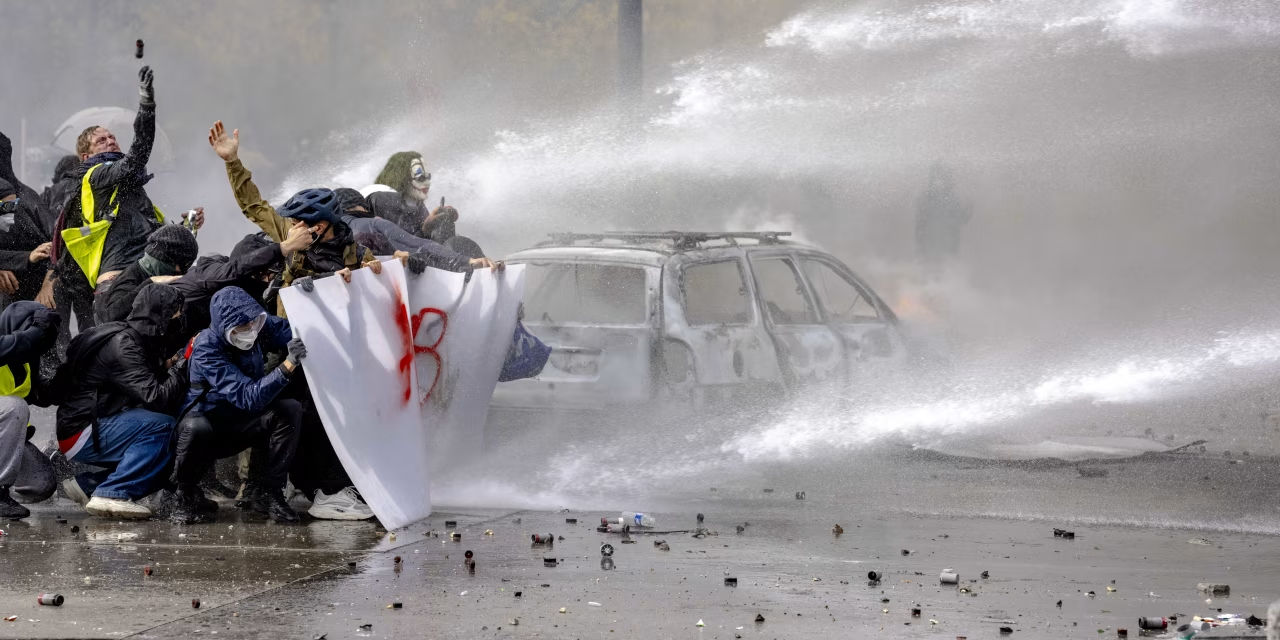
French bonds began to suffer in early September, fueled at first by a global rise in yields that focused attention on weak links in debt markets. Pressure built with poorly received plans to reduce the deficit, and again this week after riots that could make it even harder for the government to cut spending.
法国十年期国债收益率本周首次自2002年以来超过5%,并在周四继续上升。其与德国国债的利差——德国国债是欧洲的首选避险资产——自2011年欧元区危机最严重的阶段以来首次如此宽泛。利差已超过1.6个百分点,超过年初水平的两倍多。
Ten-year French bond yields surpassed 5% for the first time since 2002 this week and continued rising Thursday. Their spread over equivalent German bunds, Europe’s go-to safe asset, hasn’t been so wide since 2011, during one of the worst phases of the eurozone crisis. The spread has surpassed 1.6 percentage points, more than double where it started the year.
由德国保险公司安联所有的债券投资者惠理集团(Pimco)是谨慎贷款者之一。投资组合经理康斯坦丁·费特(Konstantin Veit)表示,除非当选官员提出可信的赤字削减计划,否则这种情况不太可能改变。2025年,法国赤字占国内生产总值的比例为5.1%。
Pimco, the debt investor owned by German insurer Allianz, is among the ranks of cautious lenders. Portfolio manager Konstantin Veit says that is unlikely to change unless elected officials show a credible plan to reduce the deficit, which stood at 5.1% of gross domestic product in 2025.
“一个并非仅限于法国的问题是,你在任何地方都能找到不错的收益率,”费特说。
“One issue that isn’t confined to France is that you find good yields everywhere,” Veit said.
海外持有可以成为一种优势,因为它降低了法国自身金融体系与其债券之间的关联。2010年代,意大利银行大量持有政府债务,加剧了该国的金融动荡。
Overseas ownership can be a strength in that it reduces the linkages between France’s own financial system and its bonds. Large holdings of government debt by domestic banks worsened Italy’s financial dramas in the 2010s.
另一面则是,海外私人投资者比本地贷款人更可能撤资,而且他们可选择的投资地点更多。英国财政监督机构在2023年的一份报告中表示,资本回流曾导致1994年国际债券恐慌,以及欧元区危机期间的恐慌。如今,较高的收益率使日本和德国显得特别有吸引力。
The flip side is that private investors abroad are more likely than home lenders to step away, and they have a longer menu of places where they can invest. Repatriation of capital contributed to international bond panics in 1994 and again during the eurozone crisis, Britain’s fiscal watchdog said in a 2023 report. These days, higher yields make Japan and Germany look particularly alluring.
潘特宏观(Pantheon)的维斯特森(Vistesen)去年估计,日本投资者持有法国10%至15%的债务。巴克莱分析师罗汉·坎纳(Rohan Khanna)估计,总体而言,31%的法国债务由欧元区以外持有,24%由单一货币区的其他成员国持有。
Pantheon’s Vistesen last year estimated that Japanese investors owned between 10% and 15% of France’s debt. In total, Barclays analyst Rohan Khanna estimates, 31% of French debt is held outside the eurozone and 24% in other members of the single-currency bloc.
他表示,法国财政部数据显示,日本投资者在截至8月的三个月内增加了对法国债券的持有,就在抛售开始之前。
He says Ministry of Finance data suggest Japanese investors added to their French bondholdings in the three months through August, just before the selloff began.
不过,一个大群体已经开始削减。花旗银行分析师藤木朋久在最近的一份报告中表示,日本人寿保险公司在2022年欧洲央行加息后削减了其法国债券持有量,因为这使得对冲货币波动的成本更高。他预计,随着日本利率上升,现在将出现更多“逐步回流”。
One big group has already cut back, however. Japanese life insurers reduced their French holdings after the European Central Bank raised interest rates in 2022, which made it more expensive to hedge against currency moves, Citigroup analyst Tomohisa Fujiki said in a recent note. He expects more “gradual repatriation” now that Japanese rates have risen.
另一大持有者——欧洲央行——在2010年代以及新冠疫情期间,作为其量化宽松计划的一部分,大举购买欧元区政府债务。自2023年以来,它一直在通过被称为量化紧缩的过程解除这些持仓。
Another major owner, the ECB, splurged on eurozone government debt in the 2010s and again during the Covid pandemic as part of its quantitative-easing program. It has unwound those holdings since 2023 in a process known as quantitative tightening.
韦特表示,法国银行财务状况良好,且持有本国政府债券的比例相对较小,这使它们有空间介入并购买。不过,这可能会降低它们向企业或消费者发放贷款的能力。
French banks are in good financial health and have a relatively small portion of their own government’s debt, giving them room to step in and buy, said Veit. That could, however, reduce their ability to lend to companies or consumers.
投资者预计,穆迪将在周五下调法国的信用评级,同时维持该国的投资级地位。投资者表示,这不太可能立即推高债券收益率。但这可能会促使一些保守的参与者,例如央行储备管理人员,停止购买。
Moody’s is expected by investors on Friday to downgrade France’s credit rating, while retaining the country’s investment-grade status. Investors say that is unlikely to move bond yields immediately. But it could encourage some conservative players, such as central-bank reserve managers, to stop buying.
任何进一步的抛售都将使法国更难说服投资者,其能够改善财务状况。它有巨额赤字需要融资。而且,它需要用收益率远高于当时的新发行证券,来偿还在利率接近0%时发行的到期债券。
Any further selloff will make it harder for France to persuade investors it can improve its finances. It has a substantial deficit to fund. And it needs to pay back maturing bonds issued when rates were near 0% with newly issued securities yielding much more.
法国到2030年到期的债务超过1万亿美元。明年,它计划发行约3800亿美元的债券,创下纪录。
France has more than $1 trillion in debt coming due by 2030. Next year it is set to sell a record of about $380 billion in bonds.
“这是一个非常困难的局面,”维斯特森表示。他说,如果政府能将赤字降至GDP的4%,可能勉强撑过去,但如果赤字达到5%,市场将继续惩罚它。
“It is just a really difficult situation,” said Vistesen. The government can probably muddle through if it gets the deficit down to 4% of GDP, he said, but the market will keep punishing it at 5%.