随着港元逼近其交易区间的弱端,策略人士认为货币防御措施将提升借贷成本波动的风险,而银行间体系的现金储备正处于历史低位附近。
As the Hong Kong dollar nears the weak end of its trading band, strategists see currency defenses raising the risk of volatility in borrowing costs, with interbank cash reserves sitting near historical lows.
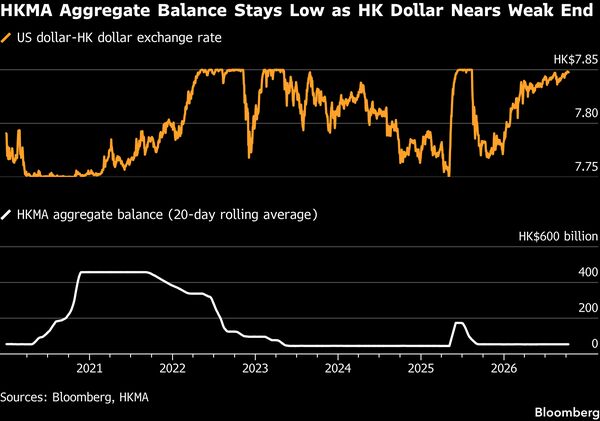
港元已逼近其对美元7.75–7.85的交易区间弱端,因美国国债收益率上升促使交易员更倾向于持有美元而非当地货币。为防止港元突破其弱端限制,香港金融管理局买入港元,这一操作会耗尽银行间体系的现金缓冲,即所谓的综合余额。
The Hong Kong dollar has moved within striking distance of the weak end of its 7.75–7.85 per US dollar trading range as higher Treasury yields prompt traders to favor the greenback over the local currency. To prevent the currency from breaching its weak-side limit, the Hong Kong Monetary Authority buys local dollars, an operation that drains an interbank cash buffer known as the aggregate balance.
该流动性回笼推高了银行间借贷成本,并使交易员做空港元的吸引力下降。但根据彭博对金管局数据的分析,综合余额已降至540亿港元(6.9亿美元),这一水平仅在2023年货币防御活跃阶段出现过一次。
That liquidity withdrawal drives up interbank borrowing costs and makes it less attractive for traders to short the Hong Kong dollar. But the aggregate balance has already fallen to HK$54 billion ($6.9 billion), a threshold crossed only once in 2023 during active stretches of currency defense, according to a Bloomberg analysis of HKMA data.
策略人士认为,现金缓冲过薄将提升即使金管局进行适度干预也可能导致本地借贷成本出现剧烈波动的风险。
Strategists see a thin cash buffer raising the risk of even modest HKMA interventions causing sharp spikes in local borrowing costs.
“香港银行同业拆息的总体趋势将呈上行态势,”香港星展银行策略师李嘉怡表示。“如果综合余额跌至之前的低点,可能会出现波动。”金管局已提醒公众,在港元逼近其弱端交易限制时,需在购房、投资和借贷方面管理利率风险。周三,港元交易价格徘徊在该7.85界限下方约17个基点。
“For Hong Kong Interbank Offered Rates, the overall trend is set to be upward,” said Carie Li, a strategist at DBS Bank in Hong Kong. “It could be volatile if aggregate balance falls to the previous lows.”The HKMA has already cautioned the public to manage interest-rate risks across property purchases, investments, and borrowing as the Hong Kong dollar approaches its weak-side trading limit. The local currency traded around 17 pips shy of that 7.85 boundary on Wednesday.
若货币防御措施导致剩余现金过快耗尽,华侨银行预计金管局将通过选择不续到期票据或在时间紧迫时进行主动回购,向银行间市场注入流动性。
Should currency defenses drain remaining cash too rapidly, Oversea-Chinese Banking Corp. expects the HKMA to shift liquidity to the interbank market, either by choosing not to roll over maturing bills or via active buybacks if the time is tight.
“如果出现这种流动性转移,将适得其反,削弱外汇干预的效果,可能因港元汇率出现双向波动而使过程延长,”该行外汇和利率策略主管张凤仪上周在一份报告中写道。
“This shift of liquidity, if it happens, will be counterproductive to the impact of FX intervention, potentially lengthening the process with two-way fluctuations in Hong Kong dollar rates,” Frances Cheung, head of foreign exchange and rates strategy at the bank, wrote in a note last week.
这是因为向银行体系注入现金将抵消金管局吸走流动性、导致汇率双向波动的货币购买行为。在流动性波动之外的时期,张凤仪预计银行间利率只会出现温和的上行。
That’s because injecting cash into the banking system would counteract the HKMA’s currency purchases that drain liquidity and cause two-way rate swings. Outside periods of liquidity fluctuations, Cheung expects only a mild upside in interbank rates.
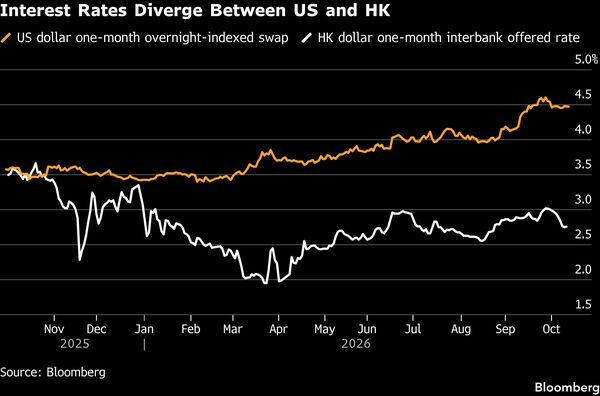
一个月期港元银行同业拆息(Hibor)已从9月下旬触及的九个月高点3.02%回落至约2.7%,与同期限的隔夜指数掉期(OIS)利差扩大至自5月以来的最大水平。
The one-month Hibor has fallen to around 2.7% from a nine-month high of 3.02% touched in late September, widening the spread with the US overnight indexed swaps of the same tenor to the widest since May.
摩根士丹利分析师指出,虽然低聚合余额唤起了人们对2022–2023年的记忆——当时美联储激进加息和金管局干预推高了Hibor和按揭成本——但香港更广泛的缓冲应能限制此次影响。
Morgan Stanley analysts noted that while a low aggregate balance revives memories of 2022–2023, when aggressive Fed rate hikes and HKMA interventions drove up Hibor and mortgage costs, Hong Kong’s broader buffers should limit the impact this time.
“低聚合余额会提高Hibor对金管局进一步收回流动性的敏感性,但它反映的是结算流动性,而非银行体系的整体资金状况,而后者如今状况要健康得多,”由郑静领衔的分析师团队在9月28日的一份报告中写道。该行指出,聚合余额仅占货币基础的2.6%,无法反映更广泛的银行体系流动性,而后者仍然得到支撑,因为存款增长快于贷款增长。
“A low aggregate balance raises Hibor’s sensitivity to further HKMA liquidity withdrawal, yet it captures settlement liquidity rather than the banking system’s overall funding position, which is much healthier today,” analysts led by Jenny Zheng wrote in a Sept. 28 note. The aggregate balance accounts for just 2.6% of the monetary base and fails to capture broader banking system liquidity, which remains supported as deposit growth outpaces lending, according to the bank.
虽然聚合余额的收缩不被视为对港元与美元挂钩的威胁,但薄弱的流动性缓冲将使套利交易者——他们试图从利率差中获利——变得极其脆弱。这是因为即使金管局的小规模干预也可能迅速耗尽剩余现金,引发借贷成本急剧飙升,从而抹去他们的利润。
While the shrinking aggregate balance is not seen as a threat to the Hong Kong dollar’s peg to the greenback, a thin liquidity buffer leaves carry traders, who look to profit from interest-rate gaps, highly vulnerable. That’s because even a small HKMA intervention could rapidly drain remaining cash and trigger a sharp spike in borrowing costs that wipes out their profits.
由于存在该风险,在总体余额偏低的情况下,交易员对推低港元仍保持谨慎,这使得任何潜在干预保持适度,星展银行的李先生如是说。
Because of that risk, traders remain cautious about pushing the Hong Kong dollar lower while the aggregate balance is thin, keeping any potential intervention moderate, according to DBS Bank’s Li.
“波动幅度是否会更大取决于金融市场活动是否活跃,”李先生表示。“目前,此类活动并不特别活跃。”
“Whether there could be bigger swings depends on whether financial market activities are thriving,” Li said. “Currently, such activities are not particularly strong.”