全球银行正对澳大利亚私募信贷基金的融资趋于冷却,这威胁到本已面临房地产低迷、借贷成本上升和监管审查的行业。
Global banks are cooling on financing Australian private credit funds, threatening to squeeze an industry that’s already grappling with a property downturn, higher borrowing costs and regulatory scrutiny.
据知情人士透露,高盛集团和瑞银集团等贷款机构正变得更加挑选性地向私募信贷管理人提供专项融资。银行正将新放贷重点放在规模最大、最顶级的私募市场管理人上,回避规模较小的公司以及在澳大利亚困境中的房地产市场敞口较大的公司。知情人士要求匿名,因为他们未获授权公开发言。他们补充称,已有的承诺大体仍在维持。
Goldman Sachs Group Inc. and UBS Group AG are among lenders that are becoming more selective about extending specialized financing to private credit managers, according to people familiar with the matter. Banks are instead focusing any new lending on the largest and top-tier private market managers, while steering away from smaller firms and those heavily exposed to Australia’s struggling real estate market, the people said, asking not to be identified as they aren’t authorized to speak publicly. Existing commitments are largely still being maintained, they added.
华尔街一些最大玩家在近年迅速扩张此业务,为基金提供用于交易的资本或帮助满足投资者赎回需求。退出市场将使本已承压的行业流动性进一步渗透。
Some of Wall Street’s largest players rapidly grew this business in recent years, offering funds the capital to deploy into deals or help meet investor redemptions. Stepping back from the market threatens to seep liquidity from a sector already under stress.
约有一半的澳大利亚2000亿澳元(约合1400亿美元)私募债务市场与房地产相关,使其对日益加深的房地产低迷尤为脆弱。悉尼开发商Bathla Group于八月进入破产程序,欠私募债务管理人约34亿澳元。监管机构与此同时加大了对不当基金发行的打击力度。
About half of Australia’s A$200 billion ($140 billion) private debt market is linked to real estate, making it vulnerable to the deepening property slump. Bathla Group, a Sydney developer, went into insolvency in August owing A$3.4 billion largely to private debt managers. Regulators have meanwhile intensified a crackdown on improper fund offerings.
Corval Avenue Ltd.房地产基金经理首席运营官Belinda Bible表示:“市场的泡沫正在消退。银行在向私募信贷基金放贷时更加挑剔,而流动性的减少可能会带来麻烦,因为有迹象表明投资者也在收紧。”知情人士称,银行在最近几个月已开始转变,包括收紧贷款条件以及在对资金使用方式拥有发言权的情况下阻止交易。高盛和瑞银的代表均拒绝置评。
“The froth is coming out of the market,” said Belinda Bible, chief operating officer of real estate fund manager Corval Avenue Ltd. “Banks are being more selective in lending to private credit funds and that reduction in liquidity could be troublesome given signs investors are also pulling back.”The banks have been making this shift in recent months, which includes tightening lending terms as well as blocking deals in instances where they have a say in how the money is used, the people said. Representatives for Goldman Sachs and UBS declined to comment.
不只是大型银行。据熟悉该行业务的人士透露,总部位于墨尔本的专注于服务中小企业的专业贷款机构Judo Bank,如今在与私人信贷基金开展贷款合作时也变得更加审慎。Judo银行今年8月曾透露,目前其通过九个贷款项目提供的仓储式贷款总额约为4.45亿澳元,且后续还有大量新业务机会在洽谈中。该行拒绝对其当前的业务策略发表评论。
It’s not just the big banks. At Judo Bank, the Melbourne-based specialist lender to small and medium sized businesses has also become more selective in the lending deals it pursues with private credit funds, according to people familiar with the bank’s work. Judo said in August its warehouse lending was around A$445 million across nine facilities, and it has a strong pipeline of new opportunities. The bank declined to comment on its approach.
澳大利亚一家私人信贷基金管理公司的高管表示,过去一个月里他没有接到过任何一家银行主动联系、希望提供债务仓储式贷款服务的电话。相比之下,过去几年里他每周通常都能接到两到三个此类电话。
One executive at a private credit fund manager in Australia said he hasn’t received a single call in the past month from banks wanting to offer debt warehouse facilities. This compares with the usual two or three calls a week he had typically gotten over the past few years.
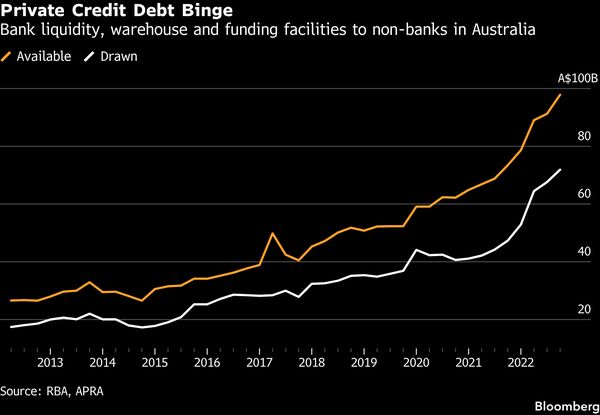
目前很难准确估算针对私人债务基金的贷款规模,但可以确定的是这一市场正在迅速扩张。澳大利亚储备银行与澳大利亚审慎监管局的统计数据显示,截至2022年底,面向非银行机构提供的仓储式贷款及融资服务总额已达980亿澳元,这一数值在过去十年间持续攀升。不过此后几年市场增长最为迅猛的阶段,目前尚无最新的统计数据可供参考。
An accurate size of current lending to private debt funds is hard to gauge, though it’s clear the market has ballooned. Data compiled by the Reserve Bank of Australia and Australian Prudential Regulation Authority show warehouse and funding facilities provided to non-banks reached A$98 billion at the end of 2022, having steadily risen over a decade. There aren’t updated figures that capture some of the market’s busiest growth years after that.
据安永-帕特农咨询公司统计,2025年澳大利亚私人债务资产管理规模已大幅增至2340亿澳元。这一增长势头既源于国内银行向高风险领域放贷的监管限制日益严格,也得益于大量投资者资本涌入、寻求高收益的固定收益类投资机会。
Private debt assets under management in Australia have risen sharply to hit A$234 billion in 2025, according to data compiled by EY-Parthenon. The expansion reflects tighter regulations on domestic banks lending to the higher-risk space as well as an influx of investor capital chasing high-yielding fixed income opportunities.
对于国际性大型银行而言,其向私人信贷基金提供的贷款服务类型十分多样:既有帮助基金获取银行资金用于投资项目的债务仓储式贷款;也有以贷款组合作为抵押物的净值贷款(即所谓的“后杠杆”服务);此外还有专项信贷额度以及A/B票据贷款——即银行将一笔贷款拆分为两部分,把风险较高的部分交由私人信贷基金承担。
For the global banks, their lending spans debt warehouse facilities that let funds access bank capital to deploy for deals, net asset value lending — also known as back leverage — where funds borrow against a portfolio of loans, to specialist credit lines and A/B note lending, where banks split a loan in two and leave the riskier portion for the private credit fund.
此类交易通常不会对外公开。不过,彭博新闻社统计的过去五年间已公布的交易案例显示,其总额超过29亿澳元。其中较为典型的交易包括:高盛和摩根士丹利牵头为帕拉斯资本公司提供的两笔各达5亿澳元的仓储贷款;渣打银行为 Metrics Credit Partners 提供的5.135亿澳元循环信贷额度;以及瑞银为 Centuria Bass Credit 提供的2亿澳元仓储贷款承诺。
Deals are not typically publicized. However, some announced transactions in the past five years compiled by Bloomberg News show they exceed A$2.9 billion. Notable ones include two separate A$500 million warehouse offerings led by Goldman Sachs and Morgan Stanley to Pallas Capital, a A$513.5 million Standard Chartered Plc. revolving credit facility for Metrics Credit Partners, and a A$200 million UBS warehouse facility commitment for Centuria Bass Credit.
“银行青睐这类贷款业务,因为它们能在风险相对较低的情况下带来可观收益,”圣经说道,“私募信贷基金则可借助这些贷款扩充资本规模,进而提升整体投资回报。”这种融资结构决定了除非作为贷款抵押的资产价值大幅缩水,否则银行不太可能在这些交易中蒙受损失。由于银行在资本结构中处于优先地位,只有当基金投资者遭受损失后,银行才会面临风险。
“Banks like these facilities because they provide attractive income at a relatively low risk,” Bible said. “Private credit funds can use these facilities to increase their capital base, which can boost their overall returns.”The structure of the financing means banks are unlikely to lose money on the deals unless the assets that secure the underlying loans fall sharply. The banks sit atop the capital structure, meaning the fund’s investors incur losses before them.
此类安排能为银行带来可观的资本回报率。据多位了解相关业务的人士透露,此类贷款的利率通常比基准利率高出100至650个基点,其中350个基点左右属于常见水平,具体数值视贷款类型而定。如此优厚的收益条件使得银行往往积极劝说私募信贷基金申请此类仓储贷款,并希望它们能尽快动用贷款额度。
Such arrangements can deliver an attractive return on capital. Interest charged on the debt is usually between 100 and 650 basis points above the cash rate, although around 350 basis points above the cash rate is a typical level, depending on the type of lending, according to multiple people briefed on the offerings. The lucrative terms mean banks often encouraged private credit funds to sign up for the warehouse facilities and were keen for them to be drawn down, the people familiar said.
不过,近期银行对私募信贷基金的态度有所转变,这进一步反映出该行业正面临诸多挑战,整体氛围趋于谨慎。目前利率水平处于15年来的高位,央行也发出信号称可能继续加息。由于此类交易大多采用浮动利率机制,这必然导致借款方向私募信贷基金支付的利息成本上升。与此同时,房地产市场的低迷也拖累了房屋销售表现,那些大量从非银行金融机构举债的房地产开发商因此深受影响,巴特拉集团的破产便是例证。
The shift in tone among banks lending to private credit funds is a further sign of caution for a market facing several challenges. Interest rates are at a 15-year high and the central bank has warned further hikes may come. This increases the amount borrowers must pay to private credit funds given deals are typically executed on a floating rate basis. Meanwhile, a housing downturn has weakened home sales for property developers that borrowed heavily from non-bank lenders, as shown in the case of the collapsed Bathla Group.
根据基金评级机构 Zenith Investment Partners 的收入研究主管 Dugald Higgins 的观点,如果投资者开始赎回他们在私人信贷领域的投资,银行此时退出该领域可能会给市场带来流动性压力。“从根本上来说,这其实是一种‘借短钱、投资长期资产’的行为,”他说,“这些金融联系的复杂性往往比人们想象的要高得多。”
Banks pulling back from the private credit sector now could add liquidity stress to the market should investor redemptions materialize, according to Dugald Higgins, head of income research at funds ratings agency Zenith Investment Partners. “We are talking fundamentally about borrowing short and investing long in private markets,” he said. “The pervasiveness of the linkages are always a little bit further than you thought.”