法国债务动荡带来的冲击尚未反映在该国短期融资市场上,这表明目前尚不会出现全面的信贷危机。
The shock from turmoil in French debt has yet to show up in the country’s market for short-term funding, signaling a broad credit crisis is off the cards for now.
尽管法国主权债券的急剧抛售引发了对危机蔓延的担忧,但幕后交易商并未在回购市场中看到资金获取能力受到压力的迹象。这一情况既有积极的一面,也有消极的一面——它表明金融体系的基础运作正常,但也意味着一旦出现裂痕,局势仍可能大幅恶化。
While the sharp selloff in France’s sovereign bonds has raised fears of contagion, behind the scenes traders are seeing no signs of stress in the ability to get cash in the repo market. That’s both good and bad — it shows the financial system’s plumbing is working, but also that things could still get a lot worse if cracks do appear.
距离明年该国关键的总统选举仅剩六个月,对冲基金不愿冒任何风险,纷纷抛售债券,加剧了市场动荡。如果有任何迹象表明它们获取回购资金以覆盖头寸的能力正在恶化——就像疫情爆发时那样——那就预示着情况将变得严重得多。
With six months to go before the country’s pivotal presidential elections next year, hedge funds are not taking any chances and have been offloading bonds, exacerbating the turbulence. Any evidence of a deterioration in their ability to get repo funding to cover their positions — as seen when the pandemic broke — would herald a much more serious situation.
“真正的债券危机初期阶段将首先出现在回购市场,因为大量交易都集中在那里,”法国国民银行(Natixis)的利率策略师Benoit Gerard表示。“这将是法国出现重大问题的早期信号之一。”回购市场是机构以政府债券为抵押向其他机构借入现金,用于杠杆交易的市场。随着对冲基金活动的活跃,回购市场的重要性日益提升,因此它既是压力迹象的关键指标,也是监管机构为避免下一次危机而重点关注的领域。
“The early stage of a real bond crisis will occur on the repo market because this is where a lot of the business is going on,” said Benoit Gerard, a rates strategist at Natixis. “That would be one of the early signals of something big happening on France.”Repo markets are where institutions borrow cash against government bonds to finance leveraged trades. They’ve grown in importance alongside hedge fund activity, making them a key indicator for signs of stress and a focus for regulators seeking to avoid the next crisis.
法国央行在6月发布的一份金融稳定报告中警告称,非银行机构参与度上升、高杠杆以及少数企业的高度集中正在增加系统性风险。报告指出,少数大型银行处于回购中介的核心位置,而它们越来越多的资金正流向采用“高度杠杆套利策略”的对冲基金。
France’s central bank warned in a June financial stability report that rising non-bank participation, high leverage and concentration among a small number of firms were increasing systemic risks. A handful of major banks sit at the center of repo intermediation, and more of their funding is flowing to hedge funds running “highly leveraged arbitrage strategies,” it said.
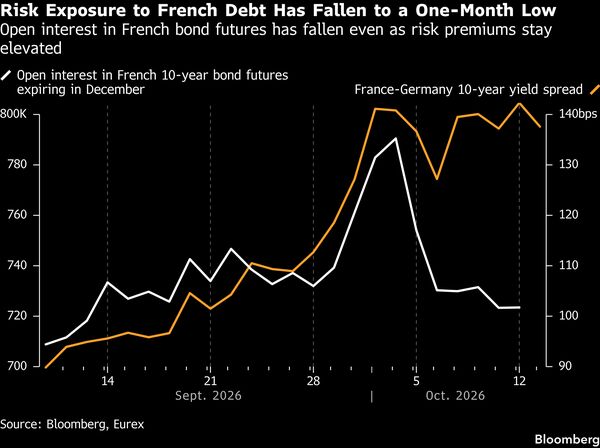
法国央行表示,如果流动性枯竭,这种结构可能会放大压力,触发“剧烈价格波动”,并产生“向更广泛金融体系的传染渠道”。根据摩根大通资产管理公司首席投资官Iain Stealey的说法,在这种情况下,“高度集中的杠杆交易平仓”导致法国国债利差扩大。
That structure could amplify stress, trigger “sharp price swings” and create “contagion channels to the broader financial system” if liquidity dries up, the Banque de France said. In this case, the “unwinding of very concentrated levered trades” caused France’s bond spreads to blow out, according to Iain Stealey, chief investment officer at J.P. Morgan Asset Management.
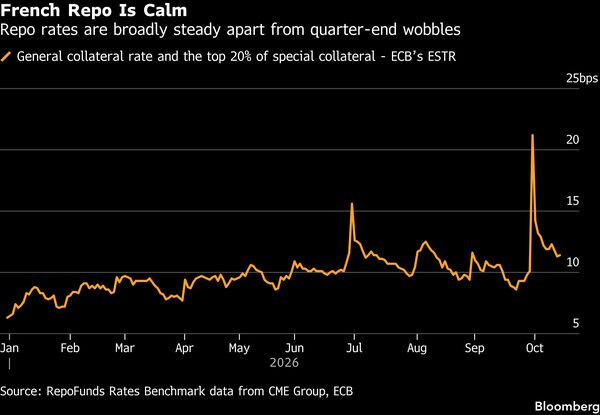
尽管过去几周法国回购活动也有所增加,且回购利率曾短暂飙升,但根据CME Group的数据,此后已回落至约12个基点,仅略高于三个月平均水平。这是指将资金安全存放于央行的成本,与以法国国债作为抵押品进行贷款并获得回报的成本之间的差额。
While there’s also been heightened French repo activity over the past few weeks and a brief spike in repo rates, they have since calmed down to around 12 basis points, only slightly above the three-month average, according to the CME Group data. That’s the cost of depositing funds safely with a central bank versus lending and getting a French bond as collateral.
巴克莱银行欧洲利率策略主管Rohan Khanna表示:“这种稳定表明这不是‘抢夺现金’。”
“The stability suggests it’s not a dash for cash,” said Rohan Khanna, head of European rates strategy at Barclays Plc.
TreasurySpring机构现金管理平台交易与执行主管Glen Stone表示,回购利率一直“保持稳定”,因为它反映了债券在几天内能否通过发放haircut或面临保证金追加来融资,“而且目前没有人在争论”法国信用度在未来一周的风险。他同时表示,相反,国债抛售反映的是未来几年的财政风险。
Repo has stayed “anchored” as it reflects whether bonds can be financed against a haircut or margin calls over days, and “nobody is debating” the risk to French creditworthiness over the next week, said Glen Stone, head of trading and execution at institutional cash management platform TreasurySpring. Meanwhile the selloff in bonds instead reflects fiscal risk over coming years, he said.
Stone表示,真正的考验在于,如果进一步的信用评级下调使法国跌回用于回购抵押品设计的门槛以下。
The real test would be if further credit rating downgrades took France below the thresholds used in repo collateral design, Stone said.
他说:“虽然这在短期内看来不太可能,但这将机械性地缩小能够接受法国抵押品的贷款者池,并提高持有这些债券的成本,届时回购压力可能开始反向作用于债券市场。”
“Whilst this looks unlikely in the immediate term, it would mechanically shrink the pool of lenders able to accept French collateral and raise the cost of holding the bonds, at which point repo pressure could start feeding back into the bond market,” he said.
惠誉评级去年将法国主权信用评级下调至A+,这一水平已被标普全球评级所匹配。穆迪评级目前仍对法国给出更高的信用评分,但计划在本月晚些时候发布可能的更新。
Fitch Ratings downgraded France last year to A+, a level that rival S&P Global Ratings has since matched. Moody’s Ratings still has a higher credit score on the country, but is scheduled to offer a possible update later this month.
惠誉公司西欧主权业务负责人费德里科·巴里加-萨拉扎尔将法国2027年的最新预算提案描述为控制该国赤字的有意义的尝试,但警告称,如果该提案未能通过,将面临不利后果的风险。国际货币基金组织也表示,法国必须确保其预算法案“及时获批”,以提振市场信心。
Fitch’s head of western Europe sovereigns Federico Barriga-Salazar described France’s latest budget proposal for 2027 as a meaningful attempt to tame the country’s deficit, but warned it risks adverse consequences if it doesn’t pass. The International Monetary Fund also said France must ensure “timely approval” of its budget bill to bolster market confidence.
本周,该国议会正就预算进行辩论。在过去两年中,曾两次因类似计划推翻总理的反对派团体不愿妥协。即使这一次获得通过,人们对该国财政的担忧也可能持续到2027年总统大选乃至之后。
Debates over the budget are underway this week in the country’s fractured parliament. Opposition groups that have twice toppled prime ministers over such plans in the last two years are reluctant to compromise. Even if it’s approved this time, worries about the country’s finances are likely to drag on through the 2027 presidential election and beyond.
这为市场再次动荡留下了充足空间。如果投资者开始撤回将法国国债作为抵押品的使用,这将表明出现严重危机,联邦赫尔墨斯公司6800亿美元流动性市场业务首席投资官德博拉·坎宁安如此表示。目前市场尚未达到这一程度。
That leaves plenty of scope for things to flare up again in markets. If investors begin pulling back from using French bonds as collateral that would signal a serious crisis, according to Deborah Cunningham, chief investment officer of the $680 billion liquidity markets business at Federated Hermes. That’s a point the market is not close to yet.
“目前尚未达到全面爆发的程度,但确实是信任危机,”坎宁安说。“全面爆发的危机将表现为你开始看到一些更具量化的统计数据,这些数据反映出目前更多的是情绪因素。”
“It’s not full-blown, but definitely a crisis of confidence,” Cunningham said. “The full-blown crisis would be when you start to see some of the more quantitative statistics reflecting what is more sentiment at this point.”