全球养老金体系正面临人口危机,随着预期寿命延长和出生率下降,退休金融面临被拉紧的风险,引发对其能否为后代持续发放养老金的质疑。
The world's pension systems are confronting a demographic crisis as longer lifespans and dwindling birth rates threaten to stretch retirement finances, raising questions about their ability to sustain payouts for future generations.
养老金计划通常分为两大类:确定给付计划,承诺向退休人员支付预先确定的收入;以及确定缴费计划,给付金额取决于累积储蓄和投资回报。
Pension offerings generally fall into two categories: defined-benefit plans, which promise retirees a predetermined income, and defined-contribution plans, where payouts depend on accumulated savings and investment returns.
人口老龄化给这两种体系带来不同挑战:确定给付计划因退休人员寿命延长而面临不断攀升的负债,而确定缴费计划的参与者则面临活得比储蓄久的风险,这给基金的投资表现带来了更大压力。
Ageing poses different challenges for the two systems: defined-benefit schemes face mounting liabilities as retirees live longer, while defined-contribution members risk outliving their savings, placing greater pressure on funds' investment performance.
国际养老金管理中心执行总监塞巴斯蒂安·贝特米耶表示,这个问题“非常巨大,而且随着时间的推移变得更加突出”,他指出一些养老金基金拥有退休近半个世纪、年龄达107岁或108岁的成员。
The problem is "huge, and it's gotten more pronounced over time,” said Sebastien Betermier, executive director at the International Centre for Pension Management, noting that some pension funds have members who have been retired for nearly half a century, aged aged 107 or 108.
他说:“寿命越长,养老金基金需要覆盖的年限就越多,这立即转化为额外负债。想想这实际上给下一代带来的成本……这是一个定时炸弹。”贝特米耶对CNBC表示。
"The higher the longevity, the more years the pension funds have to cover, and so that immediately comes in as an additional liability," he said. "Think about the cost that it imposes actually on the next generation … it is a ticking time bomb," Betermier told CNBC.
上周二发布的2026年美世CFA协会全球养老金指数(MCGPI)报告赤裸裸地展示了挑战的规模。该指数涵盖的55个养老金体系中,有43个的生育率低于每名妇女2.1个孩子的更替水平,其中23个甚至低于1.5。
The scale of the challenge is laid bare in the 2026 Marsh CFA Institute Global Pension Index, or MCGPI, report published Tuesday last week. Of the 55 pension systems covered by the index, 43 have fertility rates below the replacement level of 2.1 children per woman, while 23 have rates below 1.5.
同时,发达地区65岁人群的预期寿命自1950年以来增加了50.9%,达到约20年,意味着退休福利现在必须维持更长的时间。潜在劳动力支持老年人的比例也将大幅下降。
Meanwhile, life expectancy at age 65 in more developed regions has increased by 50.9% since 1950 to about 20 additional years, meaning retirement benefits must now last considerably longer. The number of potential workers supporting older people is also set to decline sharply.
“随着工人与退休人员的比例持续下降,未来养老金和养老护理的资金筹措变得更为关键,”MCGPI报告指出。“就目前的运行方式而言,极少有体系是安全的。”这一问题对于现收现付制养老金体系尤为严峻,在这类体系中,当前工人的缴费主要用于支付现有退休人员的福利,使其特别容易受到劳动力萎缩的冲击。
“The funding of future pensions and aged care both become more critical as the ratio of workers to retirees continues to decline,” the MCGPI report stated. “Very few systems, as they currently operate, are secure.”The problem is particularly acute for pay-as-you-go pension systems in which contributions from today's workers largely fund benefits for current retirees, leaving them especially vulnerable to a shrinking workforce.
这种压力在美国已显现出来。根据其最新受托人报告,为数千万美国人提供退休和遗属福利的老年及遗属保险信托基金,预计将在2032年第四季度耗尽储备。
The pressures are already evident in the U.S., where the Old-Age and Survivors Insurance Trust Fund, which finances retirement and survivor benefits for tens of millions of Americans, is projected to exhaust its reserves in the fourth quarter of 2032, according to its latest trustees' report.
“每个人都在力所能及的范围内转移更多风险。随着这种人口结构变化,成本正在上升。”波士顿学院退休研究中心的Jean-Pierre Aubry表示。完全积累制养老金计划——即投资工人和雇主的缴费以支付未来退休福利——也无法幸免。
Everybody is shifting a little more risk where they can. The costs are going up with this demographic shift. Jean-Pierre AubryCenter for Retirement Research at Boston College Fully funded pension schemes, which invest contributions from workers and employers to finance future retirement benefits are not immune either.
MCGPI警告称,随着成员退休并开始领取福利,一些基金可能会发现自己支付的福利超过收到的新缴费,迫使它们重新思考投资策略和流动性需求。
As their members retire and begin drawing down benefits, some funds could find themselves paying out more than they receive in fresh contributions, forcing them to rethink their investment strategies and liquidity needs, MCGPI cautioned.
报告强调:“未来的福利流出将超过缴费或保费水平……这种财务压力将不可避免地在未来加剧。”
“Future benefit outflows will exceed the level of contributions or premiums ... this financial strain will inevitably grow in the future,” the report highlighted.
人口危机正在重塑养老基金的投资方式,一些基金为了产生满足日益增长的退休义务所需的回报,开始承担更大风险。
The demographic crunch is reshaping how pension funds invest, with some taking on greater risks to generate the returns needed to meet growing retirement obligations.
许多成熟基金支付的福利已超过收到的缴费,迫使它们越来越多地依赖投资回报和累积资产。
Many mature funds are already paying out more in benefits than they receive in contributions, forcing them to rely increasingly on investment returns and accumulated assets.
根据澳大利亚审慎监管局(APRA)2025年发布的一份报告,澳大利亚约三分之一的养老基金在三年期间内记录了资产负自然现金流,意味着给付金额超过了缴费金额。
In Australia, about a third of superannuation funds recorded negative natural cash flows from assets over a three-year period, meaning benefit payments exceeded contributions, according to a 2025 report by the Australian Prudential Regulation Authority.
业内观察人士表示,追求更高回报的压力促使一些基金转向风险更高、更复杂的投资,包括私募股权、基础设施和私募信贷。
Industry watchers say the pressure to generate higher returns has pushed some funds toward riskier and more complex investments, including private equity, infrastructure and private credit.
“你可以尝试在投资上赚取更高回报,但这将要求承担更高水平的风险,”Betermier说。
"You can try to earn higher returns on your investments, but that's going to require taking on greater levels of risk," said Betermier.
波士顿学院退休研究中心州和地方研究副主任Jean-Pierre Aubry表示,养老基金正日益转向风险更高的投资,尽管转变程度在不同市场间差异很大。
Jean-Pierre Aubry, associate director of state and local research at the Center for Retirement Research at Boston College, said pension funds were increasingly shifting toward riskier investments, although the extent varied considerably across markets.
“我认为大家都在力所能及的范围内略微增加风险敞口。随着这种人口结构变化,成本正在上升,”Aubry说。
"I think everybody is shifting a little more risk where they can. The costs are going up with this demographic shift," Aubry said.
他指出,美国州和地方政府养老基金仅将约20%的资产配置于债券,其余大部分投资于股票和私募资产。
He pointed to U.S. state and local government pension funds, which hold only about 20% of their assets in bonds, with much of the remainder invested in equities and private assets.
他表示,这种资产配置使得美国公共养老基金比其欧洲和加拿大同行面临大得多的投资风险。并非所有养老基金管理者都认为老龄化是加大投资押注的理由。
Such allocations make U.S. public pension funds considerably more exposed to investment risk than their counterparts in Europe and Canada, he said. Not every pension manager sees ageing as a reason to take bigger bets.
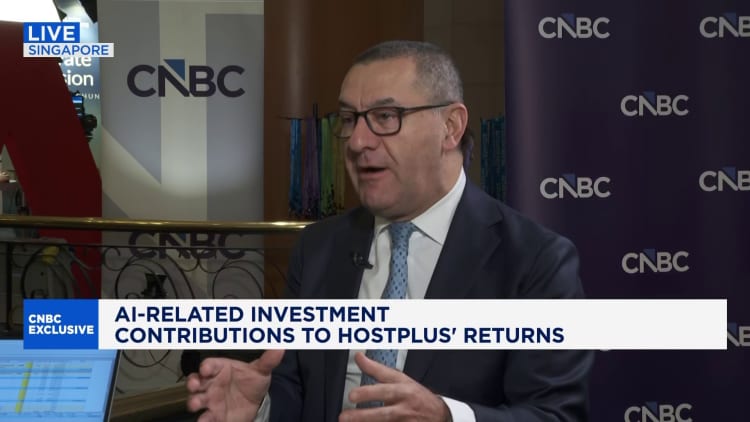
澳大利亚养老基金Hostplus首席执行官David Elias表示,人口结构变化只是影响投资决策的众多因素之一。
David Elias, CEO of Australian pension fund Hostplus said demographic changes were only one of many factors shaping investment decisions.
他强调了在资产类别、地域和行业间保持投资组合多元化的重要性,同时确保潜在回报足以补偿所涉风险。
He stressed the importance of maintaining a diversified portfolio across asset classes, geographies and industries, while ensuring that potential returns adequately compensate for the risks involved.
Elias还表示,政府可以通过移民政策和技术进步等方式缓解人口老龄化带来的压力,而人口结构变化本身也可能创造新的投资机会。
Elias also said that governments could find ways to mitigate the pressures of ageing populations, including through immigration policies and technological advances, while demographic shifts themselves could create new investment opportunities.
“我不低估政府在处理这类问题时表现出的极大创造性,”他说。“你知道,但它们毫无疑问将不得不解决这个问题。”
"I don't underestimate governments being incredibly creative in terms of dealing with these types of issues," he said. "You know, but they're going to have to address it, no doubt about that."