编辑部撰稿大多数美国人缺乏足够的能力来理解他们所遇到的种类繁多的金融产品。许多人在应对发薪日贷款、信用报告或新型支付应用时感到吃力。越来越多的人债务逾期。与此同时,去年因欺诈损失创纪录的160亿美元。如果有一个联邦机构能够被授权保护消费者免受掠夺性金融行为的侵害就好了。
By The Editors Most Americans are ill-equipped to understand the dizzying array of financial products they encounter. Many struggle to contend with payday lenders, credit reports or novel payment apps. A growing share are falling behind on their debt. Meanwhile, a record $16 billion was lost to fraud last year. If only there was a federal agency empowered to protect consumers from predatory financial actors.
事实上,消费者金融保护局(CFPB)正是于2011年成立来完成这一任务的。遗憾的是,CFPB从一开始就被政治左右。上个月在众议院提出的一项新法案,可能最终让该局站在更稳固、更持久的基础上——这将极大惠及消费者。
As it happens, the Consumer Financial Protection Bureau was established in 2011 to do precisely that. Unfortunately, the CFPB has been whipsawed by politics from the start. A new bill, introduced in the House last month, may finally put the bureau on a firmer and more durable footing — to the great benefit of consumers.
在近十五年的时间里,CFPB已向约2亿美国人返还了超过200亿美元,向违法者处以超过50亿美元的罚款,要求在抵押贷款和透支费用上提供更清晰的披露,并帮助消费者及时得到数百万投诉的回应。很少有联邦机构能够拥有如此有效的业绩记录。
Over almost a decade and a half, the CFPB has returned more than $20 billion to some 200 million Americans, levied more than $5 billion in penalties on lawbreakers, required clearer disclosures on mortgages and overdraft fees, and helped consumers get timely responses to millions of complaints. Few federal agencies can boast of a more effective track record.
然而,该局长期以来一直是党派的风向标。民主党政府扩大了该机构的人员规模,并对其职责进行广泛解释,甚至有时出现越权。共和党人则因CFPB的非传统设计和积极执法而提出异议,试图在各个环节阻碍其工作。现任白宫曾尝试完全削减该局的经费。(该努力已被法院阻止。)希望新法案能够结束这种党派循环。
Yet the bureau has long been a partisan weather vane. Democratic administrations have boosted the agency’s staff and interpreted its mandate expansively, at times overreaching. Republicans, objecting to the CFPB’s unorthodox design and aggressive enforcement, have sought to impede it at every turn. The current White House has tried to defund the bureau altogether. (That effort has been blocked in court.) Here’s hoping the new bill can end this partisan cycle.
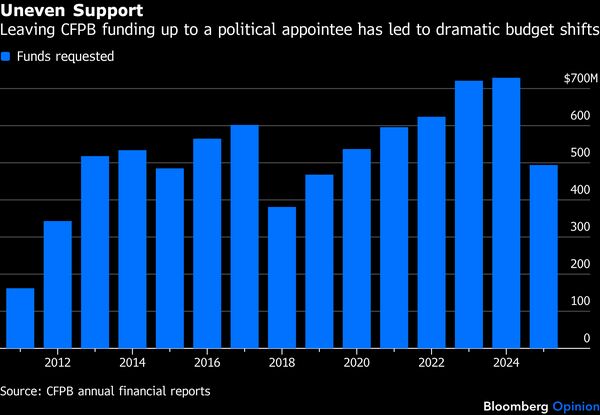
该法案名为《消费者金融保护问责与改革法》,将回应共和党人对CFPB的主要抱怨——即其经费和监督由美联储负责——并将其重新置于正常的国会拨款和监督之下。这是有道理的:一个高效且专注的机构应当能够获得两党对其经费的支持。
Known as the Consumer Financial Protection Accountability and Reform Act, it would address Republicans’ chief complaint about the CFPB — that it was funded and supervised by the Federal Reserve — and bring it back under normal congressional appropriations and oversight. That makes sense: An effective and focused agency should be able to win funding support from both parties.
接下来,该法案将设立一个专门的督察长,这将提高透明度和问责制,并授权管理和预算办公室定期审查重大规则,以确保它们在实践中发挥作用并证明其成本的合理性。此类变革应当能减少繁文缛节和对企业的过度负担,同时遏制政治化的执法。
Next, the bill would create a dedicated inspector general, which would improve transparency and accountability, and empower the Office of Management and Budget to periodically review major rules to ensure they work in practice and justify their costs. Such changes ought to cut down on busywork and excessive burdens on businesses while discouraging politicized enforcement.
话虽如此,该提案也充斥着不必要的限制和例外规定。例如,小额信贷产品往往是最具掠夺性的产品之一,不配享有安全港。大幅降低明知故犯违规行为的最高罚款似乎无济于事。而且,如果消费者的投诉包含不准确之处就威胁以伪证罪起诉他们,这无疑有些手段过激。
That said, the proposal is also larded with unnecessary constraints and carve-outs. For example, small-dollar credit products, often among the most abusive, don’t deserve a safe harbor. A drastic reduction of the maximum penalty for violations that are knowingly committed seems unhelpful. And surely threatening consumers with perjury charges if their complaints contain inaccuracies is a bit heavy-handed.
如果两党都以诚意进行谈判,达成一项妥协法案是完全可以实现的。目标应当是赋予该机构长期的合法性并施加合理的限制,同时也为其提供国会创建该机构时所需的资源和自主空间,以便其履行职责。毕竟,随着市场和技术的快速发展,两党都应认识到需要这样一个能够回应投诉并保护消费者免受金融不当行为侵害的监督机构。
If both parties negotiate in good faith, a compromise bill should be eminently achievable. The goal should be to confer long-term legitimacy on the agency and impose reasonable restraints while also granting it the resources and leeway needed to do the job Congress created it to do. After all, both parties should see the need for a watchdog that responds to complaints and protects consumers from financial misconduct, especially as markets and technology rapidly evolve.
假以时日,消费者金融保护局应当不再是一个政治风口浪尖的焦点,而应成为一个司空见惯的联邦机构,把重要工作做好。美国消费者将是唯一的受益者。
In time, the CFPB should become less of a political lightning rod and more of a humdrum federal agency, doing an important job well. The American consumer would only benefit.