如果美联储在即将召开的货币政策会议上采取更激进的立场,美国国债的看涨押注很容易出现急剧逆转。
Bullish bets in US Treasuries are vulnerable to a sharp reversal if the Federal Reserve takes a more aggressive stance at its upcoming monetary policy meeting.
尽管投资者目前预计美联储周三加息的概率很小,但主席凯文·沃什在通胀等关键问题上的鹰派表态,可能促使他们重新评估央行最终会将借贷成本提高到多高。这势必将引发交易员近期在避险资金涌入国债期间所积累的多头头寸出现痛苦平仓。
While investors are pricing only a slim chance that the Fed will lift interest-rates on Wednesday, hawkish messaging from Chairman Kevin Warsh on key issues like inflation could push them to reassess how high the central bank will ultimately lift borrowing costs. That stands to spur a painful unwind in the long positions traders have amassed during a recent haven rush into Treasuries.
花旗集团策略师戴维·比伯写道:“在联邦公开市场委员会会议之前,最大的变化是市场在战术上转为做多美国国债和欧洲债券。”他补充说,交易员追逐涨幅而建立了看涨头寸,尽管市场在结构上仍处于空头状态。
“Ahead of the FOMC, the big change has been the market flipping into longs tactically in both Treasuries and European bonds,” wrote David Bieber, a strategist at Citigroup. Traders have chased the gains by building bullish positions, even though the market remains structurally short, he added.
芝加哥商品交易所集团的未平仓合约数据显示,过去一周交易员削减了美国国债的空头头寸,同时押注由人工智能交易可持续性担忧和法国债券压力所驱动的涨势将继续。
CME Group open interest data show traders whittling down short positions in Treasuries over the past week while placing bets that the gains — driven by worries over the sustainability of the artificial intelligence trade and stress in French bonds — will continue.
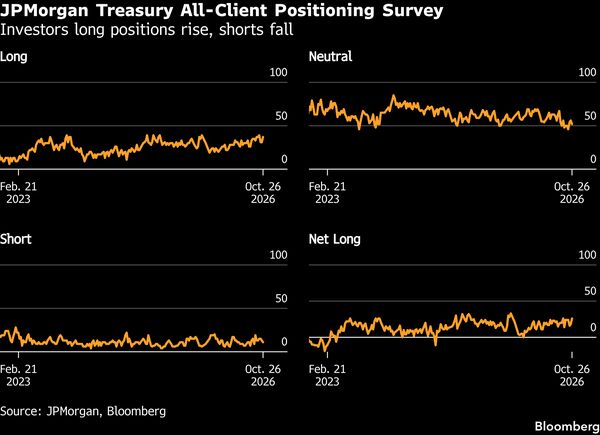
上周五,美国国债期货出现了大规模的头寸削减,尤其是与10年期国债相关的期货。前一天,随着美国国债创下两年多来最佳单日表现,同一期限的国债出现了大量与做多头寸一致的新增风险。与此同时,摩根大通的每周调查显示,净多头头寸处于9月初以来的最高水平。
Huge position reductions across Treasury futures, especially in those tied to the 10-year note, were seen on Friday. The day before, as Treasuries notched their best session in more than two years, the same tenor saw a large amount of new risk consistent with long positioning. JPMorgan’s weekly survey, meanwhile, shows net long positions at their highest level since early September.
“目前阻隔加息与市场定价的唯一因素,就是美联储的指引,”哥伦比亚线针投资公司投资组合经理埃德·阿尔-侯赛尼表示。“如果会议室内的意见发生变化,更有可能朝着加息的方向转变。”国债反弹将基准10年期收益率推低至5%左右,扭转了2025年大部时间占主导的看跌趋势。通胀加快迹象和油价高企本月早些时候曾将10年期收益率推升至5.36%,为逾二十年来最高水平。掉期定价显示,10月加息概率约为8%,12月加息概率则超过90%。
“The only thing standing between a hike and what markets are pricing at the moment is guidance from the Fed,” said Ed Al-Hussainy, portfolio manager at Columbia Threadneedle. “If there’s a change of opinion in the room, it’s much more likely to move in the direction of a hike.”The rally in Treasuries has taken the benchmark 10-year yield down to around 5%, reversing a bearish trend in place for most of 2025. Signs of quickening inflation and elevated oil prices lifted the 10-year yield to 5.36% earlier this month, its highest level in more than two decades. Swaps are pricing in a roughly 8% chance for a rate increase in October and more than 90% for one in December.
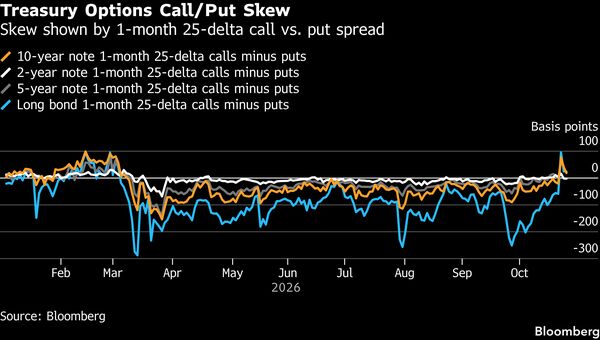
期权市场交易员纷纷买入保护以应对收益率进一步下行,推高期权对冲成本至去年3月以来最高水平。
Traders in the options market have rushed to protect their portfolios against a further move lower in yields, driving the cost of options hedges to their highest level since March last week.
许多对冲涉及买入各类看涨期权结构——部分瞄准未来几周10年期收益率下行至4.6%左右。期权看涨-看跌偏度大幅向看涨期权倾斜,显示交易员现在为对冲收益率下行支付的溢价高于对冲收益率上行。以下是过去一周利率市场持仓指标概览:截至10月26日当周,投资者多头头寸上升6个百分点,中性头寸下降4个百分点,空头头寸下降2个百分点。直接多头头寸现处于一个月来最高水平,净多头头寸则为9月8日以来最多。
Many hedges have involved the purchase of various call option structures – some targeting a move lower in the 10-year yields over the coming weeks to around 4.6%. The options call-put skew has moved sharply to favor calls, signaling traders are now paying a premium of hedging lower yields versus higher yields. Here’s a rundown of positioning indicators across the rates market over the past week: In the week to Oct. 26, investor long positions rose 6 percentage points, with neutrals dropping 4 percentage points and shorts falling 2 percentage points. The outright long positions are now at the greatest in a month while the net long position is the most since Sept. 8.
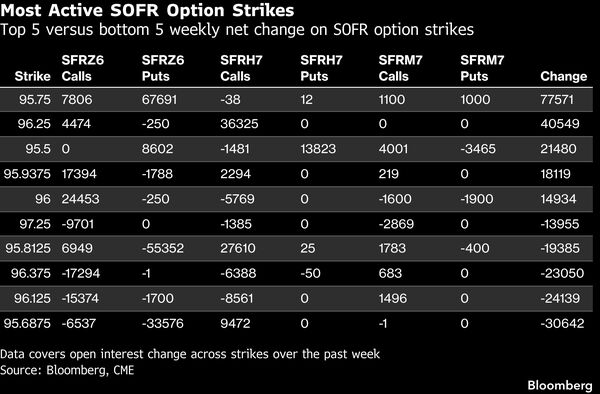
在SOFR 2026年12月、2027年3月和2027年6月期权中,过去一周通过2026年12月95.75看跌期权新增了大量风险敞口,而近期流入包括一名在2027年3月96.25看涨期权买入约3万份新增风险敞口的直接买家,推高了该行权价的未平仓合约。
Across SOFR Dec26, Mar27 and Jun27 options, there was a large amount of new risk added over the past week via Dec26 95.75 puts, while open interest also rose in the 96.25 Mar27 calls after recent flows including an outright buyer in the strike in around 30k for new risk over the past week.
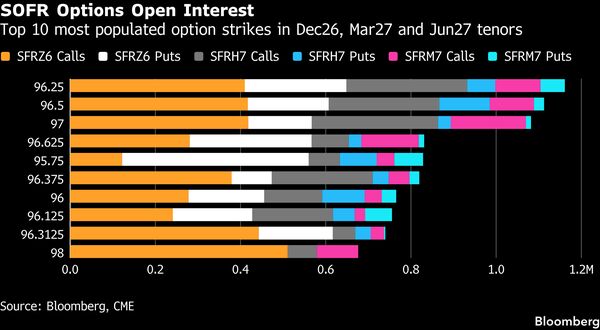
96.25 行权价在 2026 年 12 月、2027 年 3 月和 2027 年 6 月期权中仍是持仓量最大的行权价,其中 2026 年 12 月和 2027 年 3 月合约在该行权价的未平仓合约处于高位。在 2027 年 3 月期权中,仍存在大量看涨头寸,体现为 SFRH7 96.25/97.00 2x3 看涨价差组合,这些组合在过去几周内被买入。上周还出现了约 4 万份 2027 年 3 月 96.25 看涨期权的直接买入,未平仓合约显示这也是新增风险敞口。
The 96.25 strike remains the most populated across Dec26, Mar27 and Jun27 options with Dec26 and Mar27 open interest elevated in the level. In the Mar27 options, there remains a heavy upside position via SFRH7 96.25/97.00 2x3 call spreads which have been bought over the past couple of weeks. Last week also saw a buyer of Mar27 96.25 calls outright in around 40,000 which open interest also showed as new risk.
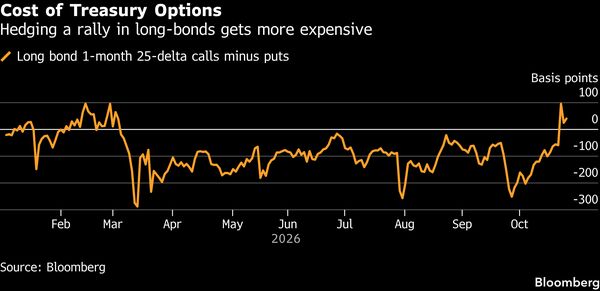
对冲国债期权的权利金在过去一周已由看跌期权转为看涨期权更贵,表明交易员为对冲国债上涨、收益率从当前水平下行的风险,支付的价格高于对冲债券市场抛售的风险。在长期国债期货中,对冲看涨期权的权利金上周升至 2 月以来最高水平。
The premium to hedge Treasury options has flipped over the past week to calls vs. puts, signaling traders paying a higher price to hedge a rally in Treasuries and lower yields from current levels over a bond market selloff. In the long-bond futures, premium to hedge calls last week reached the highest since February.