万亿美元级别的首次公开募股(IPO)或许占据了头条,但对于那些并非 Anthropic 或 SpaceX 这样公司而言,通往公开市场的道路显得不那么确定。那些已花费数年时间为 IPO 做准备的公司,可能不得不等待更长时间才能上市,因为市场环境再度发生变化。
Trillion-dollar-plus IPOs may be stealing the headlines, but for companies hoping to launch that aren’t Anthropic or SpaceX, the path to public markets looks less certain. Companies that have spent years getting IPO-ready may have to wait longer to launch as market conditions shift yet again.
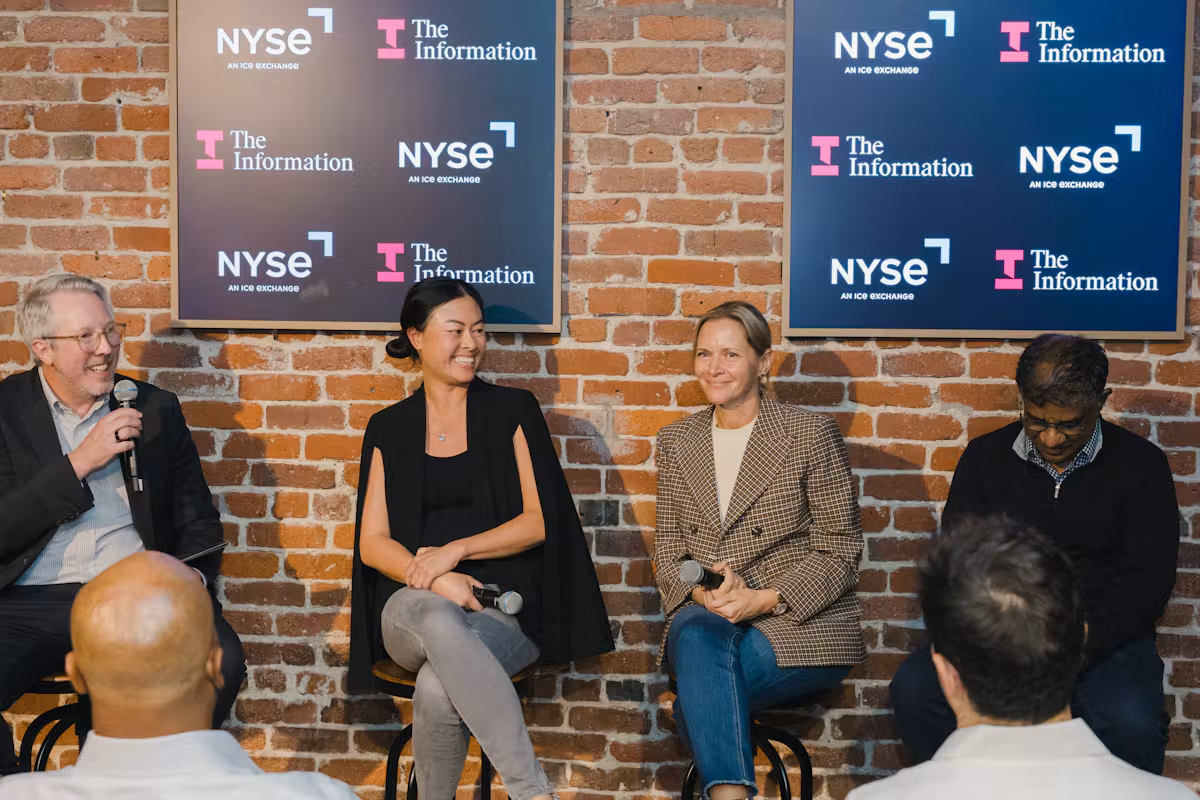
为了探讨企业如何在难以预测的环境下为 IPO 做准备,记者 Dakin Campbell 采访了三位投资专家,了解通往上市的漫漫长途。
To explore how companies can prepare for an IPO in an unpredictable climate, reporter Dakin Campbell spoke to three investment experts about the long road to going public.
做好准备之路 Kate Claassen 表示,成功的 IPO 应该是“与市场无关”的。
The Road to Readiness Successful IPOs, said Kate Claassen, should be market-ambivalent.
她说:“这更多关乎在市场上涨和下跌的日子里,都能成为一家成功的上市公司。”她补充道,成功意味着在战略以及指向战略奏效的指标上,与投资者达成一致。
“It’s more about being a successful public company on days when markets go up and when markets go down,” she said, adding that success means having alignment with investors on strategy and the metrics that point to it working.
Kiran Choudary 深知这条路有多长。Rubrik 于 2022 年底开始为 IPO 做准备,却直到 2024 年初才上市,中间经历了 IPO 市场的长期低迷。Choudary 将准备工作分为三个阶段。
Kiran Choudary knows first hand how long the road can be. Rubrik began preparing for an IPO in late 2022 but didn’t go public until early 2024, after a prolonged slowdown in the IPO market. Choudary broke preparation into three stages.
第一阶段是业务层面的准备:拥有规模、高管团队和持久的增长故事,以吸引投资者。第二阶段是财务与风险基础设施,包括干净的审计报告和审计委员会。第三阶段是 IPO 流程本身:与美国证券交易委员会、投行和律师合作,并与投资者“试水”。
The first is business readiness: having the scale, executive team and durable growth story to appeal to investors. The second is financial and risk infrastructure, including clean audits and an audit committee. The third is the IPO process itself: working with the Securities and Exchange Commission, bankers and lawyers, and testing the waters with investors.
“自2022年以来,从未真正出现过一个稳固的开放窗口期,”Choudary说。取而代之的是,只有短暂的时期里,少数几家公司上市,随后活动又再度放缓。“如果你想成为一家上市公司,如果你的业务已经准备好,且你对此充满信心,你就必须找到一个合适的窗口期并果断出击。”
“Since 2022, there’s never really been a solidly open window,” Choudary said. Instead, there have been short periods when a handful of companies go public before activity slows again. “If you want to be a public company, if your business is ready and you feel good about it, you have to find a reasonable window and go.”
抢占先机的优势更多公司选择私有化的时间更长,部分原因在于它们有选择在公开市场之外融资和成长。纽约证券交易所(NYSE)的应对方式是更早地介入公司的IPO历程,有时最早从A轮融资阶段就开始介入,让这些公司获得交易所的资源及其2400家上市公司的网络支持。
The Early-Bird Advantage More companies are staying private for longer, in part because they have the option of raising capital and growing outside the public markets. The NYSE is responding by getting involved earlier in companies’ IPO journeys, sometimes as early as Series A, giving them access to the exchange’s resources and its network of 2,400 publicly listed companies.
“很多时候,我们会举办活动,让私营发行人接触到它们公开上市的同行。这意味着接触到潜在的终端市场客户,”Crystal Shen表示。“如果等到最后才与交易所接洽,你会错失良机。”
“A lot of times, we’re hosting events where private issuers can get exposure to their publicly listed counterparts. That’s exposure to potential end-market customers,” said Crystal Shen. “You leave a lot on the table if you wait until the very end to engage with an exchange.”
Claassen表示,投资者同样需要同样的早期关注,她建议公司在路演开始前数年就与主要IPO投资者建立关系。熟悉公司的现有投资者更有可能参与其IPO,并在之后继续保持重要股东地位。
Investors need the same early attention, said Claassen, who advised companies to build relationships with major IPO investors years before a roadshow begins. Existing investors who know a company well are more likely to participate in its IPO and remain significant shareholders afterward.
“数据确实表明,投资者陪伴你的时间越长,他们继续持有的时间也会越长,”她说。
“Data does show that the longer an investor’s been with you, the longer they’re going to stick with you,” she said.
即使是在公司最早的融资轮次中做出的决定,也可能在很久以后产生后果。Shen指出了指数纳入的问题,这可能取决于公司在注册声明中的定位以及有多少股票可供公开交易。例如,不受限制的投资者手中的投票权可能会影响公司入选罗素美国股票指数等指数的资格。
Even decisions made during a company’s earliest funding rounds can have consequences much later. Shen pointed to index inclusion, which can hinge on how a company is positioned in registration statements and how much of its stock is available for public trading. Voting rights in the hands of unrestricted investors, for example, can affect eligibility for indexes such as the Russell US Equity.
“这应该影响你如何构建早期的私募融资轮次,以确保日后拥有适合指数纳入的适当流通股,”Shen说。
“That should shape how you structure some of your private rounds to ensure you have [the] appropriate float for index inclusion down the line,” Shen said.
IPO格局的变化 随着企业在私募市场停留时间更长、融资更多、规模更大后再上市,IPO规模正在变大。投资这些企业的基金规模也在增长。
The Changing IPO Landscape As companies spend longer in private markets, raising more capital and growing larger before going public, IPOs are getting bigger. The funds investing in them are growing, too.
“大型基金变得更大,正在形成这样一个循环,”沈某表示,并指出中小型基金在数量和资产规模上都在下降。这使得小型公司更难吸引机构投资者。乔达里表示赞同,回忆称他在做投行家时,营收1亿至1.5亿美元的软件公司就能上市。
“The large funds are getting larger, and it’s creating this cycle,” Shen said, noting that smaller and mid-cap funds are declining in both number and assets. That makes it harder for smaller companies to attract institutional investors. Choudary agreed, recalling that when he was a banker, software companies with $100 million to $150 million in revenue could go public.
“在科技领域,我认为那种规模的公司上市甚至已经不存在了,”他说。
“In tech, I don’t think that sized company going public even exists anymore,” he said.
压力并不止于IPO。克拉森表示,最大的挑战是上市到解禁期结束之间的波动,这可能冲击员工的税单。沈某补充说,公司如何设计要约收购(即从现有持股人手中回购股份)日后会产生连锁影响。这些计划通常只允许现任员工和某些早期投资者出售,导致其他投资者和前员工只能等公司上市后寻找流动性。她表示,这在IPO前形成了积压的供给。
The pressure doesn’t end at the IPO. Claassen said the biggest challenge is volatility between listing and the end of the lockup period, which can hit employees’ tax bills. Shen added that how companies structure tender offers, in which shares are bought from existing holders, can have repercussions later on. Those programs often let only current employees and certain early investors sell, leaving other investors and former employees to find liquidity once the company goes public. That, she said, creates pent-up supply ahead of the IPO.
“公司和管理团队需要考虑IPO前增加的二级市场活动水平,”沈某说,“以缓解IPO后将面临的一些问题。”
“Companies and management teams need to think about that increased level of secondary activity pre-IPO,” Shen said, “to alleviate some of those issues you’re going to have post-IPO.”