在笼罩欧洲——传染效应的威胁。法国的财政失败正是其根源,如今,那些本应改善财政状况的国家也面临危险。
A specter is haunting Europe — the threat of contagion. France’s fiscal failures are the source, and now even countries that were supposedly improving their finances are in danger.
以意大利为例,该国虽已成功削减财政赤字,但其宏观经济复苏对主权债务收益率的上升极为敏感,而这也直接推高了其借贷成本。多年的财政管理不善,将导致其债务今年达到国内生产总值的139%。欧元区之外也暗藏危机。罗马尼亚在9月30日未能组建政府后,再次陷入政治动荡,其债券收益率约为7.3%。
Italy, for one, has managed to cut its fiscal deficit, but its macroeconomic recovery is very sensitive to rising yields on its sovereign debt — and hence its borrowing costs. Years of fiscal mismanagement will cause its debt to hit 139% of gross domestic product this year. Trouble is brewing beyond the euro zone as well. Romania, going through another bout of political turmoil after failing to install a government on Sept. 30, has yields of about 7.3%.
我们距离2010至2012年欧元区危机的重演仍有一段距离。但欧盟在过去十年中为何不断从一个紧急事件滑向另一个紧急事件?为何每一次压力——2022年俄罗斯天然气供应中断、伊朗战争、法国的过度支出——都似乎可能将其推向崩溃边缘?答案在于,欧盟始终未能趁形势良好时为危机做好准备。
We’re still some distance from a repeat of the 2010-2012 euro zone crisis. But there is a reason why the European Union has for a decade lurched from one emergency to another, and why every moment of stress — the 2022 loss of Russian gas, the Iran war, France’s overspending — threatens to push it over the brink. It has consistently failed in good times to prepare for the bad.
再来看看欧盟一些看似成功的国家。若深入探究,就会发现不负责任的现象比比皆是。意大利实际上正在实现预算盈余,且乔治亚·梅洛尼的政府已执政近四年,让这个以政局动荡闻名的共和国获得了前所未有的稳定时期。然而,她的政府仍在要求放宽欧盟规则,以便增加支出。
Look beyond France at some of the bloc’s apparent successes. When you dig deeper, irresponsibility is rife. Italy is actually running a budget surplus and Giorgia Meloni’s government has stayed in power for nearly four years, giving the notoriously unstable republic an unprecedented spell of stability. But her government is still demanding that EU rules are bent to let it spend more.
那些取得还算不错成绩的国家认为,这给了它们在接下来几年里肆意挥霍的许可——就像节食者以为十分钟的散步就能让他们大快朵颐地吃掉一大桶炸薯条。以捷克共和国为例。其民粹主义亿万富翁领导人宣布了一项预算,将赤字从2025年的2.1%大幅提高到国内生产总值的3.5%。不出所料,该国债券收益率已升至自2022年以来从未见过的水平。
Countries that rack up half-decent numbers reckon that gives them license to be irresponsible for the next few years, like dieters who think a 10-minute walk allows them to wolf down a bucket of fries. Consider the Czech Republic. Its populist billionaire leader has announced a budget that would massively increase the deficit to 3.5% of gross domestic product from 2.1% in 2025. Naturally, its bond yields have reached levels not seen since 2022.
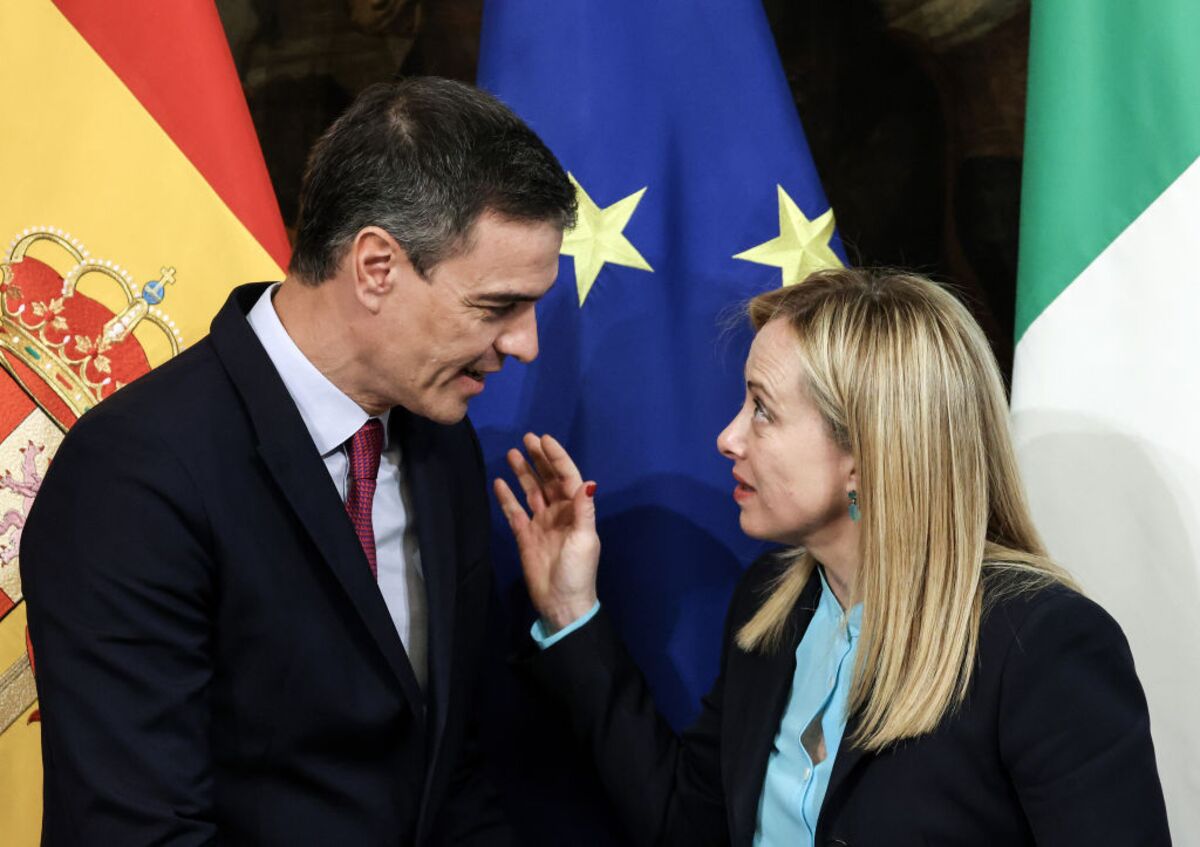
西班牙的情况更令人沮丧。尽管在民意调查中大幅落后,首相佩德罗·桑切斯还是宣布举行新一轮选举。他已连续领导了三个少数派政府,或许正希望奇迹般地赢得第四个任期。西班牙拥有文化契合的西班牙语移民,气候条件也极为适合发展可再生能源,因此经济增长数据表现良好。然而,尽管表面上的财政赤字有所下降,但国家并未真正实现财政巩固。
Spain is even more disheartening. Prime Minister Pedro Sanchez has called fresh elections, although he’s trailing badly in the polls. He has run three successive minority governments now, and perhaps hopes he can pull off an unlikely fourth win. The country is blessed by culturally compatible Spanish-speaking migrants, a climate that’s perfect for renewable energy and favorable growth numbers as a result. But there’s been no real fiscal consolidation, even though the headline deficit has fallen.
经合组织指出,西班牙的结构性赤字——即假设该国以最高可持续增速稳定增长时的赤字水平——并未减少。一旦经济增长引擎开始熄火,西班牙已无余力应对。
The OECD points out that Spain’s structural deficit — what the deficit would be if the country grew steadily at its highest sustainable rate — isn’t declining. There’s nothing in the tank for when the engine begins to sputter.
西班牙正是欧洲问题的典型代表。在危机时期,各国会向欧盟其他国家寻求援助;而在经济繁荣时,却既未为自己、也未为整个欧盟积累任何储备。在这样一个挣扎求存的欧洲大陆上,西班牙非但没有成为力量源泉,反而试图将应对市场的艰巨任务推给他人,甚至提议设立一个欧洲层面的借贷机制,以便代表本国筹集资金。
Spain typifies Europe’s problem. In times of crisis, countries look to the rest of the EU for help. In happier times they bank nothing, for themselves or the bloc. Instead of being a source of strength in a struggling continent, Spain has sought to leave to others the tough job of dealing with markets, suggesting a European-level borrowing facility that could raise money on its behalf.
桑切斯试图推行租金管制——这一提案在议会中被否决,也促使他宣布举行新选举——正是这种倾向的典型表现。住房短缺确实是个严重问题,但他的应对措施却是一种缺乏深思熟虑的民粹主义政策,包括自动续租合同等。真正需要的是切实解决那些使西班牙从金融危机前每年新增80万套住房的建房冠军,沦为“邻避主义”天堂的根本问题。
Sanchez’s attempt to introduce rent controls — which was defeated in parliament, precipitating his call for new elections — is typical. The housing shortage is a real problem, but his response was poorly thought through populism, including the automatic renewal of rental contracts. What’s needed is a genuine attempt to fix the problems that have turned Spain from a housebuilding champion, adding 800,000 a year before the financial crisis, into a NIMBY paradise.
金融市场审视欧洲时,对其现状并不乐观:这个大陆尚未正视人口老龄化及其必然带来的财政紧缩问题。他们确实看到一些增长亮点——如波兰和西班牙——但并未看到足以支撑这种增长可持续性的财政改革。
Financial markets look at Europe and dislike what they see: a continent that hasn’t come to terms with its aging population and the straitened finances that inevitably follow. They see patches of growth — Poland, Spain — but no sign this is being matched by the fiscal reforms that will make this growth sustainable.
政治家无法向选民坦诚说明必要牺牲的真相,而选民即便听到这些实话,也拒绝相信。投资者对民粹主义者那些不真诚且无法兑现的承诺,以及由此引发的动荡感到不满。最重要的是,他们看到整个欧洲大陆都不愿接受那些可能避免经济停滞的福利和移民改革。许多国家甚至拒绝建造新住房,尽管高企的住房成本正在严重制约经济增长,并疏远年轻一代。
Politicians are unable to tell electorates the truth about the necessary sacrifices, and voters refuse to believe it even when they’re told. Investors balk at populists’ insincere and undeliverable promises, and the instability they create. Above all, they see a continent-wide unwillingness to embrace the welfare and immigration reforms that might prevent stagnation. Many countries are refusing to build new homes, too, even though housing costs are crippling growth and alienating the young.
债券市场推动收益率上升也就不足为奇了。欧洲是一个拒绝成熟的老化大陆。它如今的开支方式仿佛正值青春鼎盛,却没有相应的收入能力来支撑这种消费。
No wonder bond markets are pushing yields higher. Europe is an aging continent that refuses to grow up. It’s spending as if it’s in the first flush of youth, without the earning capacity to justify that.