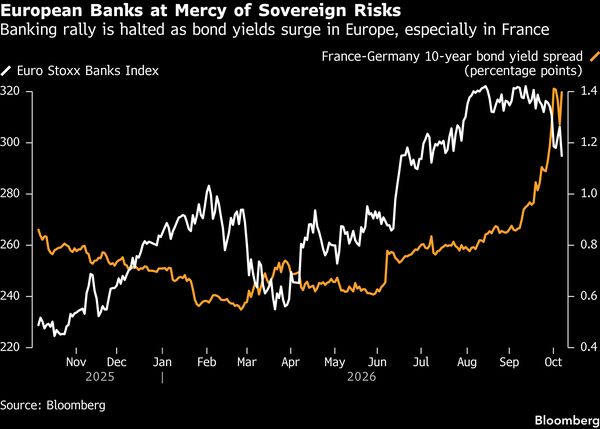
三,欧洲银行业股票再度遭遇抛售。法国兴业银行与德意志银行股价均下跌超过5%。市场对政治动荡的担忧加剧,导致债券收益率上升。
A selloff in shares of European banks resumed on Wednesday, with the likes of Societe Generale SA and Deutsche Bank AG tumbling more than 5%, as mounting fears over political turmoil sent bond yields higher.
欧洲斯托克银行指数一度下跌4%,有望创下近三个月来的最低收盘水平。该指数涵盖法国巴黎银行、法国农业信贷银行及意大利联合信贷银行等金融机构,所有成分股均呈现跌势,令该板块今年以来的部分涨幅化为乌有。
The Euro Stoxx Banks Index fell as much as 4%, putting it on pace to close at the lowest level in about three months. Every stock within the index, which includes lenders like BNP Paribas SA, Credit Agricole SA and UniCredit SpA, was trading lower, as the sector pares back some of its gains on the year.
近期,受法国政府可能倒台及财政赤字再度飙升的影响,欧洲股市持续走低。投资者纷纷抛售法国债券,导致法国与德国10年期国债收益率之差扩大至约140个基点。多重危机正令欧洲央行面临自十多年前欧元区债务危机以来未曾出现过的与投资者的对立局面。
European markets have sold off recently amid France’s prospect of government collapse and another deficit blowout. Investors are particularly responding to the political and economic crises in France by dumping its bonds, with the spread between the yield on French and German 10-year bonds widening to about 140 basis points. The country’s multiple crises are threatening to drag the European Central Bank into the kind of faceoff with investors that it hasn’t seen since the euro area’s debt crisis more than a decade ago.
今年以来,欧洲银行业表现一直优于地区大盘及美国同业。尽管近期有所回调,该板块在2026年仍录得12%的涨幅。此次下跌虽使欧洲银行指数较8月高点回落逾8%,但摩根大通策略师达维德·西尔维斯特里及其团队在周三早些时候发布的报告中指出,这“更像是受市场情绪及仓位调整驱动的避险行为,而非基本面恶化引发的下行趋势”。
Lenders had been outperforming the region’s broader market and US peers this year, and the group remains up 12% in 2026 despite the recent retreat. The latest pullback has taken the European lenders gauge down more than 8% from an August high, but it appears “more like an episode of sentiment and positioning-driven de-risking than the start of a fundamentals-driven downturn,” JPMorgan strategists led by Davide Silvestrini wrote earlier Wednesday in a note.
这些策略师认为当前回调为买入银行股的良机,尤其是法国银行股;他们预计国债收益率不会出现大幅攀升,主权债利差扩大对银行资产负债表的直接影响也相对有限。
The strategists saw the pullback as a good entry point for banks, particularly French lenders, citing a base case for yields not rising substantially more. The direct impacts on balance sheets from the widening in sovereign spreads should be limited, they note.
与此同时,可能产生更大影响的二级效应,例如存款结构的变化以及对资产质量的宏观影响,“主要关乎市场情绪、概率加权以及利差扩大的持续性,而不是对资本或流动性造成直接的机械性冲击。”
The second-order effects that could be more impactful, such as deposit mix changes and macro impacts on asset quality, meanwhile, are “primarily about sentiment, probability-weighting, and the persistence of spread widening, rather than an immediate mechanical hit to capital or liquidity.”