由斯里尼瓦瑟·西瓦巴兰撰写巴林债券的抛售正在将其借款成本推高至2018年危机时期的水平,当时该国的中东富裕盟友介入提供财政救助。
A selloff in Bahrain’s bonds is pushing its borrowing costs to levels last seen during the nation’s 2018 crisis, when its wealthier Middle East allies stepped in with a financial rescue.
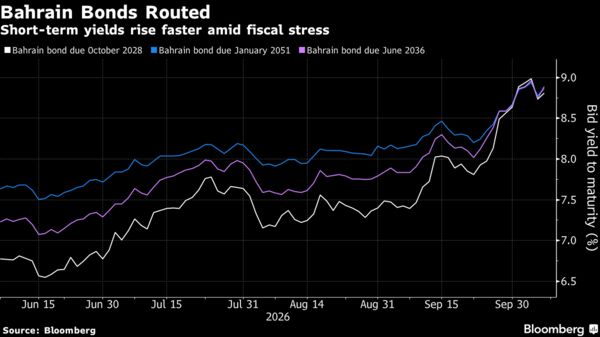
这个负债累累的海湾国家正处于伊朗战争的影响之中,同时美国国债收益率的飙升正推高其债务服务成本。这种组合使到期于2028年的巴林美元债券收益率升至6年来最高的8.99%,自8月底美国国债动荡开始以来上升了1.6个百分点。
The heavily indebted Gulf state is grappling with the fallout from the Iran war just as surging US Treasury yields drive up its debt-servicing costs. That combination has lifted yields on Bahrain’s dollar bonds due 2028 to a six-year high of 8.99%, up 1.6 percentage point since late August, when the Treasury turmoil began.
在此期间,巴林的美元债务成为新兴市场中表现最差的债券之一,下跌了4.2%,而其伊斯兰金融证券苏库克也下跌了3.5%。短期借款成本上升幅度最大,表明投资者正在为更多的近期压力做准备。
Over that period, Bahrain’s dollar debt has been among the worst performers in emerging markets, losing 4.2%, while its sukuk Islamic finance instruments have declined 3.5%. Shorter-dated borrowing costs have risen the most, suggesting investors are bracing for more near-term stress.
这场抛售正在唤起人们对巴林上一次资金紧张的记忆,这次紧张跟在2014年油价下跌之后,并最终促使海湾合作委员会成员国沙特阿拉伯、阿联酋和科威特承诺提供超过100亿美元的支持。投资者表示,GCC可能正在密切关注最新的压力迹象。
The rout is reviving memories of Bahrain’s last funding crunch, which followed the 2014 oil-price slump and ultimately prompted Gulf Cooperation Council members Saudi Arabia, the UAE and Kuwait to commit more than $10 billion in support. Investors say the GCC is likely watching the latest signs of stress closely.
“巴林欧元债的抛售是针对发行人的,超出了新兴市场高收益信用的普遍疲软范围,”迪拜阿尔卡姆资本的固定收益投资组合经理法迪·金迪说。“我们预计在任何大规模且持续的市场疲软情况下,海湘合作委员会的支持将变得更加明确和广泛。”即使在战争之前,巴林就被认为是财政上较为脆弱的新兴市场借款国之一,根据世界银行数据,其预算赤字相当于国内生产总值的10.5%,而公共债务超过140%的GDP。它也是唯一一家从三大主要信用评级机构获得垃圾信用评级的GCC成员国。
“The selloff in Bahrain eurobonds is issuer-specific and extends beyond a general weakness in EM high-yield credits,” said Fady Gendy, a fixed-income portfolio manager at Arqaam Capital in Dubai. “We would expect Gulf Cooperation Council support to become more explicit and broad-based on any large and sustained market weakness.”Even before the war, Bahrain was considered one of the more fiscally fragile emerging-market borrowers, with a budget deficit equal to 10.5% of gross domestic product and public debt surpassing 140% of GDP, according to World Bank data. It’s also the only GCC member to have a junk credit rating from all three major credit rating firms.
战争加剧了紧张局势,扰乱了出口,大幅削减了原油产量,并破坏了基础设施。根据彭博新闻社调查的中位数预测,今年经济可能萎缩6.6%。彭博指数显示,巴林相对于美国国债的主权风险溢价现已远高于战前水平。
The war has deepened the strains, disrupting exports, slashing crude output and damaging infrastructure. The economy could contract 6.6% this year, according to the median estimate in a Bloomberg News survey. Bahrain’s sovereign risk premium over Treasuries is now well above pre-war levels, a Bloomberg index shows.
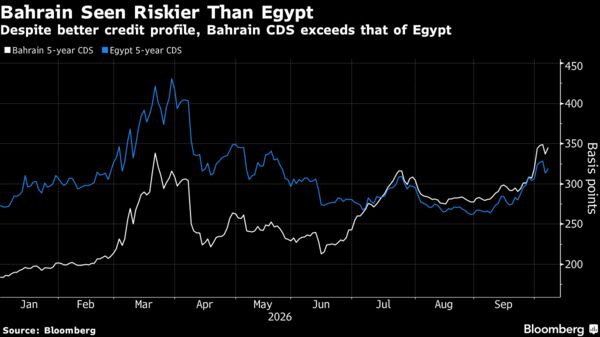
压力主要集中在短期端,2028年到期的债券利差扩大程度超过2035年到期的证券。尽管巴林的穆迪信用评级比埃及高两个等级,但其收益率现已超过埃及,信用违约互换价格也更为昂贵。
The pressure is concentrated at the front end, with spreads on the 2028 issue widening more than on securities due 2035. Bahrain’s yields now exceed Egypt’s despite a Moody’s rating two notches higher, while its credit-default swaps are also more expensive.
投资者表示,该国可能仍然能够进入债券市场,并指出其在6月成功发行了10亿美元债务,而当时仅几小时前该国还遭到了导弹袭击。然而,随着美国国债收益率目前约为5%,而投资者要求额外约3.5个百分点的风险溢价来持有巴林债券,新的发债成本将高得令人望而却步。
Investors say the nation probably still can access bond markets, pointing to its successful $1 billion debt sale in June, just hours after being targeted by missiles. But with Treasury yields now around 5% and investors demanding roughly another 3.5 percentage points to hold Bahrain risk, fresh issuance would be prohibitively expensive.
如果收益率进一步上升,海湾地区的金融支持可能会变得愈发紧迫。
Should yields rise further, a Gulf financial backstop could become increasingly urgent.
“对阿联酋和沙特阿拉伯而言,巴林的安全和地缘政治稳定被视为自身安全的延伸,”观察者研究基金会中东问题研究员马赫迪·古卢姆表示。“严峻的经济状况只会增加巴林不稳定的风险,而这可能对其邻国产生影响。”在海湾合作委员会2018年实施救助之前,巴林的外汇储备已严重枯竭,仅能覆盖1.5个月的非石油进口,国际货币基金组织的数据如此显示。尽管最新数据尚未公布,但该基金在1月份估计,当时的外汇储备仅能覆盖两个多月的非碳氢化合物进口。
“For both the UAE and Saudi Arabia, Bahrain’s security and geopolitical stability is viewed as an extension of their own,” said Mahdi Ghuloom, a fellow at Observer Research Foundation Middle East. “An economically dire situation will only increase the risk of instability in Bahrain, which could have ramifications for its neighbours.”Ahead of the GCC’s 2018 rescue, Bahrain’s hard-currency reserves were so depleted, they covered just 1.5 months of non-oil imports, according to the International Monetary Fund. While the latest figures aren’t available, the fund estimated in January that reserves covered just over two months of non-hydrocarbon imports.
目前,Arqaam公司的根迪预计巴林仍能勉强应对,通过私募、国内融资和苏库克(伊斯兰债券)发行来满足其支付义务。他表示,一旦美国债券市场抛售缓解,期限最短的证券可能会变得更具吸引力。
For now, Arqaam’s Gendy expects Bahrain can muddle through, using private placements, domestic funding and sukuk issuance to meet its obligations. That could make the shortest-duration securities attractive once the US bond selloff eases, he said.
“这提供了一种无需承担大量久期风险即可获取收益的吸引力,”他补充道。
“This is attractive carry to earn without taking extensive duration risk,” he added.