这是固定收益领域最难理解的信号之一,但最近,随着它在市场中重新显现,华尔街的每个人都在热议其含义。
It’s one of the least understood signals in the fixed-income world, but lately, everyone on Wall Street is abuzz about what it means as it reasserts itself in the market.
这就是所谓的期限溢价(term premium),即投资者要求获得的额外回报,以补偿他们持有10年期国债而非通过滚动持有同等期限的短期证券所承担的风险。衡量它的具体方法各不相同,对其波动的解释也莫衷一是。
It’s known as the term premium, or the extra payout that investors demand in return for the risks of owning 10-year Treasuries instead of just rolling over short-dated securities for the same amount of time. How exactly to measure it varies. So do the explanations for its moves.
毋庸置疑的是,在过去几周里,它飙升至十多年来未见的水平,并推动了债券抛售潮的最新一轮行情,将美国国债收益率推向了24年来的高点。反过来,这又加剧了人们对潜在转变的担忧,这种转变将给本已遭受重创的市场带来更大压力,并使整个经济体的借贷成本居高不下。
What’s not in question is that during the past few weeks it spiked to levels not seen in over a decade and drove the latest leg of the bond selloff that’s sent US Treasury yields to a 24-year high. And that, in turn, is fanning fears of a potential shift that will heap pressure on an already battered market and keep borrowing costs elevated across the economy.
期限溢价本质上是对不可预测变动的保护,这些变动范围从地缘政治冲击到政府财政危机,都可能在长期债券到期前冲击市场。
That term premium is essentially protection against unpredictable turns, ranging from geopolitical shocks to government fiscal crises, that could hit the market before long-term bonds come due.
它不同于当前的通胀前景和货币政策走向,后两者也反映在收益率中。由于溢价无法直接观察到,必须通过推断得出,明尼阿波利斯联邦储备银行行长尼尔·卡什卡利(Neel Kashkari)曾将其比作“暗物质”,即物理学家所说的解释某些宇宙奥秘的无形物质。
It’s distinct from the current outlook for inflation and the direction of monetary policy, both of which are also reflected in yields. Because the premium isn’t directly observable and must be inferred, Neel Kashkari, the president of the Federal Reserve Bank of Minneapolis, once likened it to dark matter, the invisible substance physicists say explains some cosmic mysteries.
“计算它的方法有很多种,但它们都在走高,”全球宏观策略主管弗兰克·雷宾斯基(Frank Rybinski)表示,“这告诉我的信息是,这种走势具有持久力。”目前还没有明确的催化剂。由黛米·胡(Demi Hu)领导的巴克莱研究人员表示,宏观经济的不确定性、股票和债券走势之间常规相关性的破裂、债务供应的增加以及对财政政策的担忧,都是影响期限溢价的因素,且可能都在发挥作用。
“There’s multiple ways to calculate it, but they’re all going higher,” said Frank Rybinski, head of macro strategy at Aegon Asset Management. “And what that tells me is that this move has staying power.”There was no clear-cut catalyst. Barclays researchers led by Demi Hu said macroeconomic uncertainty, breakdowns in the usual correlations between stock and bond moves, the rising supply of debt and worries about fiscal policy are all things that figure into the term premium and could be playing a role.
资本经济集团(Capital Economics)的首席经济学家尼尔·希林(Neil Shearing)表示,最近的债券市场波动可能反映了某些技术性因素,比如上月底投资者对投资组合的调整,或是欧洲对法国债务负担日益担忧所导致的副作用。NISA投资顾问公司(NISA Investment Advisors)的首席经济学家斯蒂芬·道格拉斯(Stephen Douglass)指出,信贷市场存在一定的紧张迹象,同时投资者也对在通胀冲击频发的情况下持有固定收益资产的价值产生了怀疑。
Neil Shearing, the group chief economist at Capital Economics, said the recent move could reflect technical factors, like portfolio adjustments at the end of last month, or the side effects of mounting concern in Europe about France’s debt load. Stephen Douglass, chief economist at NISA Investment Advisors, pointed to some indications of stress in credit markets, as well as broader doubts among investors over the benefits of holding fixed-income assets when inflationary shocks are becoming more frequent.
“这并不是一个简单的现象,”道格拉斯警告说,“我们正处于一个长期利率溢价(term premium)不断上升的环境中。”这对债券多头来说是个不利因素——因为较高的长期利率溢价会抑制长期利率的下降,从而阻碍债券市场的复苏。
“It’s not a simple story,” said Douglass, who warned against reading too much into short-term moves. “But I would say that I think we are in a rising term-premium environment.”That’s a worry for bond bulls. A structurally higher term premium could keep long-term interest rates elevated, preventing the market from rebounding from its slump.
根据纽约联邦储备银行(New York Fed)经济学家开发的模型显示:在20世纪90年代,随着全球化进程的加速,长期利率溢价持续下降;到了21世纪10年代,由于各国央行实施量化宽松政策,大量资金涌入全球债券市场,导致长期利率溢价进一步下跌,甚至在2020年3月跌至负1.7%的低点。此后,长期利率溢价逐渐回升至正值区间。在美国于2月底对伊朗发动战争后引发的债券市场抛售潮中,这一指标基本保持稳定。
The metric came down steadily in the 1990s, when increasing globalization was exerting a deflationary force, and fell further still during the 2010s as central banks’ quantitative-easing programs distorted global bond markets by flooding them with cash. It dropped as low as negative 1.7% in March 2020, when investors were rushing for the safety of bonds, before rising consistently into positive territory after late 2024, according to a model created by economists working for the New York Fed. It had remained relatively steady during most of the selloff that started after the US launched its war against Iran in late February.
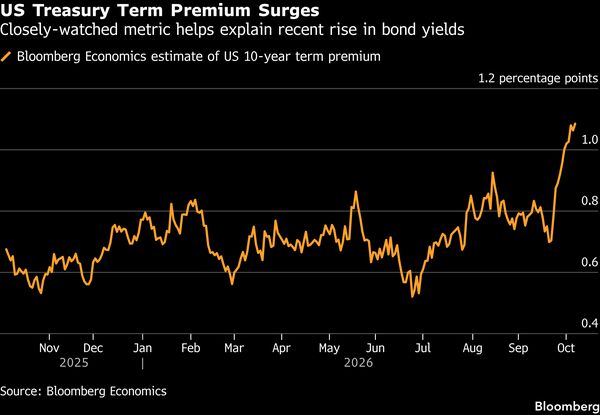
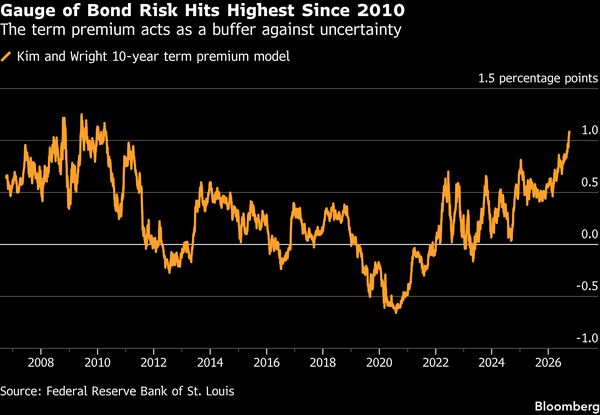
然而到了9月中旬,长期利率溢价开始急剧上升。纽约联邦储备银行的模型显示,该指标上升了约40个基点,达到0.98%的水平,这是自2014年以来的最高值,也足以解释同期10年期美国国债收益率上升近30个基点的原因。彭博经济研究(Bloomberg Economics)的估计结果也显示了类似的趋势;另一项结合了经济学家对美联储政策预测的模型则显示,长期利率溢价已升至1.08%,创下2010年以来的最高水平。
Then, in mid-September, it started surging. The New York Fed model shows it climbed around 40 basis points to about 0.98%, the highest since 2014 and more than enough to account for the nearly 30 basis-point rise in 10-year Treasury yields over that time. Bloomberg Economics’ estimate shows a similar increase. Another, which incorporates economists’ forecasts for Fed policy into the calculation, has climbed to 1.08%, the most since 2010.
这一上涨是在其他价格驱动因素几乎没有变化的情况下发生的。通胀预期一直保持稳定。美联储上个月一致决定加息,平息了一些关于其致力于抑制消费价格的担忧。尽管油价维持在每桶100美元以上的高位,但也一直保持在窄幅区间内。
That break higher came as other drivers of prices were little changed. Inflation expectations have been stable. The Fed’s unanimous decision to raise rates last month quelled some concerns about its commitment to reining in consumer prices. And oil, while elevated at over $100 a barrel, has been holding in a narrow range.
期限溢价的持续上升将加剧市场压力,这些压力源于高通胀、强劲的经济增长,以及企业投资人工智能和全球各国政府赤字带来的大量借贷需求。达拉斯联邦储备银行行长洛里·洛根(Lorie Logan)上周表示,期限溢价上升会推高借贷成本,这可能会减缓经济增长,并降低央行进一步加息的必要性。
A sustained term-premium increase would add to the pressure on the market from elevated inflation, robust economic growth, plus a flood of borrowing from companies investing in artificial intelligence and from deficit-running governments around the globe. Fed Bank of Dallas President Lorie Logan last week said a rising term premium, by pushing up borrowing costs, may slow the economy and reduce the need for the central bank to hike rates.
隆奥资产管理公司(Lombard Odier Investment Managers)宏观研究主管弗洛里安·伊尔波(Florian Ielpo)表示:“债券市场不再等待美联储收紧金融环境。即使短期利率的预期路径变得不那么激进,高期限溢价、通胀不确定性和政府借贷需求仍可能使长期收益率保持在限制性水平。”近期市场波动的一个原因可能是法国债券无序抛售带来的溢出效应。一些人还指出,抵押贷款支持证券持有人的对冲活动可能会暂时放大市场波动。
“The bond market is no longer waiting for the Fed to tighten financial conditions,” said Florian Ielpo, head of macro at Lombard Odier Investment Managers. “High term premia, inflation uncertainty and government borrowing needs can keep longer-dated yields restrictive even when the expected path of short rates becomes less aggressive.”One reason behind the latest moves may be spillover effects from the disorderly selloff in French bonds. Some also point to hedging activity by holders of mortgage-backed securities that can temporarily exaggerate market moves.
然而,其背后可能潜藏着全球经济中不断积累的长期风险。其中之一是,随着地缘政治分歧加剧,能源和其他大宗商品的供应冲击——例如俄罗斯入侵乌克兰以及美国对伊朗的战争之后所发生的情况——可能会变得更加频繁。
Yet behind it may be lurking longer-term risks that have been building up in the global economy. One is that shocks to the supply of energy and other commodities — like those that followed Russia’s invasion of Ukraine and the US war on Iran — may become more frequent as geopolitical divisions widen.
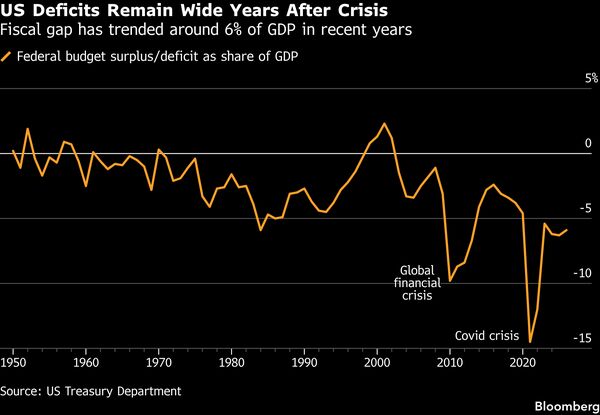
此外,联邦政府还面临着2万亿美元的预算赤字,这相当于美国国内生产总值(GDP)的6%左右,在失业率较低且经济增长稳健的情况下,这属于历史高水平的刺激措施。尽管特朗普政府多次誓言要控制支出,但外界几乎不指望这种情况会在短期内发生。
Then there’s the federal government’s $2 trillion budget deficit — the equivalent of about 6% of the nation’s gross domestic product, an historically high level of stimulus at a time of low unemployment and solid economic growth. While the Trump administration has repeatedly vowed to rein in spending, there’s little expectation that will happen anytime soon.
“宏观环境充满了风险,这应该转化为健康的期限溢价,”Siebert Financial首席投资官马克·马莱克(Mark Malek)表示。“每当有突发新闻出现时,投资者就会被提醒这种风险的存在。”
“The macro picture is full of risk which should translate into a healthy term premium,” said Mark Malek, the chief investment officer at Siebert Financial. “Any time we have a headline flair up, investors are reminded of that risk.”