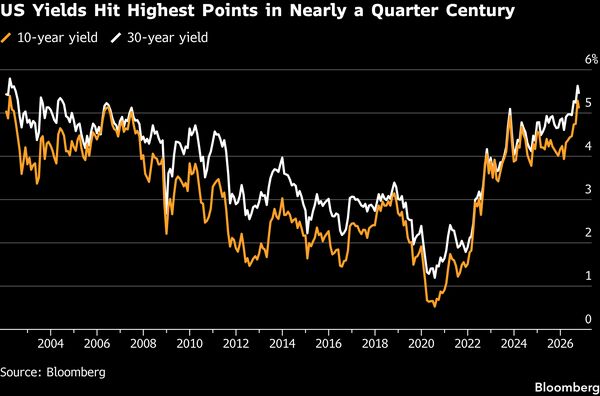
美国国债遭遇抛售,基准收益率飙升至数十年高位,导致美国政府越来越依赖那些只在价格合适时才买入的投资者。
Beset by a selloff in Treasuries that’s sent benchmark yields to multidecade highs, the US government is finding itself increasingly dependent on investors who only buy if the price is right.
过去二十年间,全球最大债券市场规模膨胀七倍至32万亿美元,这主要得益于山姆大叔的疯狂借贷。随着市场演变,其投资者结构也在发生变化。
The evolution in who forms the world’s biggest bond market is underway after it swelled seven-fold to $32 trillion over the past two decades, powered by Uncle Sam’s rampant borrowing.
外国政府、央行和养老基金的相对重要性不如从前。这些机构对价格的反应不那么敏感,习惯大量买入传统上被视为无风险、以美元计价、回报可预期的证券。尽管其中一些机构正考虑削减持仓,但它们通常长期持有美国国债。可以称它们为“慢钱”。
Relatively less important than they once were are the foreign governments, central banks and pension funds that display a less knee-jerk sensibility toward prices and hoover up traditionally risk-free securities — which pay predictable returns and are issued in dollars. Although some are flirting with winnowing their holdings, they are typically holding Treasuries for the long-run. Call them slow money.
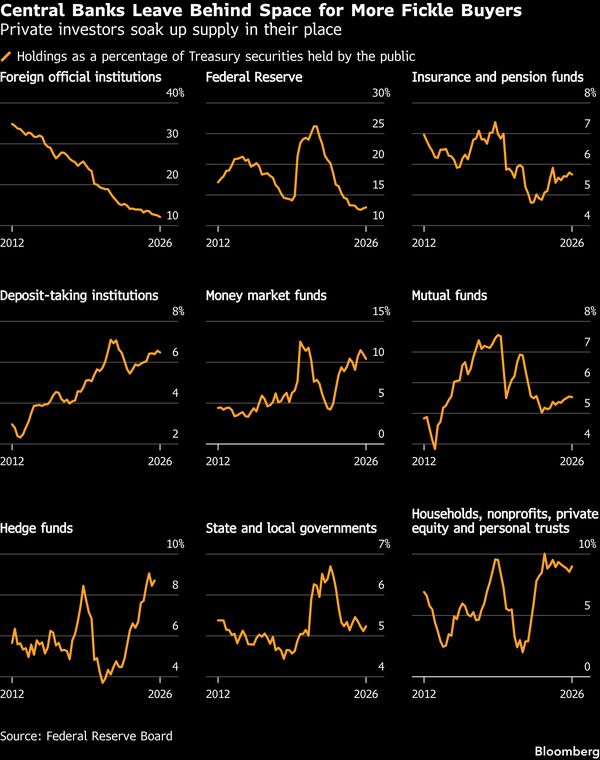
与此同时,私人投资者的份额正在扩大。他们持有约70%的联邦债务,接近1990年以来的最高水平。对冲基金占据国债市场近十分之一的份额,它们有其他资产可供选择,且利用杠杆利用市场错配获利的做法引起了监管机构对金融稳定风险的关注。在追逐收益的过程中,稍有风吹草动就可能让这类投资者转身离场。它们是“快钱”。
The footprint of private investors, meanwhile, is expanding. They own about 70% of federal debt, near the most since 1990. And almost a 10th of the Treasury market belongs to hedge funds, who have other assets to pick from and whose use of leverage to exploit market dislocations has drawn the eyes of regulators concerned over risks to financial stability. In the hunt for returns, it doesn’t take much for such investors to turn away. They’re the fast money.
对于美国财政部长斯科特·贝森特和美联储主席凯文·沃什这类人物而言,担忧在于:如果价格敏感型买家突然因货币政策、经济走向、美国赤字扩大或任何总统宣言而受惊,它们现在掌握的权力比以往任何时候都大。
For the likes of US Treasury Secretary Scott Bessent and Federal Reserve Chairman Kevin Warsh, the worry is that price-sensitive buyers now wield more power than ever if they suddenly take fright at monetary policy, the economic trajectory, widening US deficits or any presidential proclamation.
是的,美国政府仍能找到债权人为其开支买单,但这些投资者靠不住了——它们的反复无常正在推高收益率。
Yes, the US government is still finding creditors to bankroll its spending, but those investors are less reliable — and their fickleness is contributing to a rise in yields.
巴克莱银行美国利率策略主安舒尔·普拉丹认为,这种行为揭示了美国资金的真实成本。
To Anshul Pradhan, head of US rates strategy at Barclays Plc, it’s a behavior that reveals the true cost of money for the US.
“投资者群体变得更挑剔了,”他说。“拥有大量对价格不敏感买家的市场可以在相对较小的调整下吸收供应。依赖私人资本的市场可能需要更大的让步。”在今年债券抛售的背景下,这一转变正变得更加重要。虽然主要受全球因素驱动,如油价飙升以及经济增长前景改善,但重新定价也重新点燃了对美国政府财政政策的担忧。它同样推高了企业和个人的借贷成本。
“The investor base has become more discerning,” he said. “A market with large price-insensitive buyers can absorb supply with relatively little adjustment. A market that relies on private capital may require a larger concession.”In the context of this year’s bond selloff, the transformation is taking on even bigger significance. While driven largely by global factors such as a surge in oil prices as well as an improved economic growth outlook, the repricing has revived concerns over the US government’s fiscal policy. It’s also pushing up the cost of borrowing for companies and individuals.
一只澳大利亚国有基金去年表示,由于担忧美国总统唐纳德·特朗普的关税和税收计划,正在减少其美国国债持有。去年九月,挪威央行旗下的 Norges Bank Investment Management 部门提议削减其主权债务持有,称其在其他固定收益资产上可能获得更好的风险调整后回报。
An Australian state-run fund last year said it was reducing its Treasury holdings on concern over US President Donald Trump’s tariff and tax plans. And this September, Norges Bank Investment Management, a unit of Norway’s central bank, proposed reducing its sovereign debt holdings, saying it could see better risk-adjusted returns from other fixed-income assets.
与此同时,公司为融资人工智能及其配套基础设施,正创纪录地发行债务,这一押注助长了股市的狂热。
Companies, meanwhile, have been selling record amounts of debt to finance developments in artificial intelligence and the infrastructure to support it, a bet that’s helped drive a frenzy in the stock market.
不同于通常为管理国家储备和汇率而购买国债的外国央行,私人投资者更有能力抛售国债,转而持有公司债或股票。与此同时,美联储也不再通过量化宽松计划大量买入债券以刺激经济。
Unlike foreign central banks, who typically buy Treasuries to help manage national reserves and exchange rates, private investors have a greater ability to dump Treasuries in favor of corporate debt or stocks. The Fed, meanwhile, is no longer snapping up bonds as part of a quantitative-easing program designed to boost the economy.
“作为投资者,央行的波动性较小,部分原因是它们在购买上受到更多限制,”瑞银全球财富管理首席经济学家保罗·多诺万说。“多变且不受约束的私营部门提升了其在债券市场的影响力。”央行——通常被视为对价格最不敏感的买家——的撤出,为存款机构、对冲基金及其他相对更敏感价格的投资者让路。
“As investors, central bankers are less volatile, in part because they are more restricted in what they can buy,” said Paul Donovan, chief economist at UBS Global Wealth Management. “The fickle, less-captive private sector has increased its bond-market influence.”The retreat of central banks, often considered among the least price-sensitive buyers, has made way for depository institutions, hedge funds and other investors that are relatively more price-sensitive.
彭博经济研究估计,美联储和外国官方机构持有的美国国债减少,一度使期限溢价增加约105个基点。期限溢价是指投资者因持有10年期美国国债、而非在相同时间内滚动持有短期证券所承担风险而要求的额外回报。
Bloomberg Economics estimated that the decline in Fed and foreign official holdings of Treasuries at one point added roughly 105 basis points worth of term premium — or the extra payout that investors demand in return for the risks of owning 10-year Treasuries instead of just rolling over short-dated securities for the same amount of time.
长期债券的另一个关键需求来源如今可能正在减弱,因为企业养老金基金的管理人手头资金已足以支付退休人员的养老金,而且这些基金往往已不再接受新成员。
Another key source of demand for long-dated bonds may be fading now that managers of company pension funds have more than enough money on hand to pay their retirees, and are often shut off to new members.
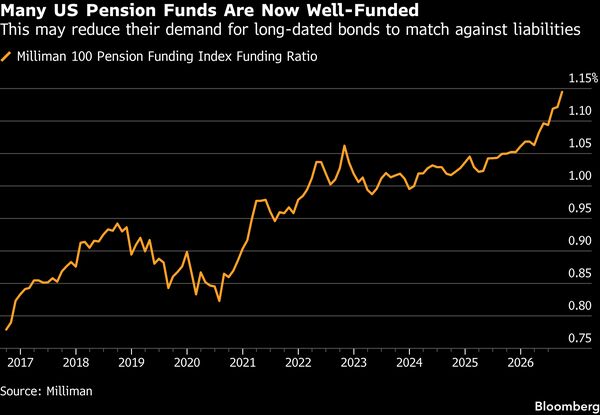
根据Milliman 100养老金资金指数,截至9月,企业养老金整体资金充足率约为114%。而在2020年7月,这些账户的资金充足率仅为82%。随着它们在股市中获利,它们有动力通过转向债券来限制风险,因为债券的预期收入可以与未来对退休人员的负债密切匹配。
Corporate pensions collectively had around 114% of the funding they needed as of September, according to the Milliman 100 Pension Funding Index. These accounts were just 82% funded in July 2020. As they notched winnings in the stock market, they had incentive to limit their risks by moving into bonds whose projected income can be closely matched to their future liabilities to retirees.
花旗集团利率策略师贾森·威廉姆斯表示,养老金基金需求减弱,可能促使美国财政部削减长期债务的发行,转而增加短期国库券的发行。
Jason Williams, a rates strategist at Citigroup Inc., said that waning pension-fund demand may push the Treasury to cut sales of long-dated debt in favor of greater short-dated bill issuance.
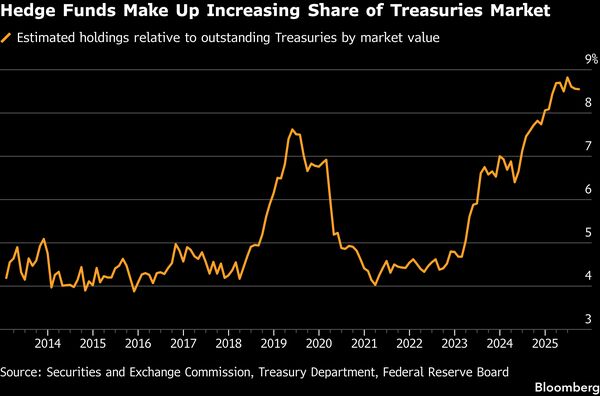
NISA Investment Advisors首席经济学家斯蒂芬·道格拉斯表示:“企业固定收益养老金计划的趋势是冻结或关闭。”“结果就是,你不再累积远期的新负债。”美联储研究人员指出,对冲基金持有的美国国债有所增加,其持仓在2012年至2025年间增长至原来的四倍,占其资产的近五分之一。它们对美国国债的吸纳速度超过了其他美国债权人,截至去年年底,这些基金持有约8.5%、即约2.7万亿美元的未偿美国国债。
“The trend in corporate defined-benefit pensions has been to freeze or close,” said Stephen Douglass, chief economist at NISA Investment Advisors. “As a result, you stop accumulating new liabilities in the distant future.”A rise in hedge funds’ Treasury holdings was flagged by Fed researchers as the funds quadrupled their position between 2012 and 2025, to constitute almost a fifth of their assets. Their absorption of US government debt has outpaced other US creditors, leaving the funds with roughly 8.5% — or about $2.7 trillion — of outstanding Treasuries as of late last year.
考虑到对冲基金快速行动、利用杠杆进行交易以及出售美国国债的灵活性,这是一笔值得注意的金额。
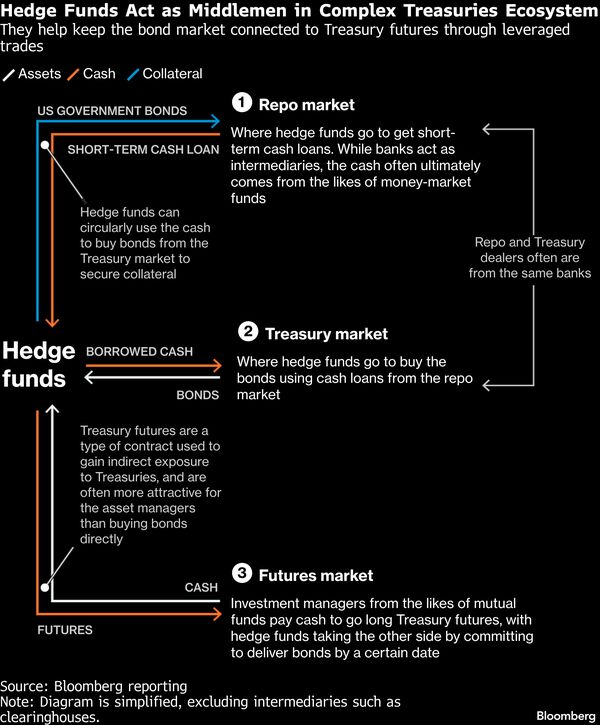
It’s a noteworthy sum given hedge funds’ ability to move rapidly, leverage their trades and their flexibility in selling a Treasury security.
对冲基金交易中有一部分利用的是市场上可比利率之间差距的相对价值。突出的例子包括基差交易和掉期利差交易,前者针对期货与债券之间的价差,后者则在利率掉期与国债之间进行押注。宏观对冲基金也会对收益率的方向进行押注。
A share of hedge-fund trades take advantage of the relative value in gaps between comparable rates in the market. Prominent examples include the basis trade, which targets the spread between futures and bonds, and swap spreads, which wagers between interest-rate swaps and Treasuries. Macro hedge funds also make bets on the direction of yields.
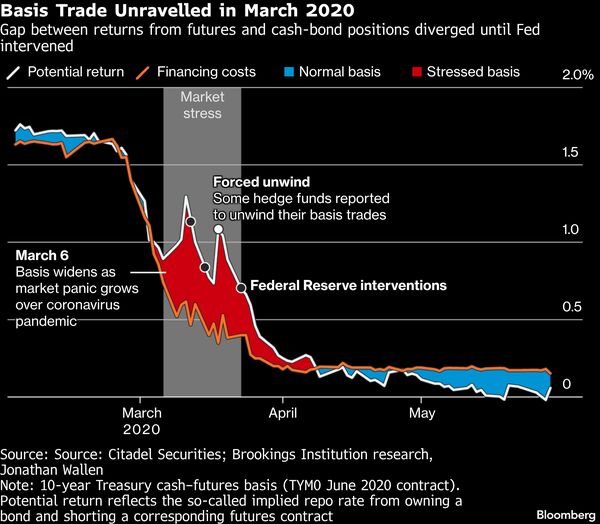
TS Lombard董事总经理史蒂文·布利茨提到了对冲基金在掉期利差和基差交易中的活动,他说:“杠杆买家提振了需求,并阻止收益率上升过高。”但“一旦回购利率大幅上升,这些头寸就会被平仓,从而造成大量美国国债涌入市场。”为了说明对冲基金持仓的潜在威胁,市场参与者、监管机构和美联储都提到了2020年3月,当时投资者在疫情封锁前寻求卖出债券以换取现金。
“Leveraged buyers boost demand and keep yields from rising too far,” said Steven Blitz, a managing director at TS Lombard, citing their activity in swap spreads and the basis trade. But “any sharp up move in repo rates and these positions are undone, creating a flood of US Treasuries.”To illustrate the potential threat of hedge funds’ holdings, market participants, regulators and the Fed have pointed to March 2020, when investors sought to sell bonds for cash ahead of pandemic lockdowns.
那轮抛售冲击了对冲基金的基差交易头寸,加剧了市场波动。但近几个月来,这一交易规模一直在缩小,表明这种杠杆策略并不值得担忧。
The selloff challenged hedge funds’ basis-trade positions, which exacerbated the market moves. But the trade has been shrinking in recent months, an indication that the leveraged strategy isn’t a cause for concern.
尽管如此,这种交易仍凸显出快钱策略与美联储等主要央行策略之间的分化——尤其是在对价格敏感的投资者在市场中所占比例越来越高的情况下。
Still, the trade underscores the split between fast-money strategies and those of major central banks like the Fed — especially as price-sensitive investors make up an increasing portion of the market.
由亚历山德罗斯·塞诺丰托斯领导的TS Lombard团队写道:“全球债券市场正在适应一个不那么宽容的买家基础。政府仍将能够为自己融资,但越来越多地要以更具自主裁量权的投资者所设定的价格来融资。”
“Global bond markets are adjusting to a less forgiving buyer base,” wrote a TS Lombard team led by Alexandros Xenofontos. “Governments will still fund themselves, but increasingly at prices set by more discretionary investors.”