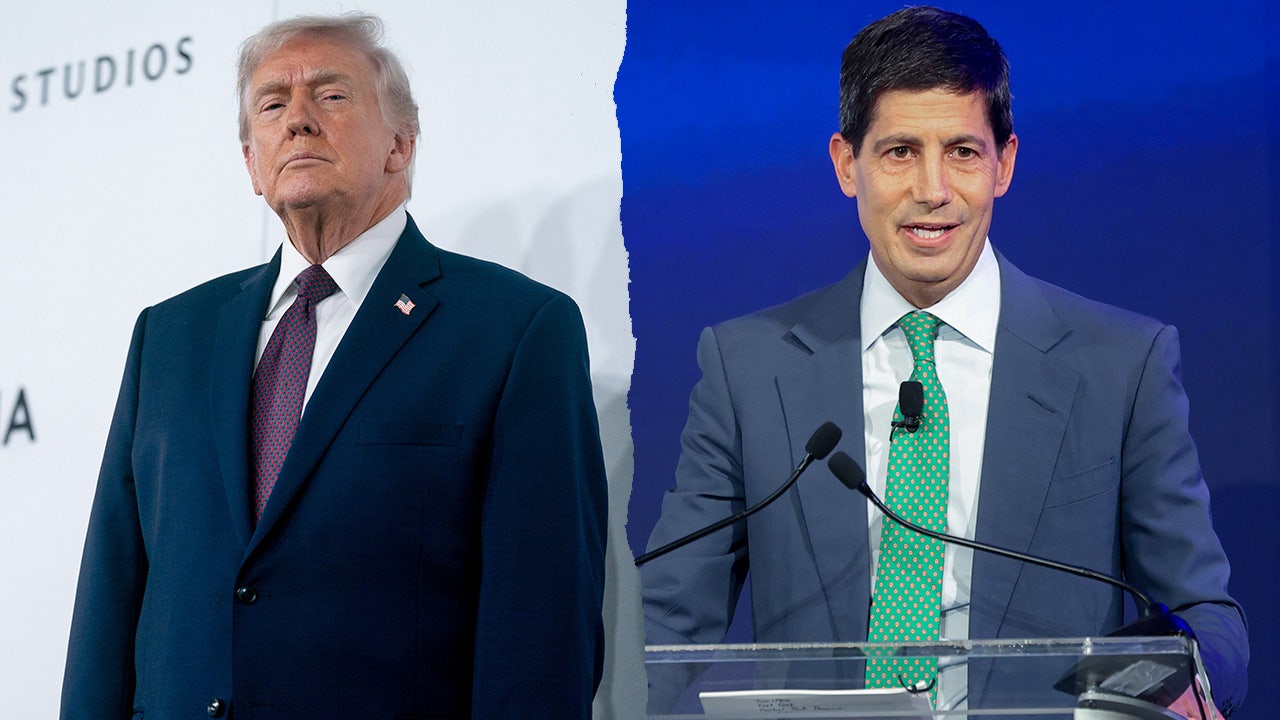
起初,凯文·沃什和斯科特·贝森特看起来像是一对能给唐纳德·特朗普带来其心仪经济团队的搭档。两人都谈到,更快的增长可能与更低的通胀共存。两人都希望重新思考美联储与财政部的关系。贝森特协助监督了将沃什推上美联储主席宝座的搜寻工作。人们很容易想象两人会紧密合作。六个月后,现在更容易想象他们走上对立面。
Kevin Warsh and Scott Bessent looked, at the start, like a pairing that might give Donald Trump the economic team he wanted. Both talked about the possibility that faster growth could coexist with less inflation. Both wanted to rethink the relationship between the Federal Reserve and the Treasury. Bessent helped oversee the search that put Warsh in the Fed chairmanship. It was easy to imagine the two working closely together. Six months later, it is now easier to imagine them on a collision course.
沃什在上个月的美联储会议上加息以对抗通胀。贝森特一直在努力控制政府债务融资成本。通常情况下,这两份工作可以互不干扰地开展。金融研究员卢克·格罗门在最近的分析中提出的一个令人担忧的可能性是:沃什为履职所做的努力,可能会让贝森特的工作变得更加困难。美联储刚刚给特朗普的中期经济信息“扔了个扳手”我们都知道传统的预期。
Warsh raised interest rates during last month's Fed meeting to fight inflation. Bessent has been trying to contain the cost of financing the government’s debt. Usually, those jobs can be carried out without one man making the other’s life miserable. The alarming possibility, laid out in a recent analysis by financial researcher Luke Gromen, is that Warsh’s efforts to do his job could make Bessent’s much harder. THE FED JUST THREW A WRENCH IN TRUMP'S MIDTERM ECONOMIC MESSAGE We all know the conventional expectations.
美联储加息短期利率。投资者对通胀将下降更有信心。他们购买长期国债,压低这些债券的收益率,最终降低购房者和其他借款人支付的利率。格罗门认为,这种预期可能不再成立。该国有大量债务需要出售,而买家不再全是过去那种耐心的投资者。对冲基金持有的国债份额不断增加,往往还使用借来的钱。如果加息动摇市场,其中一些可能被迫抛售。
The Fed raises short-term rates. Investors have become more confident that inflation will come down. They buy longer-term Treasury bonds, bringing down the yields on those bonds and, eventually, the rates paid by homebuyers and other borrowers. Gromen thinks that expectation may no longer hold. The country has a great deal of debt to sell, and the people buying it are not all the patient investors of old. Hedge funds own a growing share of Treasuries, often with borrowed money. If a rate hike shakes the markets, some may have to sell.
美元走强可能给美债外国持有者施加压力,促使他们也抛售。更多债券待售意味着债券价格下跌、收益率上升。
A stronger dollar could put pressure on foreign holders of American debt, prompting them to sell as well. More bonds for sale mean lower bond prices and higher yields.
特朗普的5000美元支票或将加入历届未兑现承诺的行列,前国会预算办公室主任警告这只是格罗门的理论,但远未获得普遍认同。
TRUMP’S $5K CHECKS COULD JOIN STACK OF PAST UNFULFILLED PROMISES, FORMER CONGRESS BUDGET CHIEF WARNS That is Gromen’s theory, but it is far from universally accepted.
然而,沃什和贝森特面临的问题影响重大,不容忽视,因为答案尚未揭晓。如果加息导致抵押贷款更昂贵,增加政府的利息支出,却无法平息债券市场,会怎样?贝森特必须继续为国债寻找买家,包括到期需要通过新借贷置换的债务。如果政府必须支付更高成本才能吸引这些买家,其利息成本就会上升。如果更高的利率进而拖累经济,税收可能受损,政府可能需要借更多的钱。
However, the question for Warsh and Bessent is too consequential to dismiss because the answer has yet to be established. What if raising rates makes mortgages more expensive, increases the government’s interest bill and fails to calm the bond market? Bessent must keep finding buyers for Treasury debt, including debt coming due that has to be replaced with new borrowing. If the government has to pay more to attract those buyers, its interest costs rise. If higher rates then slow the economy, tax receipts could suffer and the government could need to borrow still more.
这就是格罗门看到的危险:试图遏制通胀,结果却让国家为偿付更大规模的债务支付更高成本。美联储多年来首次加息:对你的钱包意味着什么沃什和贝森特很快可能面临一个极其棘手的选择。在宏观经济信号好坏参半的情况下,沃什可能认为通胀需要再次加息。贝森特可能正注视着国债收益率攀升,担心市场还能承受多大压力。
That is the danger Gromen sees: an attempt to contain inflation that leaves the country paying more to finance a larger debt. FED RAISES RATES FOR FIRST TIME IN YEARS: WHAT IT MEANS FOR YOUR WALLET Bessent and Warsh could soon face an extraordinarily uncomfortable choice. Amidst mixed macroeconomic signals, Warsh might believe inflation requires another hike. Bessent might be watching Treasury yields climb and wondering how much more pressure the market can take.
一方试图让资金变得更昂贵;另一方却需要政府廉价借款。他们早期对经济形势的一致看法无法化解这一分歧。特朗普也无法指望能悄然充当调停人。总统希望在中期选举前看到降息和经济更强劲。结果却等来了加息。是他选了沃什,也选了贝森特。如果他们的路径开始冲突,特朗普会想要一个不必在抗击通胀和降低借贷成本之间二选一的解决方案。
One would be trying to make money more expensive; the other would need the government to borrow it cheaply. Their early agreement about the economy would not settle that argument. Nor could either count on Trump to referee it quietly. The president wanted lower rates and a stronger economy heading into the midterms. He got a rate increase instead. He picked Warsh, and he picked Bessent. If their approaches begin to clash, Trump will want a solution that does not require him to choose between fighting inflation and making borrowing cheaper.
但可能根本不存在这样的方案。共和党刚获得国会争夺战的强力新剧本:内情如下政治后果显而易见。总统可以解释为什么独立的美联储做出了他不喜欢的决定。但他将很难解释为什么在他的美联储主席加息以压低抵押贷款利率后,房贷利率依然居高不下。
There may be no such solution. REPUBLICANS JUST GOT A POWERFUL NEW PLAYBOOK FOR THE BATTLE FOR CONGRESS. HERE'S WHAT'S INSIDE The political consequences are plain enough. A president can explain why an independent Fed made a decision he disliked. He will have a harder time explaining why mortgage rates remain high after his Fed chairman raised rates to bring them down.
“债券市场的表现与我们预期的不同”这一说法听起来相当严重。但对于一个刚刚算完房屋月供的家庭来说,这恐怕难以带来安慰。当然,情况也可能没有那么糟糕。通胀或许会缓解。投资者或许会认为,沃什的坚定立场使长期国债更具吸引力。收益率或许会下降,从而为贝森特争取到喘息空间,也让特朗普获得他想要的宽慰。
"The bond market is behaving differently than we expected" is a serious explanation. It is unlikely to comfort a family that has just calculated the monthly payment on a house. There are less dire possibilities. Inflation could ease. Investors could decide Warsh’s resolve makes long-term Treasuries more attractive. Yields could fall, giving Bessent breathing room and Trump the relief he wants.
格罗门或许对接下来市场的反应判断错误。这场博弈主要不会是美国总统特朗普与美联储主席沃什之间的对决——即总统希望获得廉价资金,而美联储主席却拒绝配合的老故事。真正的对决将是沃什与贝森特:两位看似注定成为盟友的人,如今却面临一个棘手的经济环境,其中一方认为必要的解决方案,可能恰恰会加剧另一方试图避免的风险。
Gromen could be wrong about how the market responds from here. ute will not chiefly be Trump versus Warsh, the familiar story of a president who wants cheap money and a Fed chairman who says "no." It will be Warsh versus Bessent: two men who appeared destined to be allies, confronting an economy in which the remedy one considers necessary may aggravate the danger the other is trying to prevent. FROM MARK HALPERIN