债券和衍生品市场是在替央行承担艰巨的工作吗?掉期交易正在对未来12个月全球协同加息周期进行定价,而美国、欧洲和日本的长期债券收益率也创下了几十年来最高水平。这反过来促使美联储主席凯文·沃什以及英国央行和欧洲央行的一些政策制定者暗示,他们可能不需要像预期那样大幅加息,因为债务市场正在推高借贷成本,这应该会抑制经济增长和通胀。
Are the bond and derivatives markets doing the tough work for central bankers? Swaps are pricing a globally coordinated cycle of interest rate increased over the next 12 months, and longer-term bond yields are hitting multi-decade highs in the US, Europe and Japan. That, in turn, has prompted Federal Reserve Chair Kevin Warsh and some policymakers from the Bank of England and European Central Bank to suggest they might not have to raise rates as much as expected because the debt markets are making it more costly to borrow, which should curb growth and inflation.
这听起来很合理,但市场利率并不能很好地替代更紧缩的货币政策,如果央行将其用作不作为的借口,就会置自身的信誉于风险之中。
Sounds reasonable but market rates are a poor substitute for tighter monetary policy, and central bankers put their credibility at risk if they use it as an excuse for inaction.
沃什在7月曾指出,甚至在美联储9月加息之前,市场就已经“做了相当多的工作”。接着在上个月,尽管通胀率高于目标,英国央行仍部分利用不断上升的短期市场利率来为其6比3维持主要政策利率不变的决定辩护。据9月会议纪要显示,英国央行货币政策委员会的“大多数成员”表示,市场利率产生了“大体上足够程度的货币政策紧缩”。
Warsh observed in July that the markets had “done quite a bit” even before the Fed went on to raise rates in September. Then last month, the BOE partially used rising short-term market rates to justify its 6-3 decision to keep its main policy rate steady, despite above-target inflation. “Most members” of the BOE’s Monetary Policy Committee said market rates were producing “a broadly sufficient degree of monetary policy restraint,” according to the September meeting minutes.
欧洲央行也呼应了这一观点,在周四公布的会议纪要中表示,市场可能会影响政策的前瞻性路径(重点由笔者标注):只要收益率曲线长端的重新定价保持有序,它也支持了既定的货币政策立场,并可能对未来合适的政策利率产生影响。模型估计表明,较高长期利率对增长和通胀的影响可能是实质性的。仅依赖市场将构成一种必输的策略。
The ECB echoed the sentiment, saying in minutes published Thursday that markets could influence the prospective path of policy (emphasis mine): The repricing at the long end of the yield curve, provided it remained orderly, also supported the intended monetary policy stance and could have implications for appropriate policy rates in the future. Model estimates suggested that the effects of higher long-term interest rates on growth and inflation could be material. Relying on markets alone would constitute a losing strategy.
已故经济学家兼诺贝尔奖得主保罗·萨缪尔森曾用一只看到自己倒影的动物来形容前美联储主席艾伦·格林斯潘对市场的反应。“我想起了一只生平第一次照镜子的猴子,”他说。“他在镜子里看到了自己的影像,并认为通过观察那只猴子的反应——包括它的惊讶——他正在获得新的信息。”经济学家斯蒂芬·莫里斯和韩宋申将此称为“反映问题”,这是在致敬萨缪尔森1994年的名言。
The late economist and Nobel laureate Paul Samuelson famously described former Fed Chair Alan Greenspan’s reactions to markets as an animal seeing his own reflection. “I am reminded of a monkey who for the first time has seen a mirror,” he said. “He sees an image of himself in the mirror and thinks that by looking at the reactions of that monkey—including its surprises—he is getting new information.”Economists Stephen Morris and Hyun Song Shin have dubbed this “the reflection problem,” in reference to Samuelson’s 1994 quote.
从实际情况来看,如果央行不采取后续行动并加息,上升的债券收益率可能会迅速逆转,并且在遏制通胀方面也不会取得进一步进展。为了让更紧缩的货币政策发挥作用,利率必须在较长时间内保持高位,而最近一轮债券抛售潮还不到两个月。
In practical terms, it’s possible rising bond yields would quickly reverse themselves if central banks didn’t follow through and raise rates, and there would have been no further headway made on reining in inflation. For tighter monetary policy to work, interest rates must remain elevated for an extended period, and the latest bond rout is less than two months old.
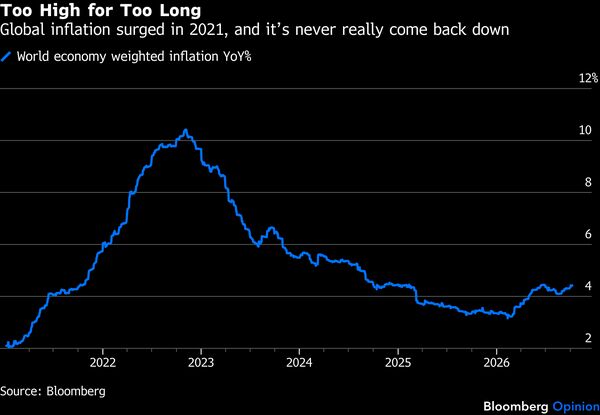
全球通胀高企已经持续了六年,以总统唐纳德·特朗普和日本首相高市早苗为首的民粹主义领导人正在将独立央行的未来置于危险之中。与此同时,世界继续应对一连串通胀冲击的余波,包括新冠疫情、俄罗斯入侵乌克兰、特朗普的关税、美以与伊朗的战争以及能源冲击。在如此充满挑战的环境中,声誉和表象与经济学同等重要,央行不能被看到袖手旁观,指望市场代其完成所有繁重的工作,而自己却连续多年错过通胀目标。
Global inflation has been elevated for six years now, and populist leaders — led by President Donald Trump and Japan Prime Minister Sanae Takaichi — are putting the future of independent central banking at risk. Meanwhile, the world continues to deal with the aftermath of a barrage of inflationary shocks, including the Covid-19 pandemic, the Russia invasion of Ukraine, Trump’s tariffs, the US-Israel war with Iran and an energy shock. In such a fraught environment, reputation and optics are just as important as economics, and central bankers can’t be seen sitting on their hands and hoping the markets do all the heavy lifting for them while they miss their inflation targets for another year.
市场利率的上升部分归因于具韧性的全球经济,加上异常庞大的联邦财政赤字以及人工智能企业的借贷狂潮——所有这些都支撑了通胀力量。难怪10年期日本国债收益率创下1996年以来的最高水平,10年期美国国债收益率创下2002年以来的最高水平,英国国债收益率创下2007年以来的最高水平,德国国债收益率创下2009年以来的最高水平。
The increase in market rates is due in part to a resistant global economy combined with abnormally wide federal budget deficits and a glut of borrowing from artificial intelligence companies — all of which underpin inflationary forces. It’s little wonder that 10-year Japanese note yields are their highest since 1996, 10-year US Treasury yields are the highest since 2002, UK yields are the highest since 2007 and German yields are the highest since 2009.
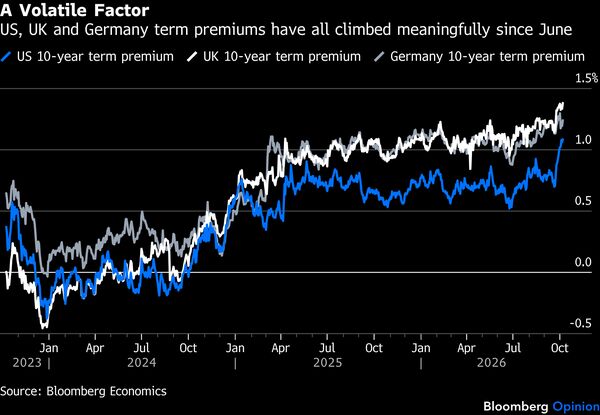
然而,这些影响各自经济体借贷成本的高收益率本身并不足以驯服通胀。原因在于,部分上涨归因于所谓的期限溢价的增加,即投资者要求持有较长期限债券而非短期债券的额外收益率。基于对风险的市场评估,期限溢价历来波动剧烈且容易受情绪摆动的影响。彭博经济研究的模型显示,美国10年期期限溢价约为1.03%,但在6月时曾低至0.52%,在短短两年前曾为负值,且在过去五年中的平均值仅为0.06%。
And yet, those high yields, which influence borrowing costs throughout their respective economies, won’t be sufficient on their own to tame inflation. The reason being is that part of the rises are due to increases in so-called term-premiums, or the extra yield investors demand to hold longer-maturity bonds rather than shorter-term notes. Based on a market assessment of risk, term premiums are notoriously volatile and subject to swings in sentiment. A Bloomberg Economics model puts the US 10-year term premium at about 1.03%, but it was as low as 0.52% in June and negative just two years ago and has averaged 0.06% over the past five years.
所有这一切都增加了迫在眉睫的“反映问题”的几率。想想美联储在2023年末的经历,当时它在9月进行了该周期的最后一次加息,而长期收益率又继续攀升了一个多月。达拉斯联邦储备银行行长洛里·洛根表示,更高的期限溢价“可能会为我们完成部分冷却经济的工作,从而减少进一步收紧货币政策的需要”。结果如何?
All this raises the odds of a looming “reflection problem.”Consider the Fed’s experience in late 2023, when it lifted rates for the final time of that cycle in September and longer-term yields continued to climb for another month or so. Federal Reserve Bank of Dallas President Lorie Logan said higher term premiums “could do some of the work of cooling the economy for us, leaving less need for additional monetary policy tightening.”How did that turn out?
美联储没有继续收紧政策,而是按兵不动,10年期美国国债收益率在不到两个月内暴跌了1.20个百分点。至于通胀,它未能回到2%的目标。糟糕。其他央行是否必须再次以惨痛的教训来吸取经验?
Instead of continuing to tighten policy, the Fed kept rates on hold and the 10-year Treasury yield plummeted 1.20 percentage points in under two months. As for inflation, it failed to return to the 2% target. Oops. Will other central banks have to learn this lesson again the hard way?
央行需要发挥作用,但它们不能依赖市场来发挥作用。对政策制定者而言,近期市场利率的上升是一个受欢迎的发展,表明他们的努力正在发挥作用。但这并不是他们大功告成的信号。
Central banks need to work but they can’t depend on the markets to work . For policymakers, the recent rise in market rates is a welcome development that shows that their efforts are working. What it’s not is a sign that their work is done.