这是一次向监管机构发出的紧急呼吁:他们敦促监管机构介入,制止这种鲁莽的行为。当时,智利的养老基金正在对美国利率进行大规模的投机交易;而在一年多后,这场投机行为最终导致了巨大的损失(这些基金亏损了数十亿美元)。
It was a desperate appeal to regulators: Step in, they were urged, and put a stop to this reckless behavior. It came as Chilean pension funds were making outsized bets on US interest rates, more than a year before a painful blowup left them billions of dollars in the red.
然而,这些警告并非来自内部举报人,也不是来自那些仔细审查账目的精明投资者,而是来自养老基金的高管们。这些高管在与监管机构的私下谈话中,恳请制定相关法规,以阻止自己继续从事这种高风险交易(即大量购买波动性极高的衍生品)。
But the warnings weren’t from an internal whistleblower, or an especially savvy investor looking into the books. Instead, they came from executives at the pension funds, who in private conversations with regulators were begging for rules to prevent them from doing exactly what they were doing — loading up on volatile derivatives.
熟悉这些谈话内容的人士表示,高管们解释说,这种高风险交易带来的利润实在过于丰厚,因此他们无法单方面停止这种行为,否则就会放弃那些竞争对手仍能获得的收益。当前的金融体系会对表现不佳的养老基金施加惩罚。
People familiar with the conversations, which haven’t previously been reported, said the executives explained the risky trade had been so lucrative that they couldn’t act unilaterally without giving up returns that rivals would continue to earn. The system penalizes funds that underperform peers.
如今,由于美国借贷成本飙升,导致养老基金遭受损失,当初未能及时采取行动的后果正在反过来困扰着这个国家的退休人员——因为这些养老基金是通过强制缴费来为整个价值2300亿美元的养老体系提供资金的。
Now, delays in heeding that call is coming back to haunt the country’s pensioners, who fund the $230 billion industry with mandatory contributions, after a surge in US borrowing costs sparked losses.
立法者们感到愤怒,退休者们忧心忡忡,而监管机构也面临着公众的严厉审视;公众要求了解事情为何会迅速恶化,以及谁应该为此负责。这再次凸显了全球金融市场的连锁反应:伊朗战争导致能源成本飙升,进而引发了多方面的连锁反应——从日本政府的货币市场干预措施、美联储的加息决策,到智利的一位退休者不得不推迟自己的退休计划。
Lawmakers are furious, retirees are anxious and regulators are under scrutiny as the public demands answers about how things went so bad so quickly, and who will be held accountable. It’s another example of the global fallout from the bearish turn for US Treasuries after the war in Iran sent energy costs surging, resulting in everything from currency-market intervention in Japan and a Federal Reserve rate hike to a pensioner in Chile who says she will now have to delay her retirement.
“我只能继续观察市场,看看情况是否会有所好转,”57岁的玛格丽塔·萨尔迪亚(Margarita Saldía)说道。她是一名公务员,由于看到自己账户中的资金价值大幅缩水,她表示自己将不得不推迟退休计划几年。
“All I can do is watch the market and see if the situation turns around,” said Margarita Saldía, 57, a public-sector employee who says she’ll need to postpone her retirement by a couple of years after seeing the value of her accounts sink.
养老金监管机构拒绝就基金是否曾要求制定可能降低风险的规则发表评论。该机构负责人华金·科尔特斯周四在接受当地报纸《梅尔库里奥》采访时表示,评估基金的投资决策并非他的职责。
The pension regulator declined to comment on whether the funds had asked for rules that could have reduced the risk. Joaquín Cortez, who heads the body, told local newspaper El Mercurio on Thursday that it isn’t his place to assess the funds’ investment decisions.
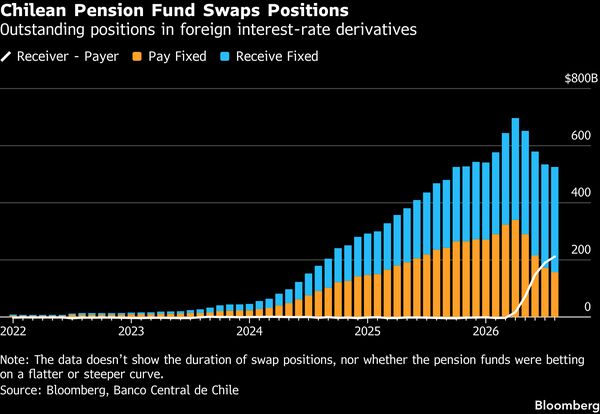
事情出错的速度之快,难以言喻。仅八个月前,这些被称为AFP的基金的外国利率衍生品头寸显示出21亿美元的按市价计价收益。到了9月,它们面临的市场价值却为负77亿美元。
It’s hard to overstate how quickly things went wrong. Just eight months ago, the foreign interest-rate derivative positions at the funds, known as AFPs, showed a $2.1 billion mark-to-market gain. In September, they were staring at a negative $7.7 billion market value.
“监管机构可以施加限制以降低风险,但前提是有一位对此事有专业知识的基金经理,”安第斯大学经济学教授马蒂亚斯·阿塞韦多表示。“问题是,他们为何采取了如此长期的头寸。鉴于这显然不是适合今日退休会员的良好策略,他们应该说明其影响。”智利工人必须参加养老金制度,储户可从五个不同的基金中选择,这些基金根据账户持有人的年龄设计了不同风险等级。
“The regulator can impose limits to reduce the risk, but the assumption is that there is a fund manager who is an expert on this matter,” said Matías Acevedo, an economics professor at Universidad de los Andes. “The question is why they took such a long-duration position. Given that it clearly wasn’t a good strategy for members retiring today, they should explain what the impact is.”Chilean workers are required to participate in the pension system, and savers have five different funds to choose from, designed with different levels of risk depending on the owner’s age.
本应是最保守的、即所谓的面向即将退休人群的E类基金,恰恰是受损害的美国利率押注风险敞口最大的基金。这些基金今年平均亏损10.4%,其中仅9月就下跌了4.9%,当时美国债券抛售加速。
The funds that were supposed to be the most conservative, so-called E funds meant for people near retirement, were the ones most exposed to the soured US rate bets. They’ve lost an average 10.4% this year, including a 4.9% drop in September alone, when the US bond rout accelerated.
同月,管理着养老金体系近一半资产且也持有部分此类押注的C类和D类基金,分别下跌3.1%和4.2%。根据行业协会的数据,大多数即将退休的人都在D类基金中。
That month, the C and D funds — which manage almost half of the pension system’s assets and also hold some of these bets — lost 3.1% and 4.2%, respectively. Most people approaching retirement are in Fund D, according to the industry association.
雪上加霜的是,AFP面临11月初的截止日期,必须遵守监管机构4月份实施的更严格的衍生品限制,此前监管机构与基金就头寸风险进行了数月的磋商。这意味着持有仍超出上限资产的基金将被迫出售并锁定损失。
Adding to the pressure, the AFPs face an early-November deadline to comply with tighter derivatives limits imposed by the regulator in April, after months of exchanges with the funds over the risks of the positions. That means funds holding assets that are still above the caps will be forced to sell and lock in losses.
除了一家养老基金外,其余所有养老基金要么拒绝置评,要么没有回复相关询问。法国新闻社(AFP)和联合国组织(UNO)指出,保守型养老基金D和E的表现不佳,这需要从它们的长期投资视角来分析;尽管如此,这两只基金在截至9月的三年和五年期内仍实现了正的年化回报率。
All but one pension fund either declined to comment or didn’t reply to requests. AFP UNO said the weaker performance of the conservative D and E funds should be viewed against their long-term investment horizon, noting that both posted positive annualized returns over the three- and five-year periods through September.
智利的一些养老基金实际上由大型国际公司持有。例如:AFP Habitat的部分股权属于Prudential Financial Inc.;AFP Cuprum的部分股权属于Principal Financial Group Inc.;而AFP Provida则由MetLife Inc.持有。
Some of Chile’s AFPs are owned by large international companies. They include AFP Habitat, owned in part by Prudential Financial Inc.; AFP Cuprum, partially by Principal Financial Group Inc.; and AFP Provida, by MetLife Inc.
事实上,截至9月,智利的养老基金总价值比年初增加了约107亿美元,涨幅达到了4.8%。其中风险最高的A型基金在这段时间内上涨了8.6%,而B型基金的涨幅为5.3%。
To be sure, Chile’s pension funds were still worth about $10.7 billion more in September than at the start of the year, a gain of 4.8%. The riskiest A fund was up 8.6% over the period, while the B fund gained 5.3%.
Cortez在《El Mercurio》的采访中表示,监管机构早在2024年就曾警告这些养老基金注意衍生品投资所带来的风险,并在2025年1月要求它们修改相关政策以控制这些风险。
Cortez said in the El Mercurio interview that the regulator had warned the AFPs about dangers surrounding the derivative positions back in 2024 and in January 2025 demanded they modify policies to manage that risk.
对于智利来说,这场养老基金危机尤其具有冲击性。长期以来,智利一直以其养老金制度为荣——该制度是在所谓的“芝加哥学派”经济学家的指导下建立的。这些经济学家曾在芝加哥大学接受培训,并推动了1970年代在奥古斯托·皮诺切特执政时期的自由市场改革,其经验也经常被其他国家作为典范引用。该制度用由私营公司管理的个人储蓄账户取代了原有的国家主导的退休金体系,这一模式后来也被秘鲁、墨西哥和哥伦比亚等邻国采纳。
The pension blowup is particularly painful for Chile, which has long taken pride in a model designed in the era of the so-called Chicago Boys — a group of economists trained at the University of Chicago who shaped the 1970s free-market reforms under Augusto Pinochet — and frequently cited as an example abroad. The system replaced a state-run retirement system with individual savings accounts managed by competing private firms, a model that inspired similar efforts in regional peers including Peru, Mexico and Colombia.
虽然这一制度被认为促进了当地资本市场的发展并增加了人们的储蓄意愿,但它也长期受到批评,主要原因是养老金水平过低以及劳动者需要承担较高的风险。日益增长的不满情绪不仅引发了2019年的街头抗议活动,还在疫情期间导致了总计近520亿美元的大规模资金提取。
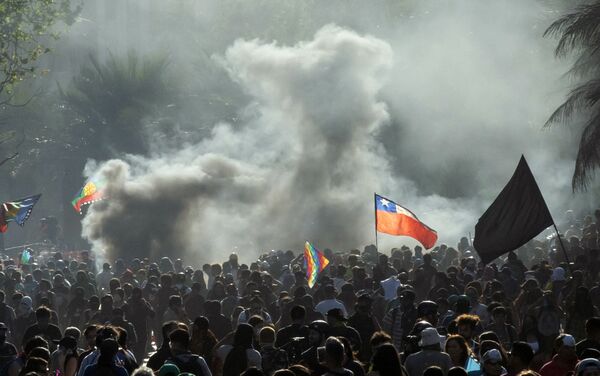
The system was credited with deepening local capital markets and boosting savings. But it has also faced decades of criticism over low pensions and the risks shouldered by workers. The mounting discontent helped animate 2019 street protests and also fanned a series of mass withdrawals totaling almost $52 billion during the pandemic.
这一切最终导致了2025年一项全面的养老金改革,打破了多年的政治僵局,并引入了提升账户的措施,包括雇主缴费的强制性规定。这项改革保留了AFPs和个人账户,同时也试图缩小长期存在的退休收入差距。如今,衍生品灾难正使该体系再次受到审查。
That culminated in a sweeping 2025 pension reform that broke years of political deadlock and introduced measures to boost accounts, including mandates for employer contributions. The overhaul preserved the AFPs and individual accounts, while also seeking to narrow longstanding retirement-income gaps. Now, the derivatives debacle is putting the system under renewed scrutiny.
几位智利立法者正在向监管机构和其他政府机构寻求解释,同时要求审计总长确定养老金监管机构的行为是否得当。
Several Chilean lawmakers are seeking explanations from the regulator and other government agencies, while asking the comptroller general to determine whether the pension watchdog acted properly.
“人们退休储蓄的损失可能是无法估量的,尤其是对那些即将退休的人来说,”独立立法者哈伊梅·阿拉亚表示,他签署了发给监管机构的几份正式请求中的一份。
“The damage to people’s retirement savings could be incalculable, particularly for those who are closest to retirement,” said independent lawmaker Jaime Araya, who signed one of the several formal requests sent to the regulator.
阿拉亚还要求AFPs披露损失影响的详细信息,并告知个人储户其退休账户受到了怎样的影响。
Araya is also demanding that the AFPs disclose detailed information on the impact of the losses and tell individual savers how their retirement accounts have been affected.
与此同时,社会党立法者丹尼尔·马努切赫里正在寻求支撑新衍生品限额和合规时间表的研究、法律和技术报告、通信及其他文件。他还想知道证券监管机构、财政部和其他当局是否就保证金追缴风险和更广泛的金融稳定威胁协调了应对措施。
Meanwhile, Socialist lawmaker Daniel Manouchehri is seeking the studies, legal and technical reports, communications and other documents underpinning the new derivatives limits and compliance timetable. He also wants to know whether the securities regulator, Finance Ministry and other authorities coordinated responses to the risk of margin calls and broader threats to financial stability.
“监管机构往往没有勇气在这些问题上采取果断行动,”阿拉亚说。
“Often, regulators haven’t had the guts to act firmly on these issues,” Araya said.
疫情期间前所未有的储蓄提取潮最初促使AFPs转向利率衍生品。他们将互换合同视为一种廉价的方式,以建立对长期利率的敞口。
The unprecedented exodus of savings during the pandemic withdrawals is what had initially pushed the AFPs toward interest-rate derivatives. They viewed the swaps as a cheap way to build exposure to long-term interest rates.
该策略曾一度取得成功。它帮助E基金去年实现了平均8.1%的收益,这是自2019年以来的最佳表现。
The strategy paid off for a time. It helped drive the E funds to an average gain of 8.1% last year, their best performance since 2019.
但根据花旗集团的分析,到了4月份,这些基金的收益每变动1个基点,其资金损失就会达到约1.31亿美元;而在2024年初,这一损失仅为约1060万美元。本月早些时候,10年期美国国债的收益率飙升至5.36%,而2月份时这一收益率还低于4%。
But by April, the funds were exposed to swings of about $131 million for every one-basis-point move in yields, up from about $10.6 million in early 2024, according to a Citigroup analysis. Yields on benchmark 10-year Treasuries peaked at 5.36% earlier this month, up from below 4% in February.
目前尚不清楚这些衍生品交易究竟导致了多大的损失,以及在11月的截止日期之前,这些基金还需要平掉多少份合约。虽然它们的持仓规模已经缩小,但随着利率的上升,它们退出这些交易所需的成本却持续攀升。
Exactly how much the AFPs have unwound — and how many more contracts they need to close before the November deadline — remains unclear. Their positions have shrunk, but the cost of getting out has continued to climb as rates move against them.
该行业协会表示,他们拒绝将这类衍生品交易视为“赌博行为”,并认为这些交易是用于长期管理固定收益投资组合的标准工具。该协会在一份声明中称:“这是一种长期投资策略。全球的固定收益基金都使用衍生品来调整现金流的时间和到期日,它们是投资策略的重要组成部分。”然而,对于那些即将退休的智利人来说,争论的焦点已不再是责任归属问题,而是更为紧迫的问题:接下来该怎么办。
The industry association said that it rejects the characterization of the derivatives trades as bets, arguing that they are a standard tool for managing fixed-income portfolios over long periods. “It is a long-term strategy,” the AFP association said in a statement. “Fixed-income funds around the world use derivatives to adjust the timing and maturity of cash flows, and they are an important part of investment strategies.”For Chileans nearing pension age, though, the debate is not over who is responsible but rather a more immediate concern: what to do next.
独立养老金顾问Danitza Ortiz为大约15位即将退休的客户提供了明确的建议:“现在绝对不要考虑退休。”她建议客户让他们的储蓄有足够的时间恢复,然后再领取养老金。她警告说:“你必须熬过这段艰难时期,因为在未来几个月内,由于这些衍生品交易带来的负面影响,投资者可能会面临进一步的损失。”
Danitza Ortiz, an independent pension adviser with about 15 clients approaching retirement, has one blunt piece of advice: “Don’t even think about retiring now.”Instead, she is telling clients to give their savings time to recover before drawing a pension. “You have to ride out the plunge,” she said, warning that further losses could follow in the coming months as AFPs continue unwinding some of the swaps positions that backfired.