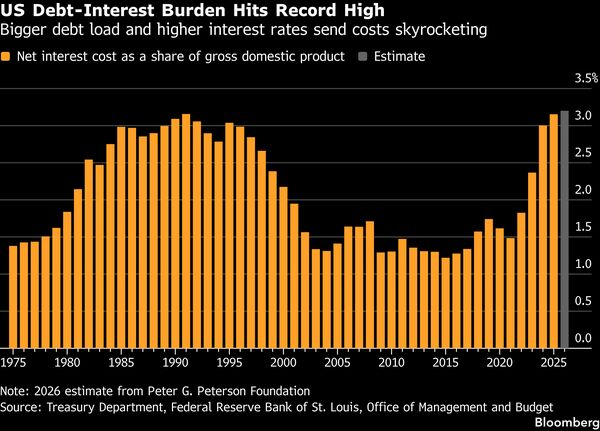
美国政府的债务利息负担在2026财年达到历史最高水平,占联邦收入的比重不断上升,并可能导致借款雪球效应,使国家在面对经济冲击时更加脆弱。
The US government’s debt interest burden reached a record high for fiscal 2026, eating up a growing share of federal revenue and risking a snowballing of borrowing that could leave the country more vulnerable to economic shocks.
财政部数据周五显示,截至9月的财政年度净利息支出达到1.05万亿美元,较2025财年的9700亿美元增长超过8%。彼得·G·彼得森基金会(Peter G. Peterson Foundation)这一研究机构预计,该费用将占国内生产总值(GDP)的3.2%,超越1991年创下的之前纪录。上一季度的GDP数据将于本月晚些时候公布。
For the year through September, net interest costs came to $1.05 trillion, up more than 8% from the $970 billion in fiscal 2025, Treasury Department data showed Friday. The Peter G. Peterson Foundation, a research group, sees the costs reaching 3.2% of gross domestic product, surpassing the previous record, reached in 1991. GDP figures for last quarter are due later this month.
这一增长既反映了需要支付利息的债务规模大幅增加 — — 一项关键指标已超过32万亿美元,比五年前多出约10万亿美元 — — 也反映了利率大幅上升。政府在可交易国债上的平均付息率在9月底达到3.52%,是五年前1.47%的两倍多。
The increase reflects both that there’s a lot more debt to pay interest on — one key measure exceeds $32 trillion, some $10 trillion more than just five years ago — but also much higher interest rates. The average rate the government paid on marketable Treasuries was 3.52% at the end of September, more than double the 1.47% five years before.
更令人担忧的是,当前收益率甚至更高,彭博美国国债指数的当前基准目前约为5%。利率上升促使财政部长斯科特·贝森特采取了非同寻常的措施来遏制这一趋势,尽管经济学家认为该国仍远离危机。债务拍卖的需求表现稳健,更高的借贷成本并未阻碍信贷流动。
What’s worse is that current yields are even higher, with the current gauge from Bloomberg’s US Treasuries index now around 5%. The rise in rates has prompted Treasury Secretary Scott Bessent into extraordinary steps to contain the move, though economists argue the nation remains distant from crisis. Demand at debt auctions has proved solid, and higher borrowing costs aren’t hindering credit flows.
布鲁金斯学会高级研究员、前联邦储备经济学家路易斯·谢纳(Louise Sheiner)表示:“这看起来不像是一场危机 — — 更像是财政能力被慢慢侵蚀。”她指出,未知的临界点在于“某些贷款人将决定不再向我们提供贷款 — — 如果这种情况发生,可能会导致财政危机”,届时财政部可能失去从市场筹集资金的能力。她补充道。
“It doesn’t seem like a crisis — it’s kind of a slow eating away” of fiscal capacity, said Louise Sheiner, a senior fellow at the Brookings Institution and former economist at the Federal Reserve. What’s unknown is the point at which “some lenders are going to decide not to lend to us — and if that happens, that could lead to a fiscal crisis,” with the Treasury losing access to raise money from markets, she said.
TD 证券美国利率策略主管根纳迪·戈德堡格表示,目前缓解更深层担忧的一个因素是,该国名义国内生产总值增长率——这对企业收入和税收等至关重要——高于美国国债收益率。第二季度名义年同比国内生产总值增长率为6.3%。戈德堡格在最近的一份报告中写道:“财政末日尚未降临。”
Gennadiy Goldberg, head of US interest rates strategy at TD Securities, said one thing staving off deeper concerns for now is that the nation’s nominal GDP growth rate — which is key for things like corporate revenues and tax receipts — is higher than US Treasury yields. The nominal year-on-year GDP gain for the second quarter was 6.3%. “A fiscal apocalypse is not upon us just yet,” Goldberg wrote in a recent note.
“尽管利率在上升,但我们某种程度上仍在应对,”国会预算办公室主任菲利普·斯瓦格尔在10月8日明尼阿波利斯的一次活动中表示。同时,他警告称,财政动态恶化确实使国家日益脆弱。“只要出现负面冲击,利率就会因各种原因上升,”此时可能出现“涡轮增压效应”。在这种情形下,利率上升的冲击“会反馈到赤字,反馈到债务,再反馈到对经济的利率上升”,斯瓦格尔说道。
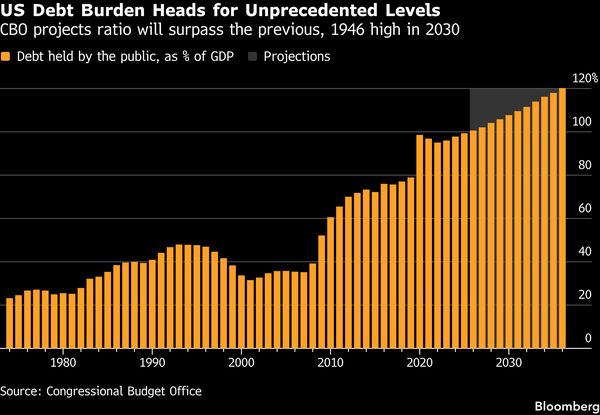
“Somehow we’re managing, even with interest rates going up,” Congressional Budget Office Director Phillip Swagel said in an Oct. 8 event in Minneapolis. At the same time, he cautioned that deteriorating fiscal dynamics do leave the nation increasingly prone. “Anytime there’s a negative shock, interest rates rise for whatever reason” there can be a “turbocharger effect.”In that scenario, the shock of higher rates “feeds into the deficit, feeds into the debt, feeds back into interest rates to the economy,” said Swagel, whose agency in February projected that the debt-to-GDP ratio will hit a record surpassing 106% in 2030.
他的机构在2月曾预测,债务占国内生产总值的比率将在2030年达到创纪录的106%以上。这名前财政部官员还表示,虽然他长期一直在传递同样的财政信息,但过去两年,市场参与者的兴趣有所增加。
The former Treasury official also said that, while he’s been delivering the same fiscal message for a long while, the past two years, market participants have been more interested.
利息成本如今已成为联邦支出列表中排名前三的最大项目,自2022年以来已增长超过一倍。仅次于社会保障和医疗保险——这两项为老年美国人提供服务的联邦巨头项目,其成本随着受益人人数以百万计的增加而逐年攀升。国防部和医疗补助位列前五。
Interest costs are now one of the top three biggest item on the list of federal outlays, after having more than doubled since just 2022. It’s only exceeded by Social Security and Medicare, the giant federal programs for older Americans, whose costs escalate each year as beneficiary rolls climb by the million. The Defense Department and Medicaid round out the top five.
上次利息成本占债务的比重达到当前水平时,美国政治界曾为应对挑战而做好准备。乔治·H·W·布什总统曾因在1990年通过一揽子增税计划而背弃其“无新税收”承诺,就在利息成本比率达到峰值之前。他的继任者比尔·克林顿随后在1993年进一步提高了税收。
The last time interest costs as a share of the debt were around current levels, American politics girded to address the challenge. President George H.W. Bush famously reneged on his no-new-taxes pledge byg a package of increases in 1990, just before the interest-cost ratio peaked. His successor Bill Clinton went on to boost levies further in 1993.
冷战结束时,国防开支也出现下滑,这有助于改善财政状况。到1990年代末,随着互联网和个人电脑的普及,经济增长回升,带动了财政收入的增加。
The end of the Cold War also saw a slump in spending on defense, bolstering the fiscal picture. By the late 1990s, a pickup in economic growth amid the diffusion of the internet and personal computing was propelling revenues.
如今,贝森特及其他特朗普政府官员一直在宣传人工智能热潮作为一种增长刺激因素,认为它将有助于降低债务比率。然而,预算专家们持怀疑态度。他们认为,国防和福利项目的支出似乎将继续攀升,而国内生产总值的增长可能不足以有效拉动财政收入。
Today, Bessent and other Trump administration officials have been touting the artificial intelligence boom as a growth stimulus that will help bring down the debt ratio. Budget experts, however, are skeptical. Spending on defense and entitlement programs appears set to keep climbing, while GDP gains aren’t likely to be fast enough to stoke revenues sufficiently, they say.
“问题只会越来越严重,因此我们不应该争论是否要等到灾难发生才行动——我们应该现在就着手解决,”彼得森基金会政策执行副总裁布雷特·洛珀说。“摆脱这个问题将非常困难。”今年净利息支出增加了814亿美元,如果利率继续上升,这一数字可能会被远远超过。美联储预计将至少再次上调其隔夜基准利率——目前为3.75%至4%——这将推高贝森特越来越倚重的短期债务成本。
“The problems only getting worse, so we shouldn’t be debating whether to wait for the catastrophe — we should be working on it now,” Brett Loper, executive vice president of policy at the Peterson Foundation. “It’s going to be really hard to climb out of this problem.”This year’s increase in net interest payments, at $81.4 billion, could be dwarfed if rates keep rising. The Fed is expected to hike its overnight benchmark rate — currently at 3.75% to 4% — at least once more, which would drive up the costs of the short-term debt Bessent has increasingly favored.
根据TD证券的计算,如果收益率曲线整体上升100个基点,2027年的利息成本将增加3100亿美元。
A 100 basis-point rise across the yield curve would drive up 2027 interest costs by $310 billion, according to calculations by TD Securities.
“我不认为财政危机迫在眉睫,我们仍然拥有一个相当强劲的经济,”哈佛大学经济学教授、曾在奥巴马政府时期任职于财政部的凯伦·戴纳说。她还指出,利率仍未回升至三四十年前的水平。
“I don’t think a fiscal crisis is imminent, we still have a pretty strong economy,” said Karen Dynan, a Harvard University economics professor who served at the Treasury in the Obama administration. And rates still aren’t back to levels from three or four decades ago, she noted.
与此同时,“债务如此之高,净利息支出真的很重要——它们将导致债务雪球效应,”她说。“利率和利息支出相对于国内生产总值的增加,可能会引发公众对行动的压力。”
At the same time, “with debt so high, net interest payments really matter — they will lead to a snowballing of debt,” she said. “The increase in interest rates and in interest payments relative to GDP, that may bring public pressure for action.”