来自Rocky Swift的欧洲和全球市场前瞻:韩国初创公司开局不利,令本周备受期待的AI超大规模企业公告蒙上阴影。
A look at the day ahead in European and global markets from Rocky Swift A rocky start for a South Korean startup cast a shadow over highly anticipated announcements by AI hyperscalers this week.
AI基础设施公司Elice Group(0158S0.KQ)周二股价较其首次公开发行价下跌近30%,而科技股权重的KOSPI(.KS11)指数亦下跌近4%,显示出在市场抛售导致部分交易受挫后,情绪仍显摇摆。
AI infrastructure company Elice Group (0158S0.KQ) sank nearly 30% below its initial public offering price on Tuesday, while the tech-heavy KOSPI (.KS11) gauge lost nearly 4%, showing shaky sentiment after a market selloff that derailed some deals.
随着季度财报的发布,主要AI企业的巨额支出计划日益成为焦点。据高盛(Goldman Sachs)称,Facebook母公司Meta Platforms(META.O)将于周三发布财报,它是五家预计明年将合并资本支出提升至约1.2万亿美元的AI超大规模企业之一。
Along with quarterly results, the massive spending plans of the major AI players are increasingly in focus. Facebook operator Meta Platforms (META.O), due to report on Wednesday, is one of five AI hyperscalers expected to increase combined capital expenditure to about $1.2 trillion next year, according to Goldman Sachs.
随着基础设施规模持续扩大、借贷成本飙升,投资者正在质疑:“每一美元的AI资本支出是否真的能带来超过其融资成本的回报?”State Street Investment Management亚太地区投资策略与研究主管宁慧 Liu 如是说。
As infrastructure plans grow ever larger and borrowing costs soar, investors are questioning "whether every dollar of AI capex earns more than it costs to finance," said Ninghui Liu, head of investment strategy and research for APAC at State Street Investment Management. On the docket today, Netflix (NFLX.O) is expected to report slowing revenue growth in the third quarter, while SpaceX (SPCX.O) is forecast to report $12.74 billion in quarterly revenue.
今日待报公司方面,Netflix(NFLX.O)预计将报告第三季度收入增长放缓,而SpaceX(SPCX.O)则被预测将报告季度收入达127.4亿美元。通用汽车(GM.N)、孩之宝(HAS.O)、哈里伯顿(HAL.N)和3M(MMM.N)等更成熟的公司名单也将于周二发布财报。
General Motors (GM.N), Hasbro (HAS.O), Halliburton (HAL.N), and 3M (MMM.N) are among the more-established names due to report on Tuesday. Oil prices resumed their climb on Tuesday as it seemed unclear whether US President Donald Trump would go through with a waiver of sanctions on some Russian energy exports, while fresh violence in the Middle East heightened the risk of supply disruptions.
周二,油价重新走高,因为尚不清楚美国总统唐纳德·特朗普是否会对部分俄罗斯能源出口实施制裁豁免,而中东地区的新一轮暴力冲突又加剧了供应中断的风险。
Inflationary pressures from elevated oil prices have put most major central banks on a tightening bias, though with a careful eye on whether economies are resilient enough to absorb higher interest rates.
油价上涨带来的通胀压力已使多数主要央行转向紧缩倾向,尽管它们仍在密切关注经济是否具备足够韧性以承受更高利率。
Recent comments from Federal Reserve officials, including Chair Kevin Warsh, suggest policymakers are in no rush to hike rates again.
美联储官员的近期表态,包括主席凯文·沃什(Kevin Warsh)在内,表明政策制定者目前并无再次加息的紧迫意愿。
European Central Bank policymaker Martin Kocher is due to speak later on Tuesday, as well as ECB policymaker and Finnish central bank governor Olli Rehn.
欧洲央行政策制定者马丁·科赫尔将于周二晚些时候发表讲话,此外还有欧洲央行政策制定者兼芬兰央行行长奥利·雷恩。英格兰银行货币政策委员会成员梅根·格林将在伦敦政治经济学院发表演讲。
Bank of England Monetary Policy Committee member Megan Greene will deliver a speech at the London School of Economics. In the economic data calendar, the US Census Bureau is expected to say housing starts rose to 1.305 million in September from 1.275 million in August, while building permits may have increased to 1.395 million from 1.403 million.
在经济数据日历方面,美国人口普查局预计将表示,9月份住房开工量从8月份的127.5万套升至130.5万套,而建筑许可可能从140.3万套增至139.5万套。
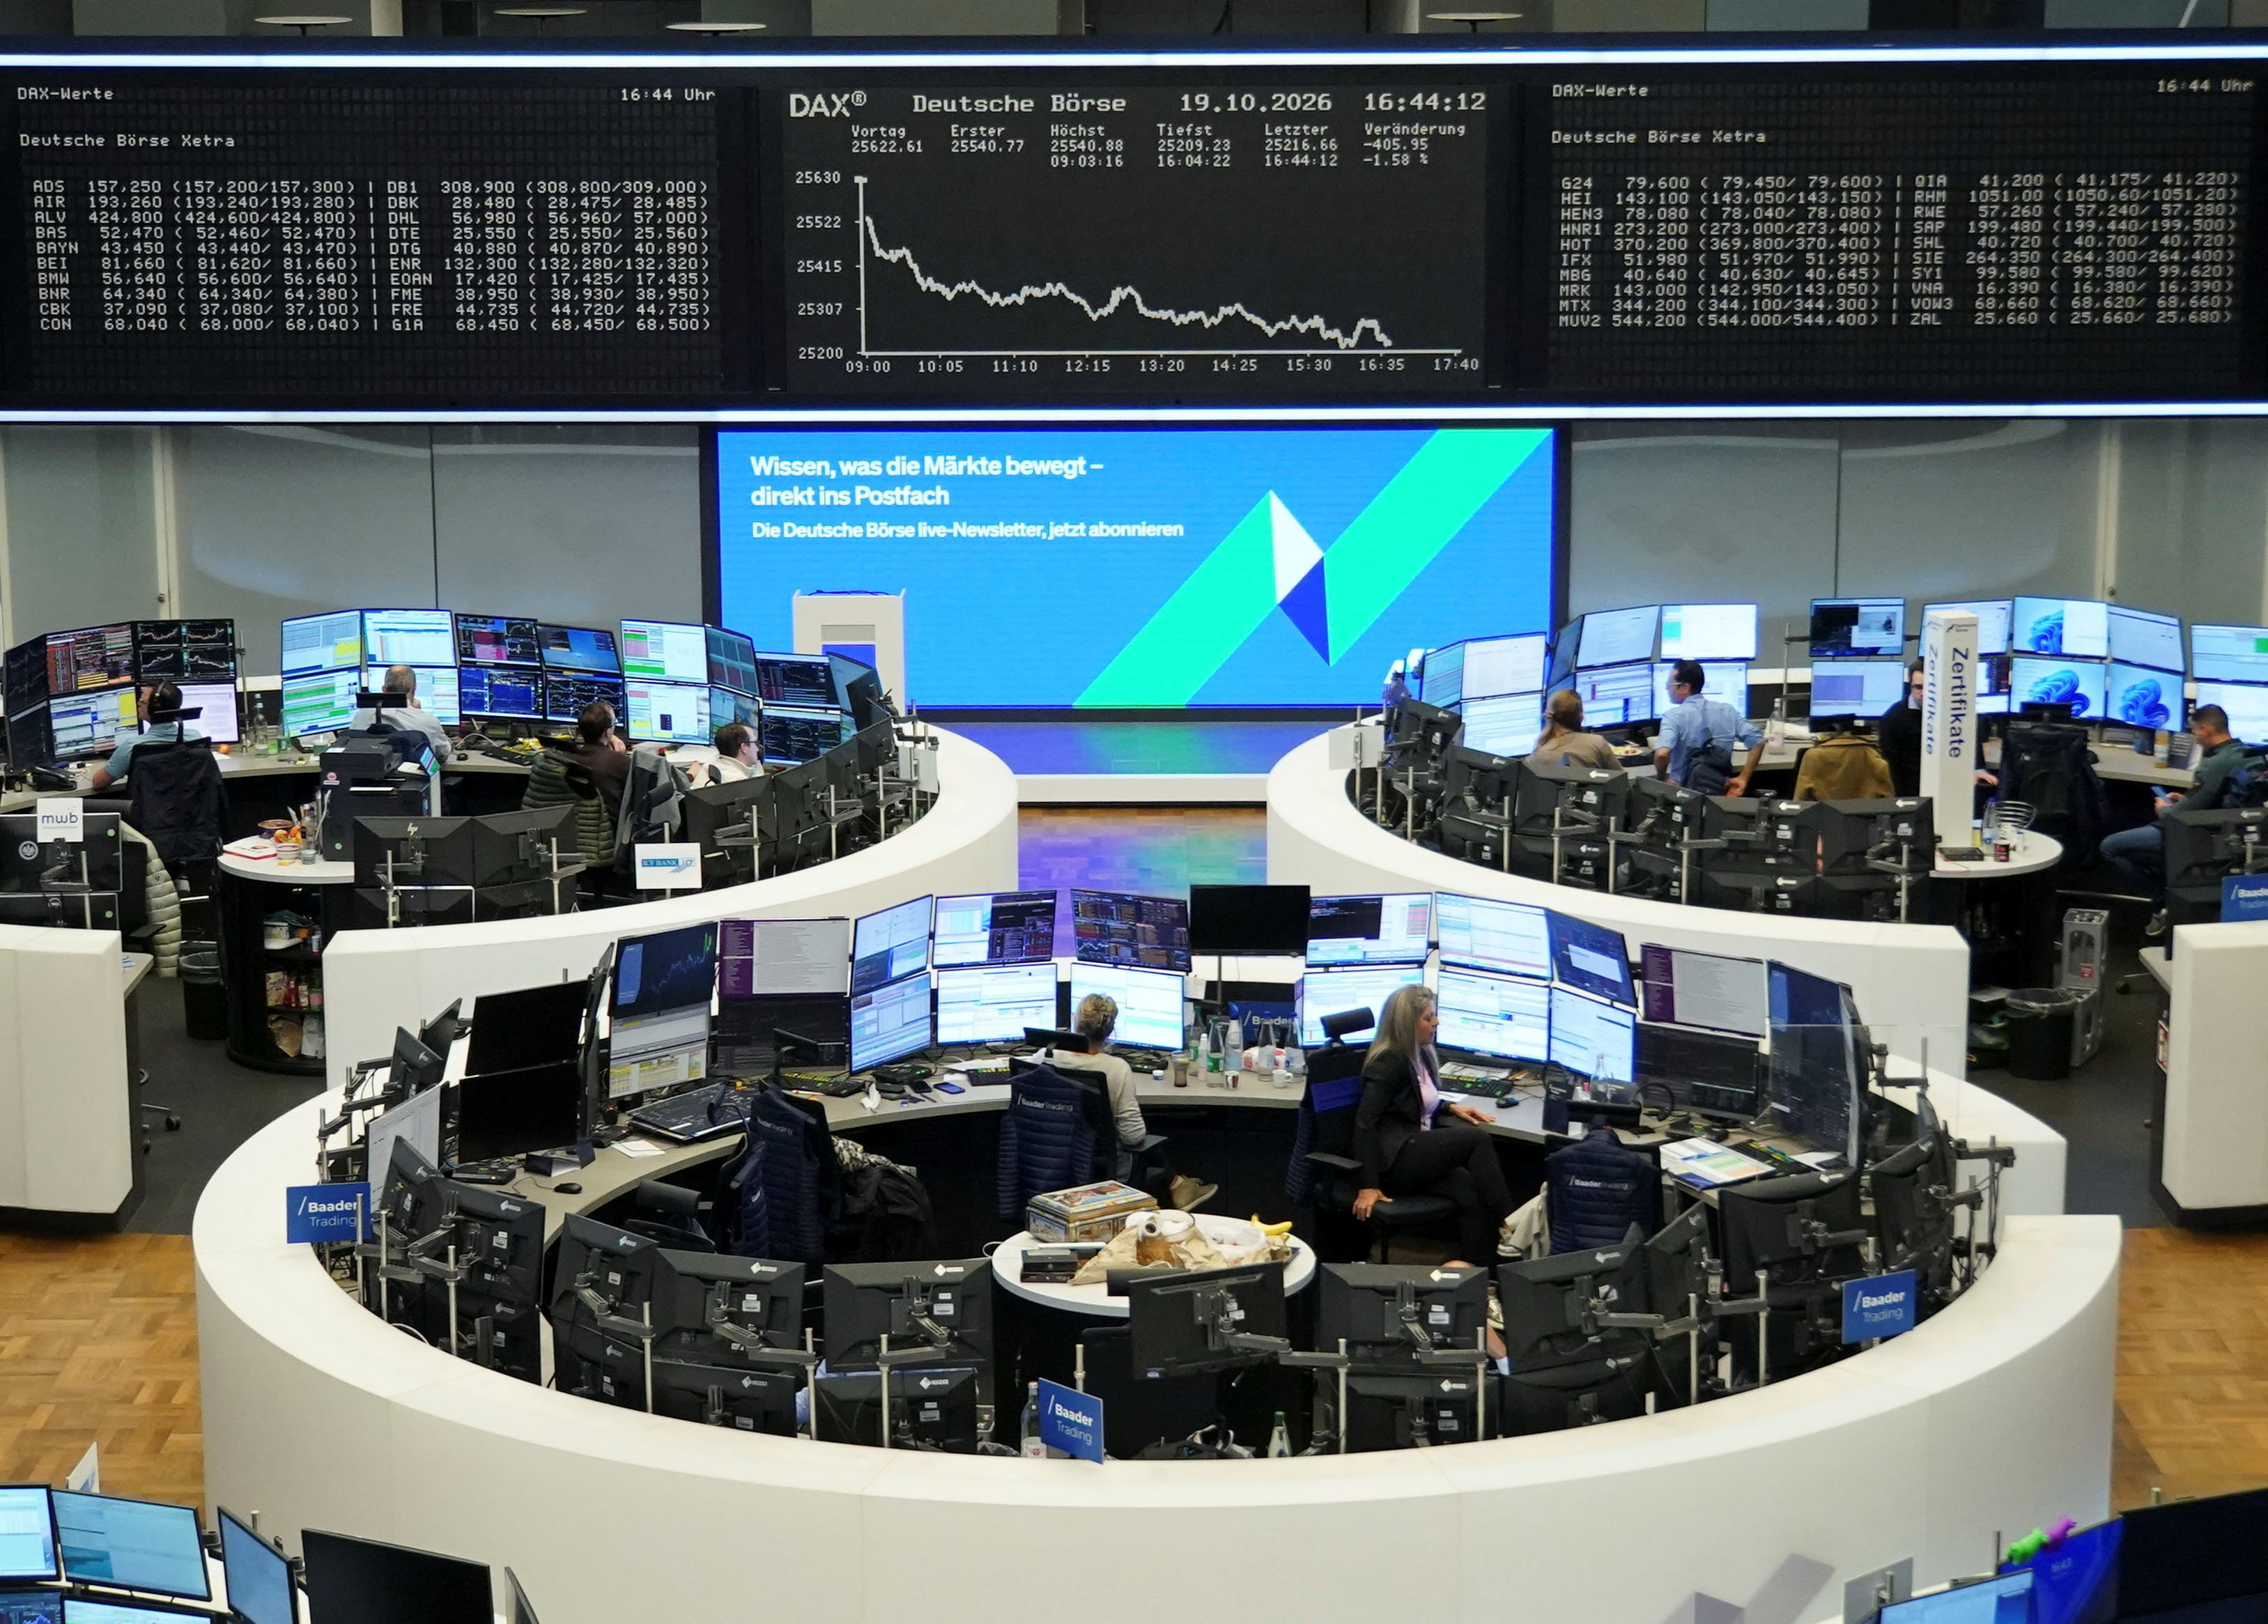
In early European trades, the pan-region Euro Stoxx 50 futures were down 0.63%, German DAX futures sank 0.39% and FTSE futures were down 0.48%.
在早盘欧洲交易中,泛欧洲区域的欧洲斯托克50指数期货下跌0.63%,德国DAX指数期货下跌0.39%,富时指数期货下跌0.48%。美国股票期货,即标普500电子迷你合约,在7742点时上涨0.1%。可能影响周二市场的关键发展:财报:德意志博塞AG、奈飞、RTX、SpaceX、通用电气、3M、通用汽车、哈斯博德国9月份生产者价格指数英国8月份就业数据欧元区经常账户(8月份)欧元区和德国ZEW调查拍卖:德国 – 重新开放3年期和27年期政府债务;英国 – 重新开放10年期政府债务
US stock futures, the S&P 500 e-minis , were up 0.1% at 7,742. Key developments that could influence markets on Tuesday: Earnings: Deutsche Boerse AG, Netflix, RTX, SpaceX, General Electric, 3M, General Motors, Hasbro Germany Producer Prices for September United Kingdom jobs data for August Euro zone current account (August) ZEW Surveys for euro zone, Germany Auctions: Germany – Reopening of 3-year and 27-year government debt; United Kingdom – Reopening of 10-year government debt