包括 T. Rowe Price Associates Inc. 和 Invesco 在内的高端投资者,正考虑涉足垃圾债券中风险最低的角落,此前更广泛的抛售导致估值下降。
High-grade investors, including T. Rowe Price Associates Inc. and Invesco, are looking at dipping into the least risky corner of junk debt after a broader selloff pushed valuations lower.
他们正考虑购买评级处于 BB 级的高收益债券,这些债券在最近几周已跌至 3 月以来的最低水平。这是一笔押注美国企业健康状况的赌注,尽管人工智能和全球战争可能会给最脆弱的借款人带来压力。
They’re considering buying high-yield bonds rated in the BB tier that in recent weeks have reached their cheapest levels since March. It’s a bet on the health of US companies, even as artificial intelligence and global wars threaten to pressure the weakest borrowers.
T. Rowe Price 全球投资级债券主管 Steven Boothe 表示,强劲的宏观经济背景为这些高质量垃圾债券提供了强有力的安全网。
A robust macroeconomic backdrop is providing a strong safety net for these higher-quality junk bonds, said Steven Boothe, head of global investment grade at T. Rowe Price.
Boothe 说:“当我想到美国企业的基本面健康状况以及高收益市场中质量较高的板块时,这仍然是一个部署风险的有吸引力的市场组成部分。”
“When I think about the underlying fundamental health of corporate America and the higher quality segments of the high-yield market, this remains an attractive component of the market to deploy risk,” Boothe said.
对最危险的高收益债务的担忧已经酝酿了数月。许多垃圾债券持有者一直在抛售市场上评级最低的证券,即 CCC 级及以下的证券,导致这些票据的风险溢价平均升至 10 个百分点以上,这一水平通常被视为发出了困境信号。
Fears about the riskiest high-yield debt have been ramping up for months. Many junk bond holders have been shedding the lowest-rated securities in the market, those in the CCC tier and below, pushing risk premiums on those notes to an average of more than 10 percentage points, a level often seen as signaling distress.
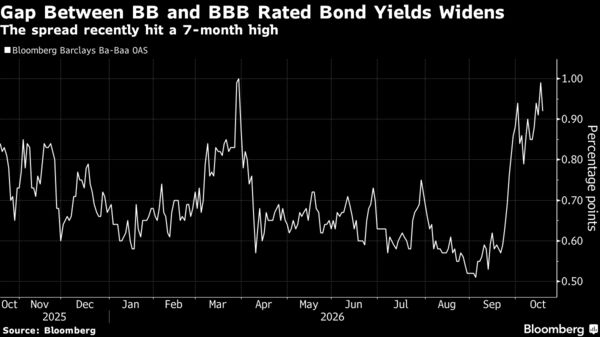
一部分资金转而流入了 BB 级债券。上个月来自垃圾债券投资者的需求帮助 BB 级债券相对于 BBB 级证券(最弱的投资级级别)成为 21 年来最昂贵的。自 9 月下旬以来的广泛债券市场抛售使估值回落到再具吸引力的水平,促使高端投资者跨入垃圾债务池,以仅略微增加的风险锁定更高的收益率。
A chunk of the money was poured into BB bonds instead. Demand from junk bond investors last month helped make BBs the most valuable they’ve been in 21 years compared with securities in the BBB tier, the weakest investment-grade levels. The broad bond market selloff since late September has taken valuations to levels that are attractive again, prompting high-grade investors to cross into the junk debt pool and lock in a higher yield for only a marginal increase in risk.
Guggenheim Investments Holdings 董事总经理兼投资组合经理 Adam Bloch 表示:“具体就双 B 级市场而言,我们认为其跑赢投资级市场其余部分的可能性相当大。”
“When it comes to the double B part of the market specifically, we think there’s a decent chance for some outperformance there versus the rest of the investment grade market,” Adam Bloch, managing director and portfolio manager at Guggenheim Investments Holdings, said.
布洛赫表示,Live Nation Entertainment Inc.(Live Nation娱乐公司)本月初发行的14亿美元债券,就是“在双B级别中具有合理性的一次性机会”的一个例子,适合投资级投资者。尽管该公司评级属于垃圾级,但其拥有强劲的现金流和较低的债务负担,更接近三B级借款人。
Bloch said Live Nation Entertainment Inc.’s $1.4 billion debt offering earlier this month is an example of “one-off opportunities in double B that make sense” for investment grade investors. While rated junk, the company has a strong cash flow and low debt load that’s closer to a triple B borrower.
降低质量标准确实伴随着额外风险,即使与垃圾债池中的其他债券相比,双B级公司的风险相对较小。根据标普全球公司的数据,BB级借款人的三年累计违约率为4.17%,而BBB级仅为0.91%。但B级借款人的违约率跃升至12.41%,CCC级更高达45.67%。
Moving down in quality does comes with extra risk, even if it’s relatively small for double B companies when compared with the rest of the junk-debt pool. Three-year cumulative default rates for BB rated borrowers are at 4.17% compared with just 0.91% for those rated BBB, according to data from S&P Global Inc. But those rates jump to 12.41% for B rated and 45.67% for CCC rated ones.
精选也至关重要,稳健的盈利能力、强劲的利润率和正的自由现金流是投资组合经理关注的一些标准。“这些就是我们喜爱的双B级债券类型,我们现在很乐意尝试投资,”Invesco Advisers Inc.(景顺投资顾问公司)美国投资级信用研究主管Bixby Stewart(比克斯比·斯图尔特)表示。
Selectivity is also key, with robust earnings capacity, strong margins and positive free cash flow being some of the criteria portfolio managers are looking at. “Those are the types of double B’s that we love and that we’re happy to dip our toes in the water now,” said Bixby Stewart, head of US Investment Grade Credit Research at Invesco Advisers Inc.
斯图尔特称,该公司在其管理的某些企业债券基金中,将8%至14%的资产配置于高收益债券。
The company allocates between 8% and 14% in high-yield bonds in some of its corporate bond funds under management, Stewart said.
布斯表示,虽然美国投资级债券供应过剩为投资者提供了有吸引力的持有收益,但高收益债券同样面临发行量大的风险,这可能会使双B级与三B级债券的利差维持在近期区间的宽幅端。
While a supply glut of US investment grade bonds provides investors with attractive carry, heavy issuance risks in high-yield bonds as well are likely to keep the spread between double B and triple B bonds pinned at the wider end of recent ranges, Boothe said.
随着超大规模云服务商竞相为AI数据中心建设融资,今年投资级市场的企业发债量达到创纪录水平。债务洪流淹没了投资者需求,引发了“消化不良”的担忧,推高了投资级利差。
Corporate issuance in the investment-grade market hit record levels this year as hyperscalers raced to fund AI data center buildouts. The debt deluge has overwhelmed investor demand and spurred concerns of “indigestion,” pushing investment-grade spreads wider.
Oracle Corp.(甲骨文公司)一直在大举借贷以资助大规模数据中心投资,被视为将增加这一压力。
Oracle Corp., which has been borrowing heavily to finance massive investments in data centers, is seen adding to the pressure.
“三B俱乐部中有一个成员非常特殊,那就是甲骨文,”哥伦比亚线针投资公司的投资组合经理Ed Al-Hussainy表示。“因为甲骨文发行了如此多的债务,它现在是超大规模云服务商中资产负债表最弱的,因此其交易价格与其他三B级债券相比非常便宜。”在标普全球将这家科技巨头的信用评级下调至BBB-——即最低投资级档位——后,该公司正摇摇欲坠地处于垃圾级边缘,因为它烧钱的速度快于产生收入的速度。
“There’s one member of the triple-B club that’s very unusual, and that’s Oracle,” said Ed Al-Hussainy, portfolio manager at Columbia Threadneedle. “Because Oracle is issuing so much debt, it has the weakest balance sheet now of the hyperscalers and so it trades very cheap to the other triple-B names.”The company is teetering on the edge of junk status after S&P Global cut its credit rating to BBB-, the lowest investment-grade rung, as the tech giant burns through cash faster than it can generate revenue.
甲骨文的一位代表在电子邮件声明中表示,维持投资级信用评级是公司的“首要任务”,并引用了首席财务官Hilary Maxson近期的言论。
Maintaining an investment grade credit rating is the company’s “first priority,” a representative for Oracle said in an emailed statement, citing recent comments from chief financial officer Hilary Maxson.
垃圾债券市场也出现了供给压力积聚的迹象。一系列大额垃圾债券发行——包括软银集团100亿美元的交易和派拉蒙天空舞公司124亿美元的交易——使9月成为今年该市场最繁忙的月份。
There are signs supply pressures are building up in the junk bond market, too. A string of chunky junk bond offerings — including a $10 billion deal from SoftBank Group Corp. and $12.4 billion from Paramount Skydance Corp. — turned September into the busiest month this year for the market.
这促使高盛集团首席信用策略师Amanda Lynam近期警告称,高收益债务可能会出现此前曾淹没投资级市场的那种“阶段性消化不良”。
That’s prompted Goldman Sachs Group Inc.’s chief credit strategist Amanda Lynam to warn recently that high-yield debt may see the same sort of “episodic indigestion” that overwhelmed the investment grade market earlier.
随着投资者持续抛售最垃圾的垃圾债券,CCC级债务的收益率已从1月的10%左右飙升至15%以上,达到2022年以来的最高水平。迫在眉睫的到期墙也将持续给最具风险的债务带来压力。根据穆迪评级的一项研究,未来两年到期的高收益债务中,约三分之一来自陷入困境的公司。
As investors continue to flee the junkiest of junk bonds, yields on CCC rated debt have surged to over 15% from around 10% in January, the highest level since 2022. A looming maturity wall will also keep pressure on the riskiest debt. Distressed companies account for about a third of maturing high-yield debt over the next two years, according to a study by Moody’s Ratings.
“高收益基金经理正在撤离那些风险较高的市场板块,并希望提升质量,”Voya Investment Management美国投资级企业债主管Travis King表示,“这也使他们转向BB级债券。”
“High-yield managers moving out of those riskier parts of the market and wanting to go up in quality,” are also turning to BB rated bonds, said Travis King, head of US investment-grade corporates at Voya Investment Management.
阿波罗全球管理公司首席经济学家托尔斯滕·斯洛克在最近的一份报告中表示,昂贵的借贷成本意味着垃圾债券将面临“缓慢挤压”,建议投资者转向质量更高的企业债券以获取有吸引力的收益率。
Apollo Global Management Inc. Chief Economist Torsten Slok said in a recent note that expensive borrowing costs mean junk bonds are in for a “slow squeeze,” advising investors to move to higher-quality corporate bonds to capture attractive yields.
他写道:“廉价货币时代的账单正首先落在最脆弱的资产负债表上”,由私募股权支持的科技公司将是最可能经历最大痛苦的群体之一。
“The bill from the cheap-money era is landing on the weakest balance sheets first,” he wrote, with private equity-backed technology companies among those poised to experience the most pain.