摩根士丹利表示,由于疲软的宏观经济和消费势头持续拖累市场情绪,中国股市在估值触底前恐将进一步下跌。
Chinese stocks are poised for further losses before valuations bottom, according to Morgan Stanley, as weak macroeconomic and consumption momentum continues to weigh on sentiment.
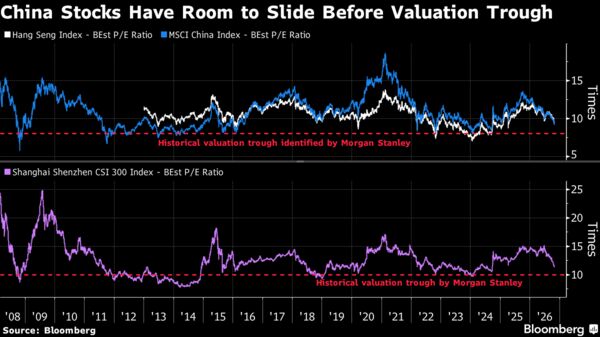
包括劳拉·王在内的分析师在周日发布的报告中写道,离岸股份可能在触及约8倍12个月远期市盈率的历史估值水平前,再下跌10%-15%。内地上市股票可能面临类似的去估值过程,远期市盈率降至约10至11倍。
Offshore shares may fall another 10%-15% before hitting their historical valuation level of about eight times 12-month forward earnings, analysts including Laura Wang wrote in a note dated Sunday. Mainland-listed equities are likely to see a similar de-rating to about 10 to 11 times forward earnings.
他们写道:“对信托税引发抛售的担忧、电商面临的压力、宏观经济走弱以及全球市场波动加剧,导致中国市场回调加速。”“过去两周的额外事态发展进一步加剧了负面势头。”中国在岸股市处于熊市之中,消费持续低迷、政策支持减弱,继续笼罩着该国的增长前景。全球人工智能股票的回调增加了压力,而香港市场仍易受全球债券收益率波动和对美联储政策路径预期的影响。
“Concerns over selling caused by trust tax, pressure on e-commerce, a weakening macro and elevated global market volatility has caused an acceleration of China’s market correction,” they wrote. “Additional developments over the past two weeks have further exacerbated the negative momentum.”China’s onshore shares are in a bear market, with persistently sluggish consumption and waning policy support continuing to cloud the nation’s growth outlook. A global retreat in artificial-intelligence stocks has added to the pressure, while Hong Kong remain vulnerable to swings in global bond yields and expectations for the Federal Reserve’s policy path.
摩根士丹利继续看好在岸股份,因为国家队正在加大对市场的支持力度。分析师称,内地股票在“与人工智能相关、硬核科技和创新型公司等营收和盈利增速较高的板块中具有更大的配置比重”。
Morgan Stanley continues to favor onshore shares as the national team steps up support for the market. Mainland equities also have “bigger concentration in the higher revenue and earnings growth segments in AI related, hard-core technology and innovation companies,” the analysts said.
在岸基准指数沪深300指数的交易估值为11.6倍12个月远期市盈率,而恒生指数的交易估值为9.5倍。
The onshore benchmark CSI 300 gauge is trading at 11.6 times 12 month forward earnings, while the Hang Seng Index trades at 9.5 times.
分析师补充称,一个值得关注的信号是国家队的高调买入,因为当政策制定者公开承诺稳定股市时,市场往往会在国家队此类买入后一至两个月触底。
One signpost to watch is high-profile buying by the national team, as the market has tended to bottom one to two months after such purchases when accompanied by public commitments from policymakers to stabilize equities, the analysts added.
研报指出:“发生的事情表明,北京目前正试图在不采取强力干预的情况下,改变边际供需平衡并确立底部。基于历史经验,这种更积极的信号释放以及仍然充足的‘干粉’,表明A股市场的企稳迹象现在可能更加明显,很可能在再过一个月或两个月左右出现。”
“What has happened demonstrates that Beijing is currently trying to change the marginal supply/demand balance and establish a floor without brute-force intervention,” according to the note. “This more proactive messaging and still ample dry powder, based on historical experience, suggests that stabilization of the A-share market could be more visible now, likely within another month or two, or so.”