2024年11月,中国30年期国债收益率首次跌破日本同期限国债收益率。这在金融市场引发了震动,加剧了人们的担忧,即中国经济易受20世纪90年代初资产价格泡沫破裂后导致日本陷入数十年通货紧缩和增长停滞的同类危机的影响。
In November 2024, the yield on China’s 30-year government bond fell below its Japanese equivalent for the first time. This was a big deal in financial markets, fanning fears that China’s economy was vulnerable to the type of crisis that condemned Japan to decades of deflation and stagnant growth following the bursting of its asset price bubble in the early 1990s.
2025年11月,中国的基准10年期国债收益率也紧随其后。尽管两国国债收益率的趋同,很大程度上也与日本在长达三十年的抗击通缩之战中取得成功有关,但中国经济的“日本化”已成为过去几年经济学家和投资者最常讨论的话题之一。
In November 2025, China’s benchmark 10-year yield followed suit. Although the convergence in the two countries’ bond yields had as much to do with Japan’s success in winning a three-decade battle against deflation, the “Japanification” of China’s economy has been one of the most talked-about themes among economists and investors in the past several years.
摩根大通在2023年8月的一份报告中表示,房地产泡沫破裂后的中国与20世纪90年代的日本之间存在一些惊人的相似之处。该行指出了两国住房危机背后的结构性原因、金融失衡加剧的规模和速度,以及严峻的人口压力。
In a report in August 2023, JPMorgan said there were some eerie similarities between post-property bust China and 1990s Japan. The bank pointed to the structural causes of both countries’ housing crises, the scale and speed of the increase in financial imbalances as well as acute demographic pressures.
不过,摩根大通表示,两者也存在关键差异。中国拥有更大的国内市场、较低的城市化率以及更大的追赶增长潜力,这使其拥有更多可以调控以提振经济的手段。此外,中国国家控制的金融体系使得“发生突然中断型债务危机的可能性更小”。
However, JPMorgan said there were crucial differences, too. China has a bigger domestic market, a lower urbanisation rate and more catch-up growth potential, giving it more levers to pull to reflate the economy. Moreover, China’s state-controlled financial system makes it so “the probability of a sudden-stop debt crisis is smaller”.
快进三年,在内需不断恶化的迹象日益增多的背景下,关于中国是否正在日本化的争论仍在继续激化。今年前9个月,消费品零售总额按年率计算仅微升1.1%。2026年前9个月固定资产投资收缩了7.2%,而房地产投资则下降了20.6%。
Fast forward three years, and the debate over whether China is turning Japanese continues to rage amid increasing signs that domestic demand is deteriorating. In the first nine months of this year, retail sales of consumer goods grew a meagre 1.1 per cent in annualised terms. Fixed asset investment contracted 7.2 per cent in the first nine months of 2026 while property investment fell 20.6 per cent.
花旗集团在10月7日的一份报告中表示,中国的“国内经济正处于衰退边缘”。该行的国内需求追踪指标已跌至疫情时期的低点以下。报告称,“疲软态势是广泛的,波及了家庭、政府和企业”。
In a report on October 7, Citigroup said China’s “domestic economy is on the verge of recession”. The bank’s domestic demand tracker has fallen below its pandemic-era low. It said the “weakness is broad-based, cutting across households, government and corporates”.
此外,信贷增长已经崩溃,由于家庭和企业对承担债务仍然保持谨慎,信贷正以有记录以来最慢的速度扩张。去年由于许多投资者转向股票而一度逼近2%的中国10年期国债收益率,已回落至1.6%的历史低点。
Furthermore, credit growth has collapsed, expanding at its slowest pace on record as households and businesses remain reluctant to take on debt. China’s 10-year bond yield, which almost hit 2 per cent last year as many investors rotated into stocks, has fallen back to a record low of 1.6 per cent.
然而,如果说三年前将中国与20世纪90年代的日本进行比较在多方面存在缺陷,那么今天将中国日本化则是一个更站不住脚的说法。如果这个世界第二大经济体正在经历“失去的十年”,为什么上个月出口额会增长36%,其中高科技产品出货量增长64%,占中国出口总额增长近一半?
Yet if comparisons with 1990s Japan were flawed on multiple counts three years ago, the Japanification of China is an even less plausible narrative today. If the world’s second-largest economy is enduring a “lost decade”, why were exports up 36 per cent last month, with shipments of hi-tech goods up 64 per cent, accounting for nearly half of China’s total export growth?
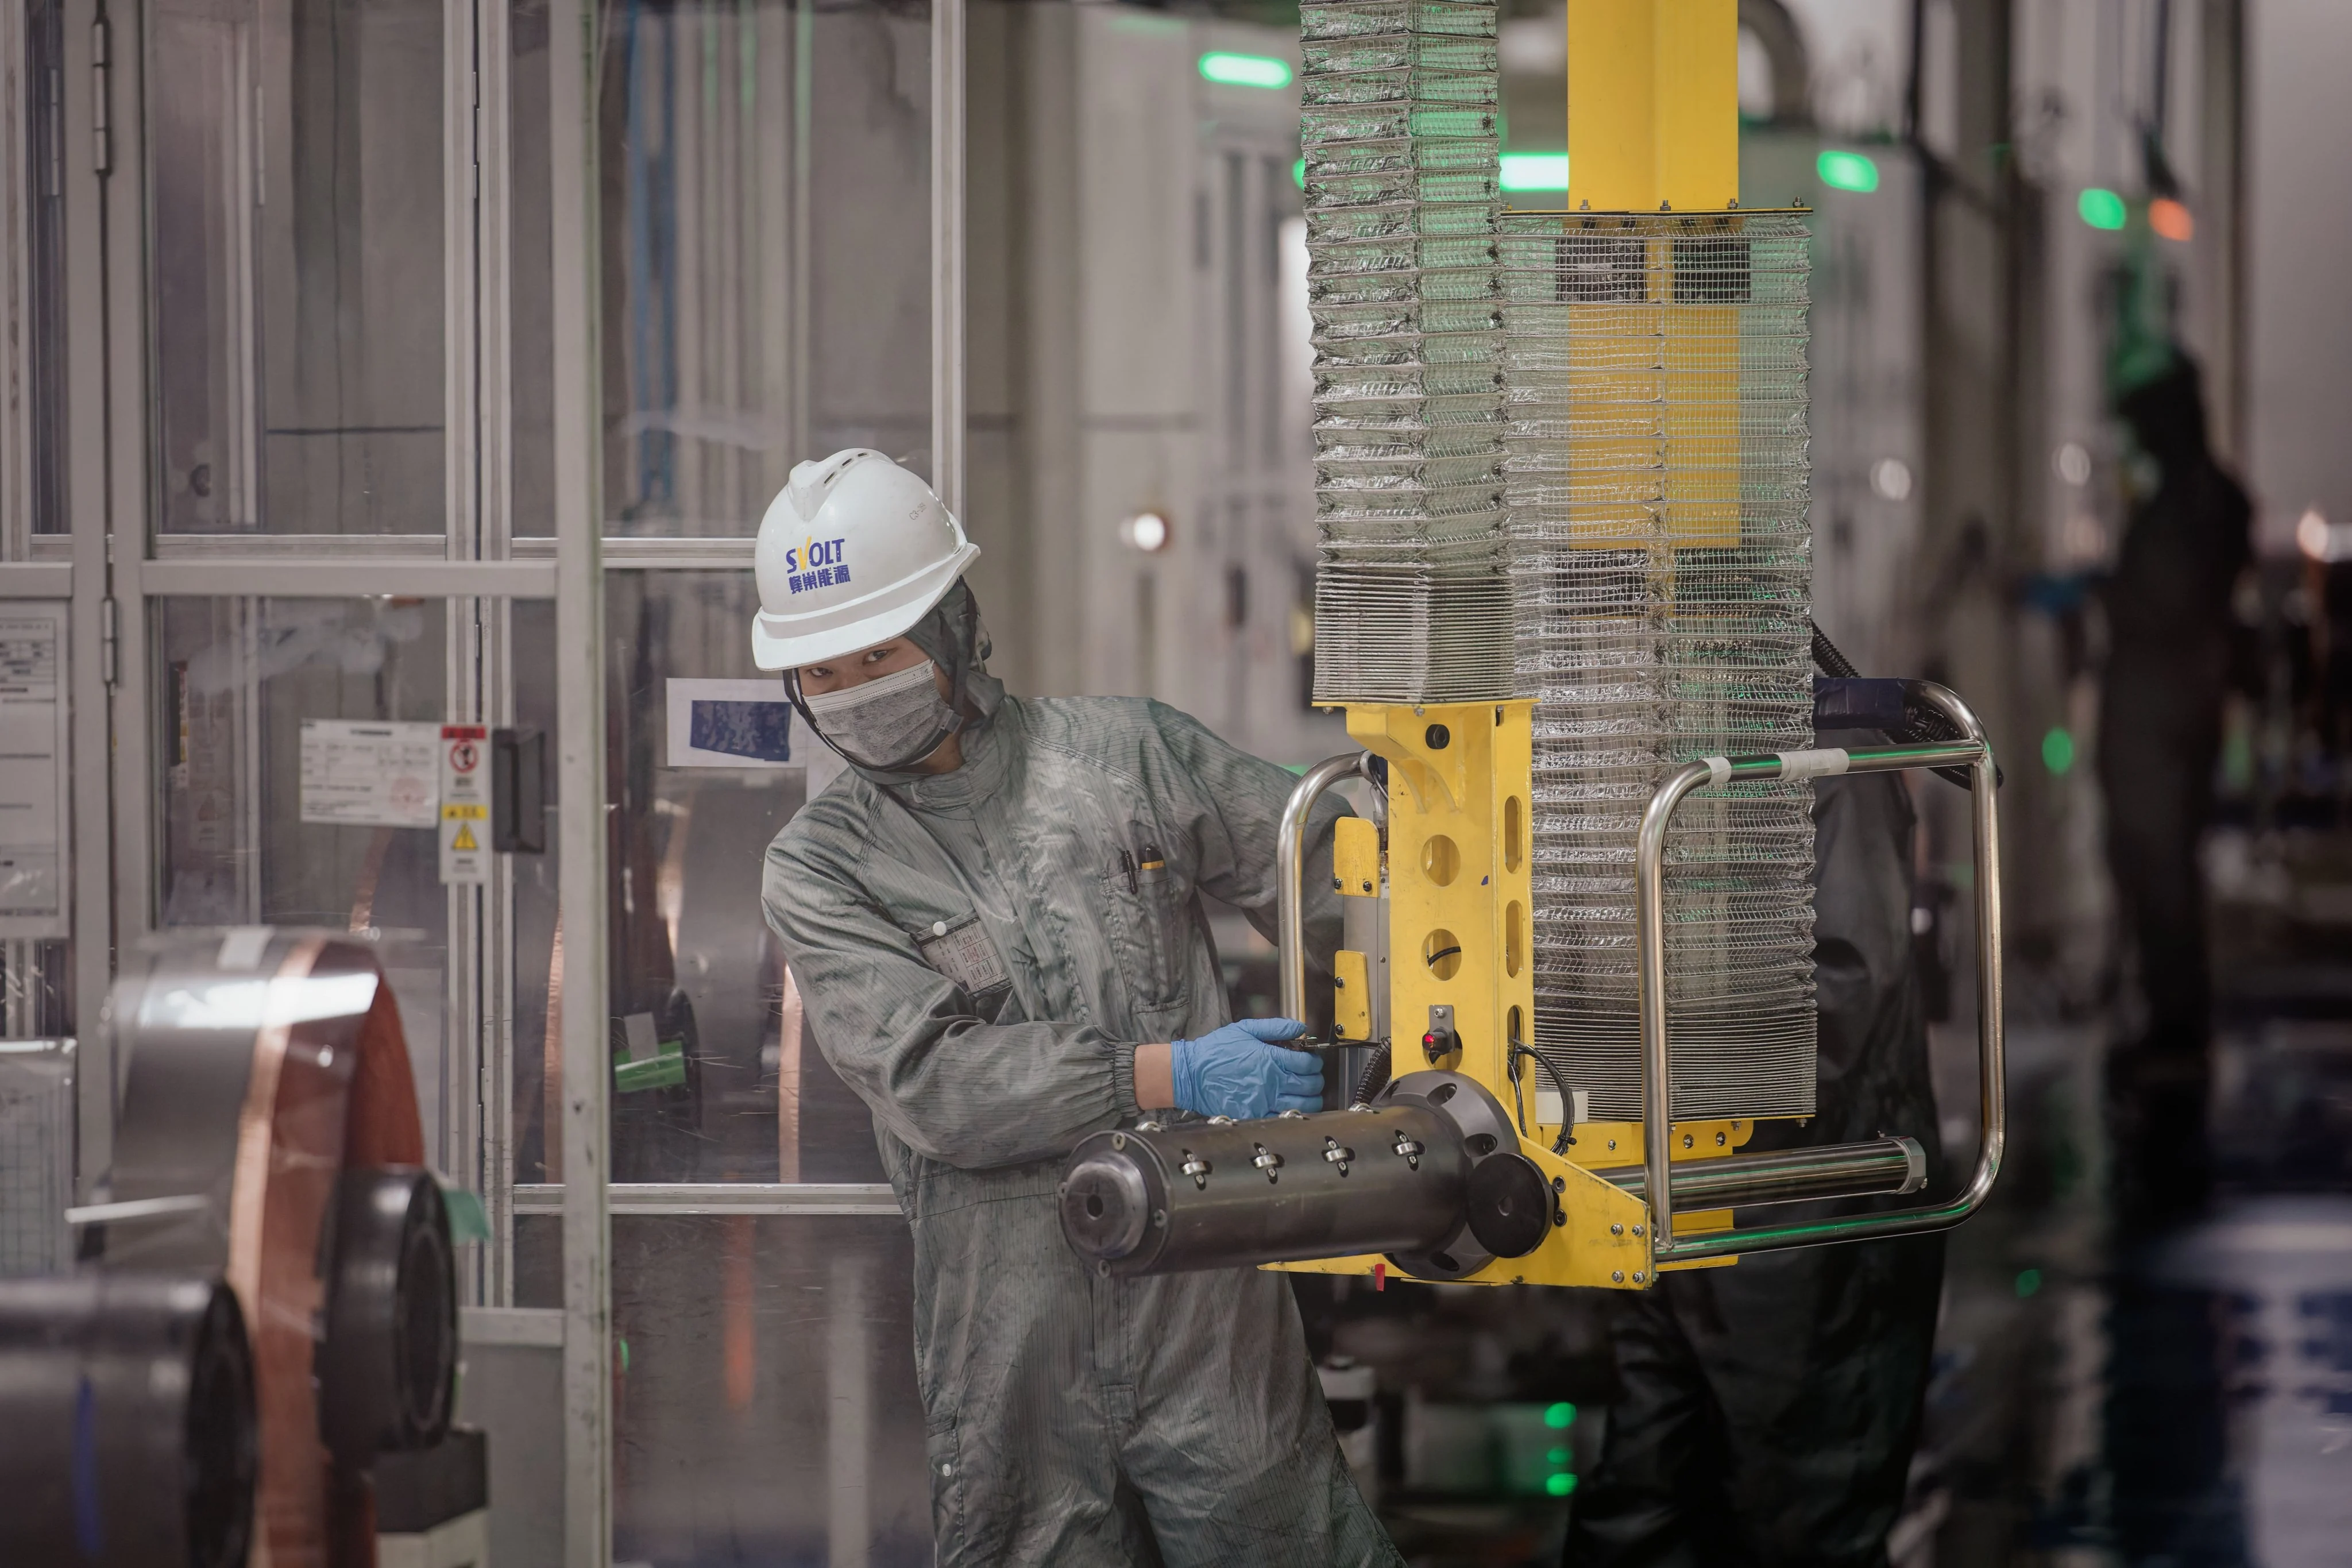
在日本泡沫破裂时,其曾经强大的制造业板块萎缩了。该国在全球制造业增值中所占的份额从1995年的23%降至2010年的11%。相比之下,中国的份额到2024年上升到了28%。事实上,自2021年住房危机爆发以来,制造业资本支出已经增加了45%。
When Japan’s bubble burst, its once formidable manufacturing sector withered. The country’s share of global manufacturing value added fell from 23 per cent in 1995 to 11 per cent by 2010. China’s share, by contrast, rose to 28 per cent by 2024. In fact, manufacturing capital expenditure has increased 45 per cent since the housing crisis erupted in 2021.
麦格理在6月份的一份报告中表示,日本的制造业资本支出在1990年至2010年间下降了14%,这“有助于解释为什么日本错过了随后互联网和半导体领域的几波技术变革浪潮”。另一方面,中国制造业“受益于疲软的人民币、显著降低的劳动力成本、持续的信贷扩张以及不断上升的[研发]支出”。
In a report in June, Macquarie said Japan’s manufacturing capital expenditure fell 14 per cent from 1990 to 2010, which “helps explain why Japan missed much of the subsequent waves of technological change in the internet and semiconductors”. Chinese manufacturing, on the other hand, “has benefited from a weak yuan, significantly lower labour costs, sustained credit expansion and rising [research and development] spending”.
虽然日本是一个在资产泡沫破裂后陷入数十年停滞的单一速度经济体,但中国毫无疑问是一个双速经济体,用国际货币基金组织的话说,“国内需求的不足已被强劲的出口增长所缓和”,从而带来了“技术进步和国际市场份额的增加”。
While Japan was a single-speed economy that stagnated for decades following the bursting of its asset bubble, China is an indisputably two-speed one in which, in the words of the International Monetary Fund, “the deficiency of domestic demand has been mitigated by strong export growth”, leading to “technological advances and gains in international market share”.
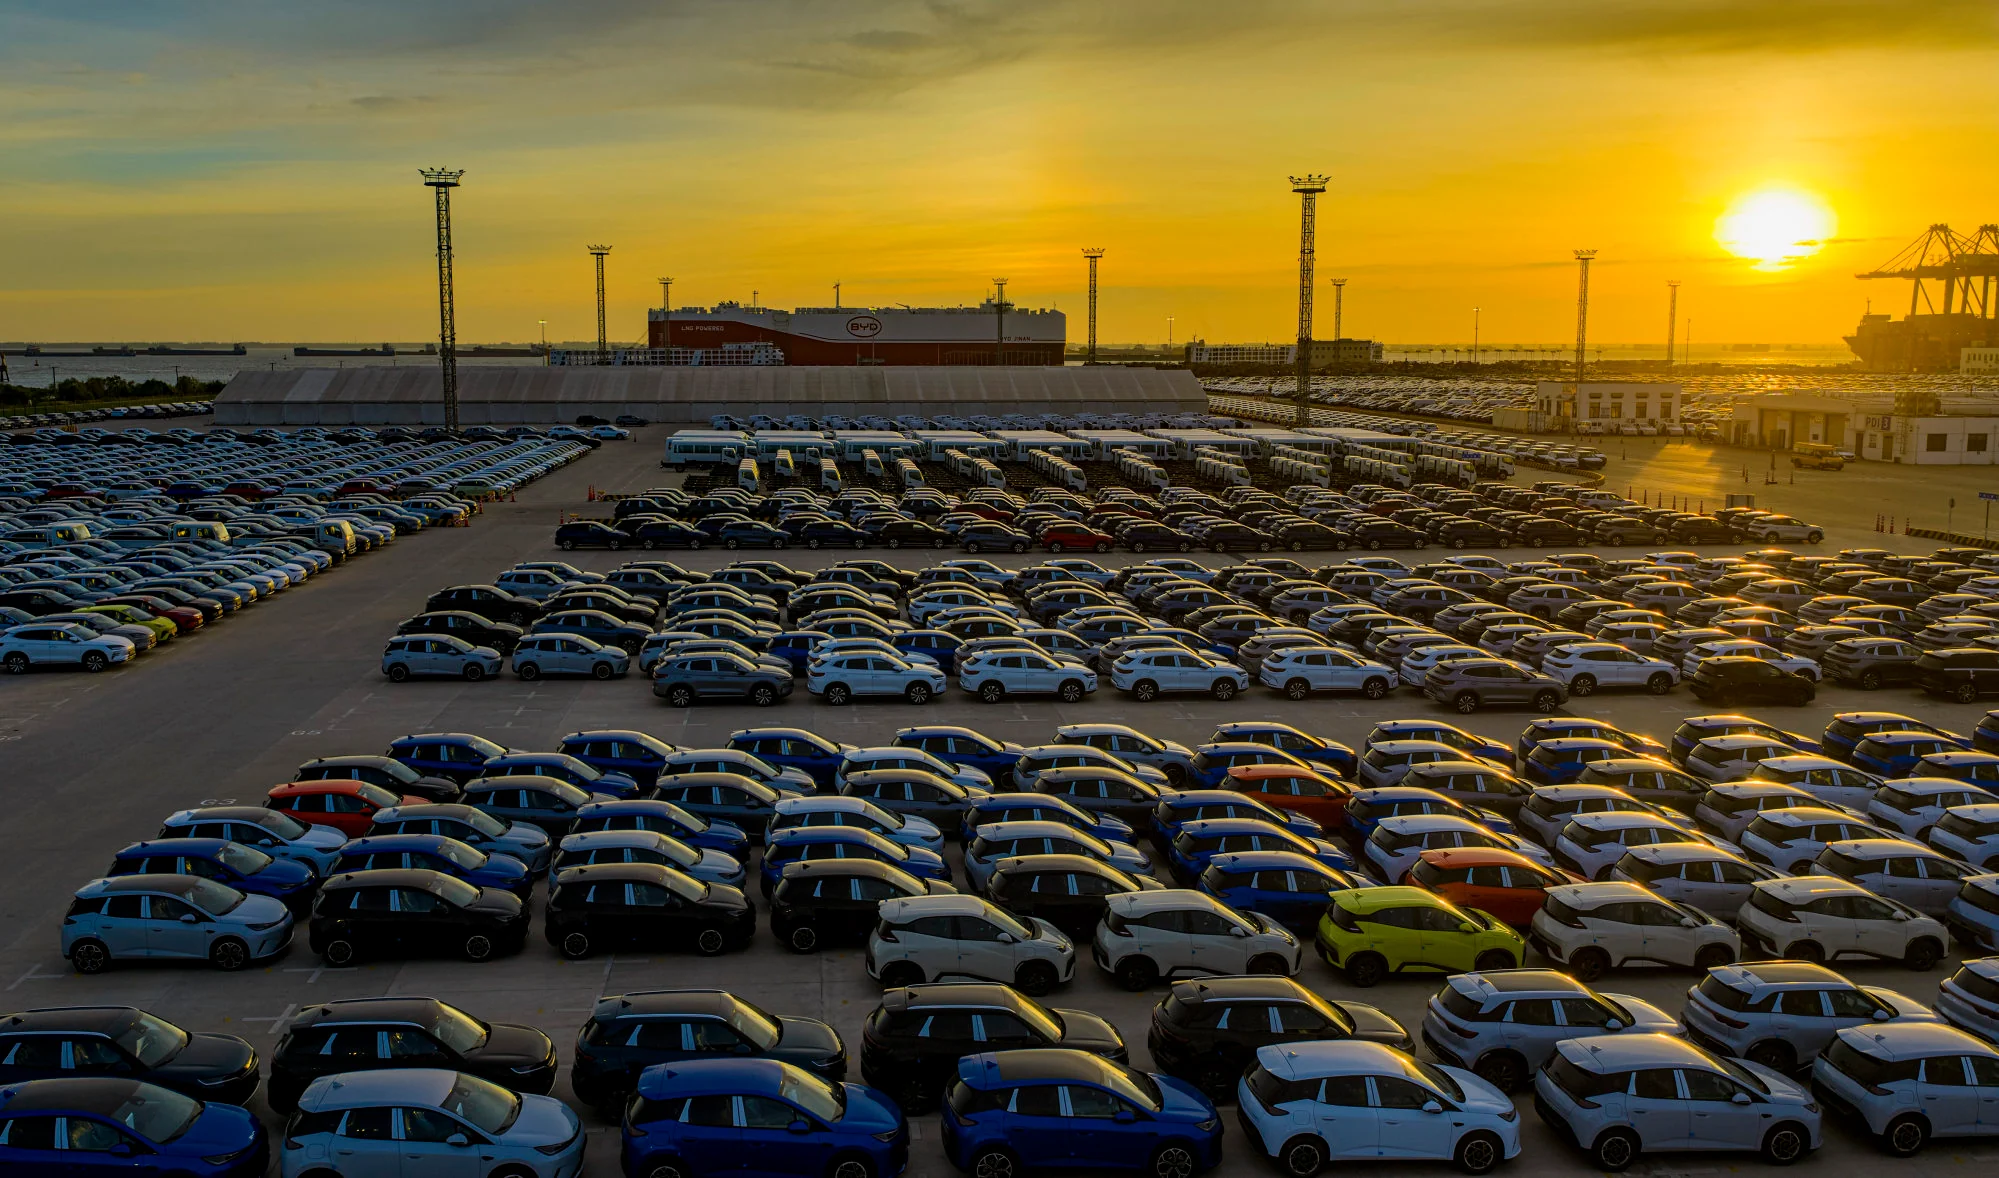
上个季度,中国汽车制造商在欧洲的销量在一个完整的季度中首次超过了日本竞争对手,占该地区总销量的12.7%。此外,人工智能浪潮一直是中国经济的强劲顺风,突显了该国作为人工智能建设制造枢纽的角色。巴克莱预计,人工智能出口今年将为经济产出贡献0.5个百分点的增长。
Last quarter, China’s carmakers outsold their Japanese rivals in Europe for the first time over a full quarter, accounting for 12.7 per cent of total sales in the region. The artificial intelligence (AI) boom, moreover, has been a strong tailwind for China’s economy, accentuating the country’s role as a manufacturing hub for the AI buildout. Barclays expects AI exports to add 0.5 percentage points to economic output this year.
只有在内需经济方面,日本化的说法才有分量。麦格理表示,中国的消费类股票“处于压抑的估值水平,暗示了日本式的‘失去的十年’情景”。即便如此,消费的持续疲软在很大程度上是由政策驱动的,因为北京正引导经济从房地产主导的扩张转向技术驱动的自力更生。
It is only in the domestic economy where the Japanification narrative carries weight. Macquarie said China’s consumer stocks “trade at depressed valuations that imply a Japan-style ‘lost decades’ scenario”. Even so, the persistent weakness of consumption is largely policy-induced as Beijing steers the economy away from property-led expansion to tech-driven self-reliance.
危险并非中国的日本化,因为人工智能驱动的出口热潮充当了对抗疲软消费的关键对冲。相反,威胁在于缺乏对经济进行再平衡的紧迫性。“出口的韧性为北京在内需疲软的情况下维持其科技优先的政策框架留出了空间,”摩根大通表示。
The danger is not the Japanification of China as the AI-driven export boom acts as a crucial counterweight to weak consumption. Rather, the threat is in the lack of urgency in rebalancing the economy. “Export resilience has given Beijing room to maintain its tech-first policy framework despite weak domestic demand,” Morgan Stanley said.
泡沫破裂后的日本与今天的中国之间的比较并不恰当,部分原因是两国制造业表现的分化。正是中国出口热潮带来的国内后果,在一定程度上导致了关于日本化的争论持续不断。
Comparisons between post-bubble Japan and today’s China are inapt, in part because of the sharp divergence in the performance of both countries’ manufacturing sectors. It is the domestic consequences of China’s export boom that are partly to blame for prolonging the debate over Japanification.