皮利于2004年开始投资买房出租,当时房价上涨,英国房东享有慷慨的税收优惠。
Pilley started investing in buy-to-let properties in 2004, when house prices were rising and UK landlords enjoyed generous tax breaks.
一度,这位55岁的男子在黑弗希尔及周边拥有18套住宅,该镇位于伦敦东北约50英里处。如今他只剩三套,因为工党和保守党政府先后出台的多项措施多年来不断侵蚀他的收益,促使他开始抛售房产。
At one point, the 55-year-old owned 18 homes in and around Haverhill, a town roughly 50 miles northeast of London. Now he’s down to three, after years of measures by both Labour and Conservative governments that have eaten into his returns and convinced him to start selling up.
他说:“你会看着这项投资想:‘你知道吗?我把钱投别处能赚得更多,麻烦还少得多。’”他已拓展至商业地产合同,维护责任更少。
“It just starts to be an investment that you look at and think, ‘Do you know what? I can do a lot better with my money elsewhere for a lot less hassle,’” he said. He’s branched out into commercial property contracts that leave him with fewer maintenance responsibilities.
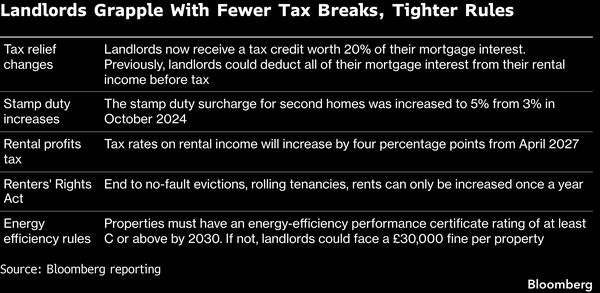
周三的预算案中,英国财政大臣约翰·希利宣布,从2027年4月起将房产收入税提高4个百分点。视个人税率档次而定,税率将升至24%、44%或49%。
In Wednesday’s budget, UK Chancellor John Healey unveiled a 4 percentage point increase in property income tax from April 2027. Depending on an individual’s tax band, that will take rates to 24%, 44% or 49%.
此次增幅取代了希利的前任雷切尔·里夫斯在去年预算案中宣布的拟增2个百分点的计划。过去十年左右,历届政府还削减了抵押贷款利息税收减免,提高了二套房印花税,引入了租金涨幅限制,并以增加房东成本的方式收紧了租赁房产的其他监管。
The increase supersedes a planned 2 percentage point hike announced by Healey’s predecessor, Rachel Reeves, at last year’s budget. Over the past decade or so, successive governments have also reduced tax relief on mortgage interest, increased stamp duty on second homes, introduced limits on rent increases and tightened other regulations around rental properties in ways that increase costs for landlords.
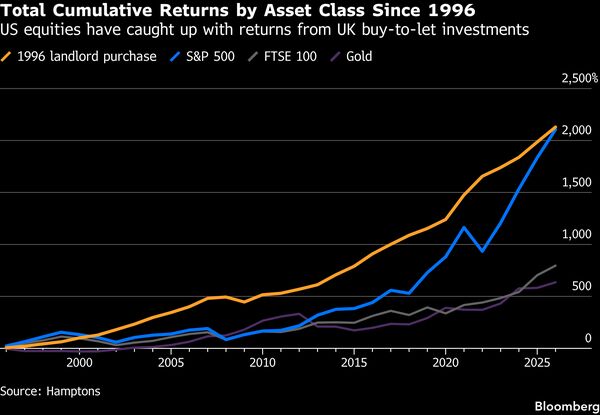
房产中介汉普顿的分析显示,买房出租的早期投资者获得了显著收益——自1996年以来平均总回报率达2130%。但过去五年,股市表现超过了住宅物业,标普500指数远超买房出租的41%回报。随着回报率下降,许多房东正在出售房产。
Early investors in buy-to-let properties have made significant gains, analysis from estate agents Hamptons shows — an average total return of 2,130% since 1996. But in the past five years, stock-market performance has outstripped residential property, with the S&P 500 far exceeding buy-to-let’s 41% returns. As returns diminish, many landlords are selling properties.
抵押贷款经纪公司骑士弗兰克金融的管理合伙人西蒙·加蒙表示,历届政府将“二套房持有,特别是买房出租持有,视为一个可以逐步蚕蚀的政治胜利。”
Successive governments have seen “second-home ownership and particularly buy-to-let ownerships as a political win to chip away at,” Simon Gammon, managing partner at mortgage broker Knight Frank Finance, said.
Gammon 补充道:“除非你购买的是收益率极高的房产,或者你以极低的贷款价值比借款用于投资,否则购买大多数买房出租类房产都讲不通。现在有更好的投资选择。”
“Unless you’re buying a property with a very high yield or you’re borrowing a very low percentage of the value of that property as an investment, it doesn’t make sense” to purchase most buy-to-let properties, Gammon added. “There are better investments out there nowadays.”
尽管《租客权利法案》等措施赋予了租客更多保护,但可供出租的房产数量减少,可能意味着许多人的租金会上涨。根据 SpareRoom 本月发布的数据,过去一年全英可供合租的房间供应量下降了近 5%,而租金现已在英格兰九大区域中的七个地区达到历史新高。
While measures such as the Renters’ Rights Act have given tenants greater protections, a shrinking number of properties to let may mean higher rents for many. Across the UK, the supply of rooms available for flatshare fell by almost 5% over the past year, according to data released this month by SpareRoom, while rents have now reached record highs in seven of the UK’s nine regions.
伦敦房产中介 Jeremy Leaf 表示,周三的预算案中“没有任何内容能鼓励新房东进入买房出租领域,也没有任何内容能说服其他人继续投资。”
Jeremy Leaf, a London estate agent, said that there was nothing in Wednesday’s budget “to encourage new landlords into the buy-to-let sector or anything to persuade others to stay invested.”
据 Ascot Lloyd 独立理财顾问 Harry Beddoe 称,即使是利用现有抵押贷款杠杆、以较小首付放大收益的能力,也正在失去吸引力。
Even the ability to leverage an existing mortgage and magnify gains on a smaller deposit is losing its appeal, according to Harry Beddoe, an independent financial advisor at Ascot Lloyd.
他说:“如果你难以偿还抵押贷款,难以找到租客,然后又难以从该房产中退出,我确实会质疑杠杆能力能起多大作用,其影响有多大。”
“If you are struggling to pay the mortgage, if you are struggling to find tenants and then you’re struggling to have an exit from that property, I do question how much being able to leverage, how significant an impact that is,” he said.
财富管理公司 Evelyn Partners 财务规划合伙人 David Little 表示,一些房产投资者可能更倾向于将资金投入股票或英国政府债券。
Some property investors may prefer to put their capital in stocks or gilts, said David Little, a partner in financial planning at wealth management firm Evelyn Partners.
AJ Bell 个人理财主管 Sarah Coles 表示,投资者应首先充分利用其 ISA(个人储蓄账户)和养老金免税额度。她补充说,对于伴侣而言,共同管理这些额度会有帮助,包括向不工作的一方的养老金缴纳资金。
Investors should maximize their ISA (individual savings account) and pension allowances before doing anything else, Sarah Coles, head of personal finance at AJ Bell, said. For couples, managing these allowances together can be helpful, she added, including paying money into a non-working partner’s pension.
对于已经用尽其他税收减免额度的高税率和额外税率纳税人而言,短期英国国债是一种极佳的税务高效选择。国债票息支付仍需缴纳所得税,但直接购买的国债免征资本利得税。因此,Coles 指出,疫情期间发行的低票息债券尤具吸引力,因为其大部分收益以资本利得而非收入形式实现。
Short-dated gilts are a great tax-efficient option for people who are higher rate or additional rate taxpayers and who have used up their tax allowances elsewhere. Income tax is still payable on gilt coupon payments, but gilts bought directly are not subject to capital gains tax. So low-coupon bonds issued during the pandemic are particularly attractive, noted Coles, because the majority of the return comes in the form of a capital gain, rather than income.
“你以 93、94 便士的价格买入,明知到期时能拿回 100 便士。”现年 53 岁的前投资银行家 James Brand 在 1990 年代开始投资出租房产时,“每一笔闲钱都投入到了购买更多房产上”,他说道。
“You’re buying them for 93, 94 pence, knowing that you will get 100 pence back when you get to maturity.”When James Brand, a 53-year old former investment banker, started investing in rental properties in the 1990s, “every spare penny went into getting more property,” he said.
2003 年,他成为全职房东,最终在伦敦和东南部积累了 14 套房产的组合。“我想我当时背负的债务大约是 400 万英镑(约合 530 万美元)”,他说。
He became a full-time landlord in 2003, eventually building up a portfolio of 14 houses in London and the Southeast. “I think I was running about £4 million [$5.3 million] debt on that,” he said.
但 2015 年保守党政府推出房产减免政策变更后,Brand 开始抛售房产以偿还买房出租抵押贷款。如今他手中剩下六套出租房。
But when changes to property relief were introduced in 2015 by the Conservative government, Brand began selling off properties to pay off his buy-to-let mortgages. He now has six houses that he lets out.
“我在审视这件事,觉得我可能做得更好——在某些方面我确实做得更好——就是把钱存在 ISA(个人储蓄账户)里”,Brand 说。在他看来,进入买房出租领域在很大程度上已不再“具备经济可行性”。“你不妨做点别的”,他说。
“I’m looking at it and I’m thinking I would do better — which I am in some places — just sticking my money in ISAs,” Brand said. In his view, getting into buy-to-let is largely no longer “economically viable.”“You might as well do anything else,” he said.