编辑部美联储上周维持短期利率不变。如果在12月的下次会议上再次这样做,它将需要一个更好的解释。
By The Editors The Federal Reserve held short-term interest rates steady last week. If it does so again at its next meeting in December, it’ll need a better explanation.
近期的通胀数据出奇地糟糕,上周会议后发布的新数据进一步强化了这一信号。美联储偏好的衡量指标——个人消费支出(PCE)价格指数,9月份上涨0.5%,为3月以来最快增速。剔除食品和能源后,核心指数上涨0.3%,同比上升3.1%,高于8月,且仍远高于央行2%的目标。
Recent inflation figures have been surprisingly bad, and new data released after last week’s meeting underlined the message. The Fed’s preferred measure, the personal consumption expenditures price index, rose by 0.5% in September, the fastest since March. Excluding food and energy, the increase was 0.3%, for a year-over-year rise of 3.1%, higher than August and still well above the central bank’s 2% target.
与此同时,经济增长已加速。第三季度,产出以年率3.4%的稳健速度增长。美联储新的政策声明称扩张步伐“强劲”,国内需求“韧性十足”。尽管外界担忧人工智能摧毁的就业岗位将多于创造的岗位,劳动力市场仍处于充分就业状态。
Meanwhile, growth has picked up. In the third quarter, output grew by a solid 3.4% at an annual rate. The Fed’s new policy statement called the pace of expansion “strong” and domestic demand “resilient.”The labor market, despite fears that AI will destroy more jobs than it creates, is still at full employment.
所有这些迹象表明,联邦基金利率目前处于3.75%至4%区间,仍过低。诚然,在中期选举前夕再次加息会显得尴尬。即便现在,最近通胀超预期的部分也很可能是暂时的。关税以及伊朗战争导致的能源成本上升推高了物价;假设没有更多坏消息且预期通胀保持稳定,随着时间的推移,部分超额涨幅应当会消退。
All of which implies that the federal funds rate, at 3.75% to 4%, is still too low. Granted, hiking again just before midterm elections would’ve been awkward. And even now, some of the latest inflation overshoot is likely to be temporary. Tariffs and higher energy costs due to the war in Iran have pushed up prices; with time, assuming there’s no more bad news and expected inflation stays anchored, some of the excess should fade.
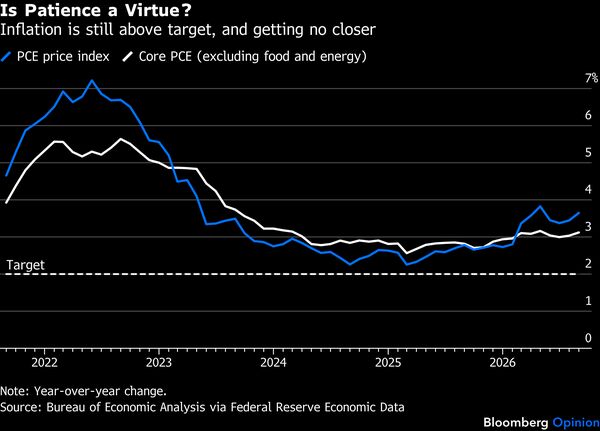
然而,如果美联储像主席凯文·沃什坚持的那样紧盯物价稳定,它不应对现状感到满意。通胀显著高于目标已持续五年多。在某个时刻,预期将发生转变。
Yet if the Fed is tightly focused on price stability, as Chairman Kevin Warsh insists, it shouldn’t be happy with where things stand. Inflation has run significantly above target for more than five years. At some point, expectations will shift.
沃什素以怀疑“前瞻性指引”著称,对于美联储12月开会时可能采取何种行动,他只表示未来六周将是“信息丰富”的时期。毫无疑问。但不太清楚的是,随着信息陆续到来,美联储将如何应对。如果降低通胀的进度缺乏进一步进展,是否需要加息?如果不需要,理由何在?
Warsh, famously skeptical of “forward guidance,” had nothing to say about what the Fed might do when it meets in December, except that the next six weeks would be “information-rich.”No doubt. What’s less clear is how the Fed will respond to this information as it arrives. Would a lack of further progress in lowering inflation call for a rate increase? If not, why not?
克利夫兰联储行长贝丝·哈马克是最新政策决定中两名持不同意见者之一,她主张再加息25个基点。在最近的一次演讲中,她指出,“泰勒”类规则——即将通胀和失业指标与特定的利率路径挂钩——是制定货币政策的一个有用起点。(目前,克利夫兰联储对这一系列规则的汇总显示,建议政策利率的中位数为4.26%。)正如她所强调的,此类规则无法决定政策——经济过于复杂。但它们为美联储提供了一种方式,即通过迫使其说明偏离的理由,使其思路对投资者和公众更加清晰。
Beth Hammack, president of the Cleveland Fed, was one of two dissenters from the latest policy decision, calling for another quarter-point increase. In a recent speech, she noted how “Taylor”-type rules, which tie inflation and unemployment metrics to a particular path for rates, are a useful starting point in framing monetary policy. (Currently, the Cleveland Fed’s summary of this family of rules has a median recommended policy rate of 4.26%.) As she emphasized, such rules can’t dictate policy — the economy’s too complicated. But they offer a way for the Fed to make its thinking clearer to investors and the public by obliging it to say why it’s deviating.
沃什是一位创新者。他成立了专门工作组研究各项美联储政策和做法,并宣布他和同事们将把每年的利率制定会议从八次减少到明年的七次,以及2028年的六次,以便为大局讨论留出更多时间。作为其拟议改革的一部分,哈马克的言论值得认真考虑。排除前瞻性指引——即坚定预测利率走向——是明智之举,除非在特殊情况下。但这仍为解释未来决策将如何考量新信息留出了很大空间。
Warsh is an innovator. He has established task forces to study various Fed policies and practices and has announced that he and his colleagues will move from eight annual rate-setting meetings to seven next year and six in 2028, to allow more time for big-picture discussions. As part of his intended reforms, Hammack’s comments deserve careful consideration. Ruling out forward guidance — firmly predicting what rates will be — is wise, except in extraordinary circumstances. But that leaves plenty of room for explaining how future decisions will take account of new information.
无论如何,主席最好明白,他目前的做法——即美联储“致力于维护物价稳定”,未来几周将是“信息丰富”的——保质期有限。
In any event, the chairman had better understand that his current approach — that the Fed is “committed to price stability” and the coming weeks will be “information-rich” — has a limited shelf life.