中国的债券表现全球领先,躲过了全球债务的抛售潮。一些基金经理正在布局,因人民币走强和国内经济疲软而预期进一步上涨。
China’s world-beating bonds have dodged the selloff in global debt and some fund managers are positioning for further gains due to a strong yuan and a sluggish domestic economy.
根据彭博全球指数,作为全球第二大经济体的中国债券,在过去12个月里为以美元计价的投资者带来了近10%的回报。相比之下,全球债务基准下跌了2.2%,而美国国债下跌了2.1%。
Bonds from the world’s second-biggest economy returned almost 10% over the past 12 months to dollar-based investors, according to Bloomberg global indexes. In comparison, a global debt benchmark lost 2.2%, while Treasuries declined 2.1%.
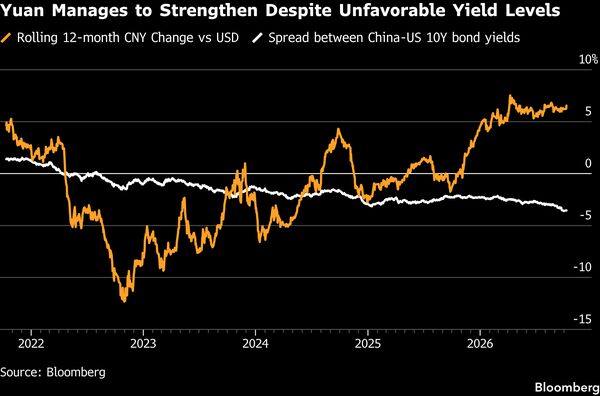
这种对比更加引人注目,因为中国10年期国债收益率与美国同期限国债收益率的折价幅度本月扩大至历史最高水平。北京得益于其庞大的石油储备以及向电动交通的逐步转型,相对免受高油价影响,这有助于推动其货币和债券的上涨。
The contrast is all the more notable given that the discount of China’s 10-year sovereign bond yield to its US counterpart widened to a record this month. Beijing’s relative insulation from higher oil prices, thanks to its large stockpiles and growing shift to electrified transport, has contributed to the gains of both its currency and bonds.
“如果一只基金在过去几年里超配人民币债券,那么它就有相当大的机会跑赢全球指数,”香港富达国际亚洲固定收益部主管Lei Zhu表示。该基金公司表示,已收到来自世界各地关于中国债券的咨询,因为一些投资者希望从低配转向中性配置。
“If a fund was overweight yuan bonds over the past few years, you would get a pretty good chance to outperform the global index,” said Lei Zhu, head of Asian fixed income at Fidelity International in Hong Kong. The fund house has received queries about China bonds from around the world, as some investors are looking to shift from underweight to neutral, she said.
中国10年期国债收益率目前为1.67%,低于同期限美国国债收益率352个基点。该利差本月触及362个基点,为自彭博2002年开始编制该数据以来的最高水平。
China’s 10-year bond yield, at 1.67%, is 352 basis points below that of comparable-maturity Treasuries. The spread touched 362 basis points this month, the widest level since Bloomberg began compiling the data in 2002.
中国债券的超额表现凸显了人民币升至四年高点以及国内经济疲软如何提升了该国主权债券对全球投资者的吸引力。这一稳步增长与最近几个月大多数主要债券市场因对失控通胀和政府债务上升的担忧而遭受的巨额损失形成鲜明对比。
The outperformance of Chinese bonds highlights how the yuan’s ascent to a four-year high and a lukewarm domestic economy are boosting the appeal of the nation’s sovereign debt to global investors. The steady gains stand in stark contrast to the heavy losses sustained by most major bond markets in recent months amid fears of runaway inflation and rising government debt.
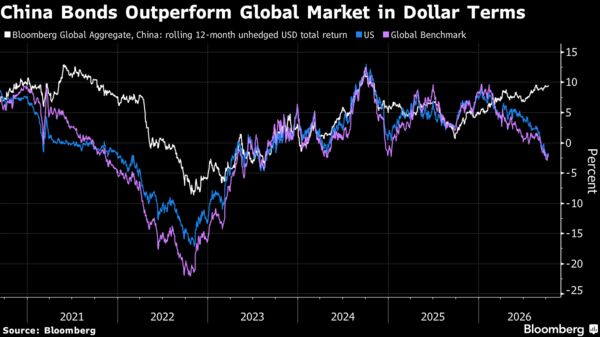
人民币今年对美元已升值4.4%,并有望实现连续第八个季度上涨。与此同时,中国10年期国债收益率自去年12月底以来已下降18个基点。
The yuan has strengthened 4.4% against the dollar this year and is on track for an eighth quarterly advance. Meanwhile, China’s 10-year bond yield has fallen 18 basis points since the end of December.
专营投资公司Arkevium Capital看好中国债券,人民币走强是重要原因。
Proprietary investment firm Arkevium Capital is bullish on Chinese bonds, and the yuan’s strength is a big reason.
Arkevium Capital创始人Maxence Visseau在迪拜表示,中国债券是一项极具吸引力的动量交易,因为其总回报自2020年以来已跑赢美国消费者物价通胀,这与主要发达市场债券形成鲜明对比。
China’s bonds are a compelling momentum trade because their total return has outpaced US consumer price inflation since 2020, unlike those of major developed markets, said Maxence Visseau, founder of Arkevium Capital in Dubai.
Visseau说:“我对中国国债持续看好,但我认为进一步跑赢将取决于人民币。”他使用了人民币的另一称呼“renminbi”。他表示,能够应对中国较低收益率、制度性限制和地缘政治不确定性所带来风险的全球投资者,有充分理由增加配置。
“I remain constructive on Chinese government bonds, but I think further outperformance will depend on the renminbi,” Visseau said, using another name for the yuan. Global investors who can manage the risks posed by China’s lower yields, institutional constraints and geopolitical uncertainties have a case for increasing their allocations, he said.
海外对中国债务的需求依然相对低迷。截至8月底,全球投资者持有2.03万亿元人民币(约3030亿美元)中国债券,与去年底的2万亿元几乎持平,较2022年1月2.52万亿元的高点有所下降。
Overseas demand for Chinese debt remains relatively muted. Global investors held 2.03 trillion yuan ($303 billion) of the nation’s debt at the end of August, almost unchanged from 2 trillion yuan at the end of last year and down from a high of 2.52 trillion yuan in January 2022.
宏利投资管理香港高级投资组合经理Paula Chan表示,中国债券收益率将继续受到该国比许多其他经济体更能吸收油价冲击的能力,以及境内优质固定收益资产持续短缺的支撑。
Chinese bond yields will remain anchored by the nation’s ability to absorb an oil-price shock better than many other economies, as well as a continuing shortage of high-quality fixed-income assets onshore, said Paula Chan, a senior portfolio manager at Manulife Investment Management in Hong Kong.
Chan称,其管理的中国债券基金目前押注中国收益率曲线将走平——即长期收益率将相对短期收益率下行。这一押注反映了她的观点:下一阶段的跑赢行情将由收益率稳定驱动,而非债券价格进一步上涨。其他基金则不那么热情。
Chan said her Chinese bond fund is currently betting the nation’s yield curve will flatten — that is, longer-maturity yields will fall relative to shorter-term ones. The bet reflects her view that the next leg of outperformance will be driven by yield stability rather than further gains in bond prices. Other funds are less enthusiastic.
联博基金亚洲固定收益联席主管Eric Liu表示,从收益角度看,中国国债不太具吸引力。
Chinese government bonds are not particularly appealing in yield terms, said Eric Liu, co-head of Asia fixed income at AllianceBernstein.
他指出,点心债——即在大陆以外发行和结算的人民币计价证券——提供更具吸引力的收益率溢价,目前可能是平衡投资组合的更好选择。
Dim sum bonds, which are yuan-denominated securities issued and settled outside Mainland China, offer more attractive yield premiums and may be a better investment right now to balance a portfolio, he said.
中国债券的另一个利好因素是,该国正努力进一步开放其债务市场,作为其长期推动人民币国际化的一部分。
Another tailwind for Chinese bonds is the nation’s efforts to further open up its debt market as part of its long-term efforts to internationalize the yuan.
“随着中国成为传统全球债券配置的有益补充,中国债券在全球投资组合中的作用正在逐步演变,”新加坡M&G Investments亚洲固定收益投资组合经理William Xin表示。
“The role of Chinese bonds in global portfolios is gradually evolving” as China emerges as a useful complement to traditional global bond allocations, said William Xin, a portfolio manager for Asian fixed income at M&G Investments in Singapore.
“历史上,中国债券往往主要从收益率的角度来看待。如今,投资者越来越认识到其分散投资的好处,以及其与发达市场固定收益的相对低相关性,还有来自货币回报的潜在贡献,”他说。
“Historically, Chinese bonds were often viewed primarily through the lens of yield. Today, investors are increasingly recognizing their diversification benefits, relatively low correlation with developed-market fixed income, and the potential contribution from currency returns,” he said.