经济学家称,欧洲央行将在12月最后一次加息,此前将在下周暂停,这与市场押注的未来将有更多加息形成对比。
The European Central Bank will lift interest rates for the final time in December following a pause next week, economists say, at odds with market bets on far more hikes lying ahead.
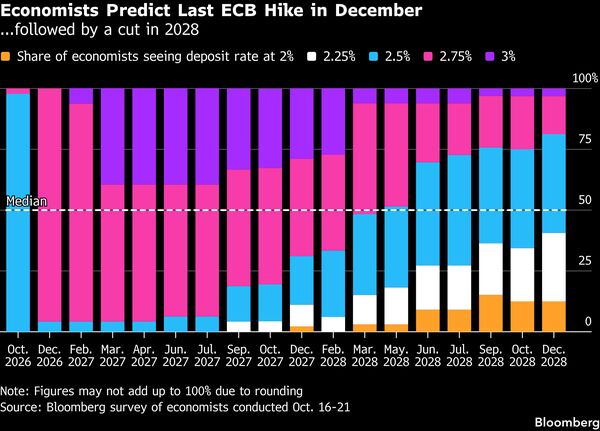
彭博调查中绝大多数受访者表示,存款利率将在欧洲央行2026年最后一次会议上上调25个基点至2.75%,并维持这一水平直到2028年5月。相比之下,交易员预计未来一年将再加息三次。
An overwhelming majority in a Bloomberg survey said the deposit rate will be raised by a quarter-point to 2.75% in the ECB’s final meeting of 2026 and stay there until May 2028. Traders, by contrast, see three more moves over the next year.
这一结果巩固了长期存在的分歧,即政策制定者需要多大力度采取行动,才能将消费者价格涨幅从目前近乎翻倍的水平拉回2%。投资者的关注点锁定在油价的稳步上涨上,而分析师指出,对通胀的溢出效应持续缺失。
The findings cement a long-standing divide over how aggressively policymakers will have to act to bring consumer-price gains back to 2% from almost double that now. While investors’ focus is locked on the steady advance of oil prices, analysts point to the continued absence of knock-on effects for inflation.
荷兰合作银行经济学家巴斯·范·赫芬表示:“仍没有迹象表明能源通胀正在向更广泛的工资和价格设定蔓延。欧洲央行不需要加快加息步伐,可以等到12月。” 借贷成本因伊朗战争已上调两次,分别在6月和9月。虽然通胀已加快,上月达到3.8%,但产出表现比大多数预期的更具韧性。
“There are still no signs that energy inflation is spreading into broader wage and price setting,” said Bas van Geffen, an economist at Rabobank. “The ECB doesn’t need to accelerate its hiking cycle and can wait until December.”Borrowing costs have been increased twice in response to the Iran war, in June and September. While inflation has quickened and reached 3.8% last month, output has proven more resilient than most expected.
官员们希望防止能源冲击内化于经济中,并曾考虑本月再次加息。不过,按季度节奏加息的可能性仍更大,届时12月会议将发布新的预测。
Officials want to prevent the energy shock from becoming embedded in the economy and had toyed with another hike this month. A quarterly pace remained likelier, though, with fresh projections due at December’s meeting.
9月的展望预计,今年国内生产总值将增长0.9%,2027年增长1.4%,伴随消费者价格分别上涨3%和2.5%。在不利情景下,通胀预计将达到3.1%和3.2%。
September’s outlook envisaged gross domestic product rising 0.9% this year and 1.4% in 2027, accompanied by increases in consumer prices of 3% and 2.5%. In an adverse scenario, inflation was projected to reach 3.1% and 3.2%.
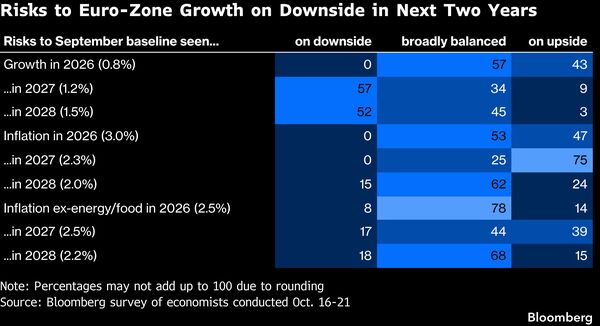
随着油价突破每桶110美元,超过三分之二的经济学家认为欧元区经济比9月的基准情景更糟。
With oil prices topping $110 a barrel, more than two-thirds of economists consider the euro-zone economy to be worse than September’s baseline.
“头部通胀保持高位的时间越长,就越难否认对工资、价格和预期的二轮效应,”柏林国际管理学院讲师丹尼斯·申说。“对欧洲央行来说,通胀超调现在远比通胀不足构成更大的中期风险。”中东地区之外,政策制定者正在评估债券收益率上升在多大程度上收紧了金融状况。欧洲央行行长克里斯蒂娜·拉加德等人认为,这将抑制经济增长并限制能源价格向通胀的传导。
“The longer headline inflation stays high, the harder it becomes to dismiss second-round effects for wages, prices and expectations,” said Dennis Shen, a lecturer at the International School of Management in Berlin. “For the ECB, an inflation overshoot is now a far greater medium-term risk than an undershoot.”Beyond the Middle East, policymakers are assessing how much rising bond yields are tightening financial conditions. President Christine Lagarde and others have argued this will curb economic growth and limit energy transfer to inflation.
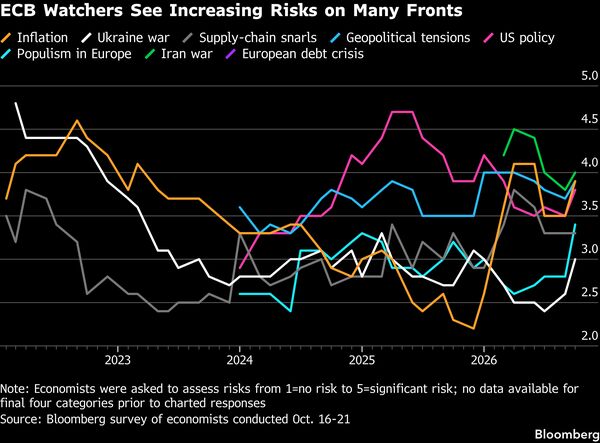
本周,法国基准国债收益率首次自2002年以来触及5%,一些投资者甚至认为存在新的欧元区债务危机风险。关于情况必须有多糟糕,欧洲央行才会动用其尚未使用过的灭火工具——传递保护工具,猜测不断升级。
With the yield on benchmark French debt hitting 5% this week for the first time since 2002, some investors even see a risk of a new euro debt crisis. Speculation is mounting on how bad things would have to get before the ECB stepped in with its as-yet-unused firefighting tool, the Transmission Protection Instrument.
经济学家认为门槛非常高,有70%的人否定任何形式的干预,约90%的人排除了传递保护工具,该工具旨在应对威胁欧元区政策传递的不合理、无序的市场动态。
Economists reckon the bar is very high, with 70% dismissing intervention in any form and about 90% ruling out TPI, which was fashioned to counter unwarranted, disorderly market dynamics that threaten policy transmission across the euro area.
“债券收益率的上升可以由全球资本需求增强以及许多国家公共财政恶化很好地解释,”瑞士萨拉萨因银行首席经济学家卡斯滕·尤尼乌斯说。“在这种情况下,欧洲央行很难证明使用传递保护工具是合理的。”一些经济学家认为,采取不那么激进的措施是可能的,例如口头干预、在利率方面释放鸽派信号,或暂停量化紧缩,即欧洲央行让其在过去危机期间购买的债券到期而不再展期。
“The increase of bond yields can be explained very well by stronger global capital demand and a deterioration of public finances in many countries,” said Karsten Junius, chief economist at Bank J Safra Sarasin. “It would be difficult for the ECB to justify the use of TPI in these circumstances.”Some economists deem less radical steps possible, like verbal interventions, dovish signals on rates or a halt in quantitative tightening, under which the ECB lets the stock of bonds it during past crises mature without them being rolled over.
“只要法国不愿意自助,欧洲央行目前几乎无法帮助法国,”英银集团全球宏观主管卡斯滕·布热斯基说。“随着债券市场接管欧洲央行的工作,欧洲央行唯一能做的就是语气稍微鸽派一些,并试图降低加息预期。”
“There’s very little the ECB can currently do to help France as long as France is not willing to help itself,” said Carsten Brzeski, ING’s global head of macro. “The only thing the ECB could do, as bond markets are taking over the ECB’s job, is to sound somewhat more dovish and try to scale down rate-hike expectations.