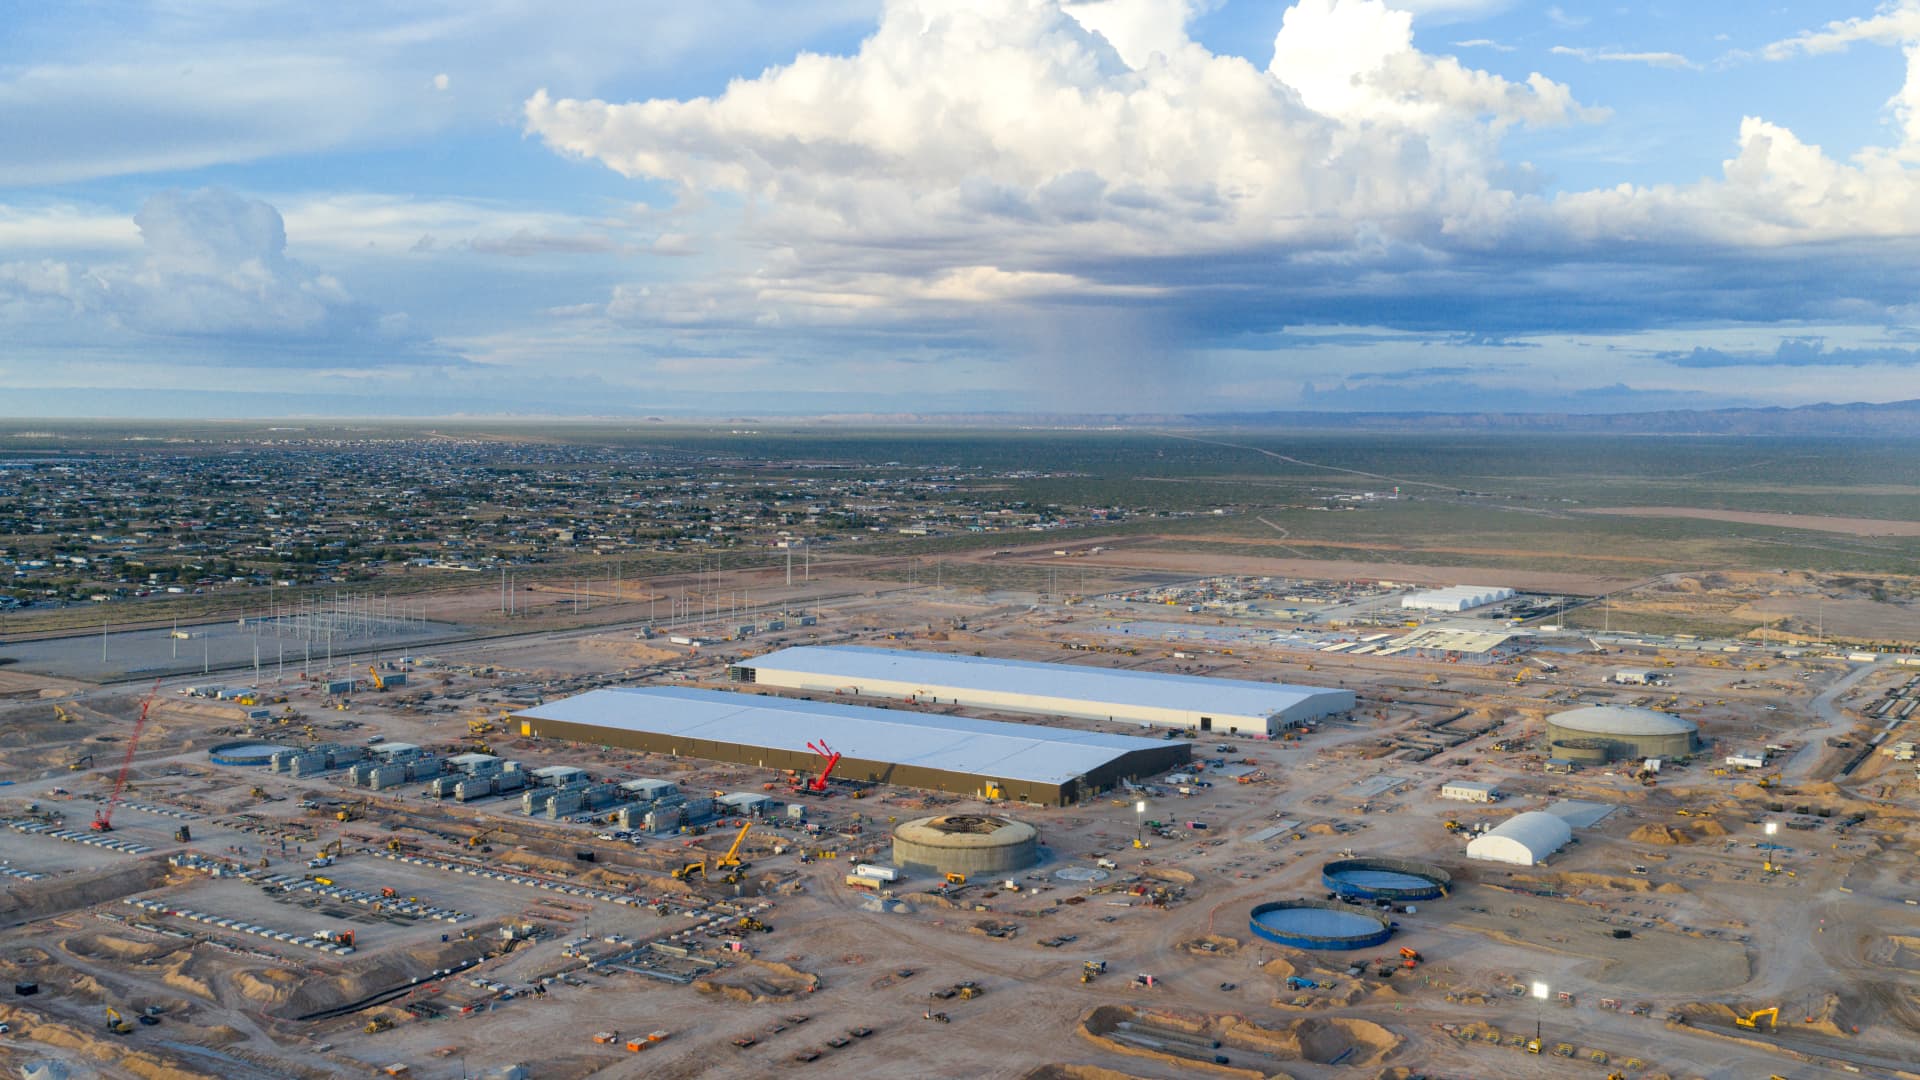
AI融资窗口正在关闭,所有人都想抢上这趟列车。显然,抢夺资本的竞赛已全面展开,因为越来越多专注于人工智能的公司感受到压力,必须持续建设以跟上步伐。我们清楚,对所有AI相关事物的需求——从模型、智能体到芯片、数据中心——持续不断增长。但华尔街在被称为第四次工业革命的下一阶段中,正变得更加挑剔,慎重选择押注哪些公司。
The AI funding window is closing, and everyone wants a seat on the train. Clearly, the rush to raise capital is on, as more and more artificial intelligence-focused companies are feeling pressure to continue building to keep up. We know the demand for everything AI — from models to agents to chips to data centers — keeps growing and growing. But Wall Street is now becoming more discerning about which companies it wants to bet on during the next phase of what is being called the fourth industrial revolution.
对资本的无尽渴求已成为瓶颈。与最初向潜在AI赢家广撒网的做法不同,这一阶段资金已不够分。近几周,较小的云服务商成为这轮合理化浪潮的前沿。CoreWeave已成为“新式云服务商是否过多”这一辩论的焦点。其股价从5月6日盘中近139美元的年内高点下跌了60%。周一一度跌至52周低点51美元上方,随后随大盘回升。
The insatiable need for capital is the bottleneck. Unlike the initial push to spread money around to bet on would-be AI winners, there is not enough to go around at this stage. The smaller cloud companies in recent weeks have been at the forefront of this rationalization push. CoreWeave has become the face of the "do we have too many neoclouds" debate. The stock has lost 60% from its year-to-date high of nearly $139 on May 6. It hit a 52-week low of just above $51 on Monday before moving higher with the broader market.
毫无疑问,一些全球最大的公司同样需要更多资金。Meta Platforms、SpaceX和Anthropic周一凭借各自计划从不断缩水的资本蛋糕中分得一杯羹、以推进AI雄心的下一步,占据了头条。Meta宣布计划分三步筹集高达950亿美元:首先,以每股642.62美元的价格增发价值225亿美元的A类普通股(即我们和大多数投资者目前持有的股份);另外增发125亿美元优先股;以及不早于明年通过“随时发行”方式发行C类股筹集600亿美元。
Make no mistake about it, some of the biggest companies in the world need more money, too. Club name Meta Platforms , as well as SpaceX and Anthropic, are dominating the headlines on Monday with plans to raise their share of the shrinking capital pie for the next legs of their AI ambitions. Meta announced plans to raise as much as $95 billion in three steps: first, an additional $22.5 billion worth of Class A common (what we and most investors currently own) priced at $642.62 per share; another $12.5 billion of preferred shares; and $60 billion no sooner than next year via an at-the-market offering for Class C shares.
我们上周才得知创建无投票权C类股作为未来融资工具的计划。谁曾想“未来”仅在短短几天之后?埃隆·马斯克表示,SpaceX已完成一笔400亿美元的债务融资交易,用于采购图形处理单元(GPU)。
We learned about the plans to create the non-voting Class C shares last week as a vehicle to raise money in the future. Who knew the future was only a few short days away? Elon Musk said that SpaceX has closed a $40 billion debt financing deal for graphics processing units (GPUs).
我们此前获悉,SpaceX 将寻求完全基于英伟达硬件构建基础设施。请记住,虽然 SpaceX 是一家火箭和卫星公司,但它也是一家大规模的 AI 基础设施公司。Anthropic 公布了其首次公开募股(IPO)招股说明书。这家前沿 AI 实验室的 IPO 估值可能高达 2 万亿美元,已向美国证券交易委员会(SEC)提交了所谓的 S-1 注册声明。
We previously learned that SpaceX would look to exclusively build on Nvidia hardware. Remember, while SpaceX is a rocket and satellite company, it is also a massive AI infrastructure company. Anthropic dropped its initial public offering prospectus. The frontier AI lab, whose IPO valuation could be as high as $2 trillion, filed its so-called S-1 with the Securities and Exchange Commission.
股份定价和初始募资规模尚未披露,将稍后公布。不过,考虑到该公司在文件中披露的财务承诺水平,可以相当肯定地说,募资规模将达数百亿美元,甚至可能达到 1000 亿美元。这三件事只是疯狂抢夺资本的最新案例,这种抢夺正给 AI 交易带来压力。多头认为,需求的存在意味着算力是必要的,现在的投资将带来正向回报。
The share pricing and initial raise were not disclosed. They will come later. However, it is probably safe to say it will be for tens of billions of dollars, if not $100 billion, given the level of financial commitments the company has disclosed in the filing. These three are just the latest in a mad rush for capital that has been putting a strain on the AI trade. The bulls argue that the demand means the compute is needed and the investments being made now will provide positive returns.
空头则认为,正在发生严重的资本错配,因为 AI 炒作不会在未来转化为 AI 利润,大家预测的算力需求也不会实现。马斯克在 X 上发帖确认 SpaceX 的债务融资时,将这些挑战置于具体背景下:“截至过去几周,债务市场几乎完全切断了对任何没有独立于 AI 数据中心的实质性收入的公司的资金供给。……这意味着 200 多家新云服务商将面临‘小鱼苗’级别的死亡和整合。一些能熬过去,但不会太多。”
The bears argue that there is a grave misallocation of capital underway, as the AI hype won't be met with AI profits down the line, and the compute demand everyone is predicting won't materialize. In a post on X confirming SpaceX's debt raise, Musk put those challenges in context . "As of the past few weeks, debt markets have almost entirely shut off access to money for any company that doesn't have substantial revenue independent of AI data centers. ... That means the 200+ neoclouds are going to see guppy-level death and consolidation.
新云服务商确实面临真正的问题,这一点毫无疑问。对我们而言更大的问题是:这会不会成为其他所有人的问题?我们认为不会,正如吉姆·克莱默在周日专栏中所写,他没有放弃 AI 交易,特别是对于马斯克口中“小鱼苗”交易另一方的那些公司。我们说的是那些业务不止于 AI 的公司。
Some will make it through, but not many." The neoclouds have a real problem. There is little doubt about that. The bigger question for us: Is that going to be a problem for everyone else? We don't think so, as Jim Cramer wrote in his Sunday column , saying he is not giving up on the AI trade, especially for the companies on the other side of Musk's "guppy" trade. We're talking about the ones that do more than AI.
上周,我们指出 Meta 超级智能实验室(MSL)的关键战略优势在于:Meta Platforms 这家更大的公司拥有一项极其盈利的核心广告业务,这使 MSL 相对于 Anthropic 和 OpenAI 等纯 AI 实验室具有结构性优势。在基础设施层面,微软、亚马逊和 Alphabet 等超大规模云服务商也存在类似优势。微软的其他业务是企业软件,广泛存在于大多数个人和工作电脑中。
Last week, we argued that the key strategic advantage for the Meta Super Intelligence Lab (MSL) is that Meta Platforms, the broader company, has a wildly profitable core advertising business that gives MSL a structural advantage versus pure-play AI labs like Anthropic and OpenAI. A similar advantage can be found at the infrastructure layer, with hyperscalers Microsoft , Amazon , and Alphabet . Microsoft's other business is enterprise software found most on most personal and work computers.
亚马逊拥有电商业务。Alphabet 与 Meta 一样,拥有强劲的广告业务。如果许多低质量的新型云服务商因缺乏资金而倒闭,从长远来看,这应被视为对幸存者的利好。(然而,无法回避的是,任何新型云服务商的倒闭都会带来短期的头条风险。投资者会先抛售,事后再问问题。)原因在于,如果一家新型云服务商倒闭,需求不会蒸发。
Amazon has e-commerce. Alphabet, like Meta, has a strong ad business. If many lower-quality neocloud players go under due to lack of funding, then it should read as a positive for the survivors long-term. (However, there is no getting around the near-term headline risk of any neocloud blowups. Investors will be selling first and asking questions later.) The reason why is that demand won't evaporate if a neocloud goes under.
与 CoreWeave、Nebius 或 Iren 等公司做生意的企业,并非专门想与这些特定供应商合作,而是看中它们以喜欢的价格和服务所提供的千兆瓦级算力。由于行业已围绕英伟达和少数定制芯片制造商等寥寥几家参与者实现标准化,而这些厂商又与吸纳了绝大部分过剩资本的大型超大规模云服务商捆绑在一起,客户迁移工作负载不会成问题。
The companies doing business with CoreWeave, Nebius , or Iren aren't after doing business specifically with those providers, as much as they are after the gigawatts of compute they have stood up at prices and services they like. Because the industry has standardized around a few players, like Nvidia and a few custom chipmakers, tied into the larger hyperscalers that are the ones soaking up all the excess capital. It won't be an issue for the customers to move their workloads.
这是一个简单的等式:供应商减少,需求不变,意味着每个供应商的份额增加。底线在于,正如任何行业在动荡期通常出现的情况那样,如果麻烦来临、参与者开始接连倒下,最终能站稳脚跟并收获回报的,将是那些拥有财务韧性的企业。这又把我们带回到微软、Alphabet 和亚马逊等最大牌企业身上——这些都是“俱乐部股票”,且本周都将发布季度财报。
It's a simple equation: fewer suppliers, with equal demand, amounts to more share for each supplier. Bottom line As is usually the case with choppy periods in any given industry, if trouble hits and players start getting their legs taken out from under them, it's those that have the financial durability to come out standing on the other side and reap the rewards. That brings us back to the biggest names, like Club stocks Microsoft, Alphabet, and Amazon, which are all set to report quarterly results this week.
我们预计,资金问题将成为这些公司财报后电话会议讨论的热门话题。在周一的晨会上,吉姆认为,继 Meta 周一的举动以及 Alphabet 夏季 850 亿美元的股票出售之后,微软和亚马逊将面临最大的融资压力。瑞银指出,亚马逊 2027 年的资本支出计划可能超过 3000 亿美元,尽管该行分析师上调了这家云计算和电商巨头的目标价,并重申“买入”评级。
We expect funding to be the hot topic of conversation during their post-earnings conference calls. During Monday's Morning Meeting , Jim thought that Microsoft and Amazon would be feeling the most heat to raise funds following Meta's move Monday and Alphabet's $85 billion stock sale over the summer. UBS suggests that Amazon's 2027 capital expenditures plan could exceed $300 billion, even as the analysts raised their price target on the cloud and e-commerce giant and reiterated their buy rating.
瑞银的研报切中要害,呼应了吉姆周末专栏的结论。近期宜保持谨慎。由于融资前景不明,我们近几周确实已减轻了 AI 仓位,包括周五退出博通。但从长远来看,你必须坚持这笔交易,精选像超大规模云服务商和英伟达这样的标的,并利用最优质股票的回调机会买入,“因为这场革命是真实的”。正如吉姆所言,问题在于:“最终还能剩下几家?”
The UBS note gets at the heart of the issue and speaks to the conclusion of Jim's weekend column. Caution is warranted in the near term. We've certainly lightened up on our AI exposure in recent weeks, including an exit of Broadcom on Friday, due to funding uncertainty. Long term, however, you have to stick with the trade, pick your spots like the hyperscalers and Nvidia, and take advantage of weakness in the highest quality names, "because the revolution is real." The question, as Jim puts it: "How many will be left?" ()